Enter at least two characters to search.
SUGGESTED RESULTS THERE ARE NO SUGGESTED RESULTS
Q3’26 Earnings
 0 0
Scroll down 
Press kit
Documentation
[28-10-2026
Press Release
[28-10-2026
9M'26 Financial Report
[28-10-2026
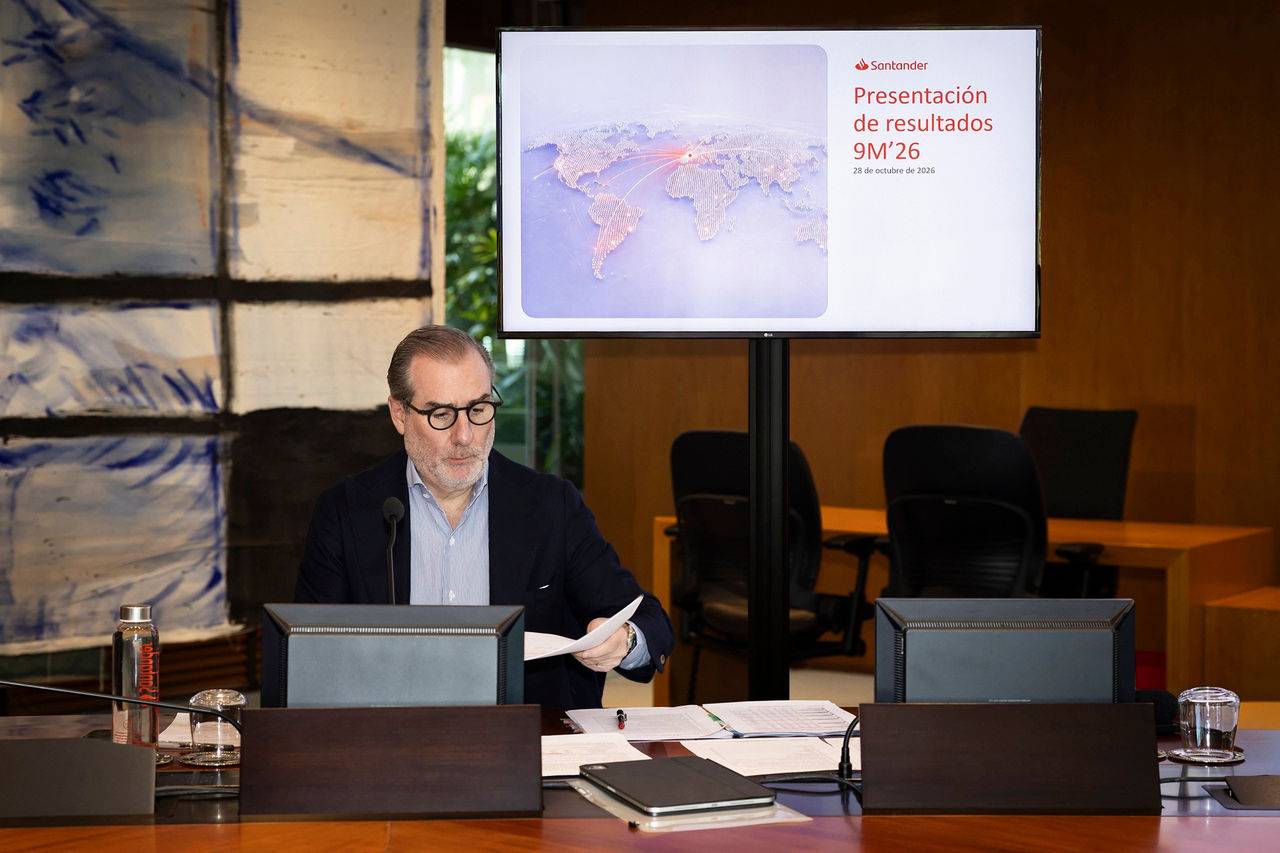
9M'26 Earnings Presentation
[Download Documentation
Pictures
[28-10-2026
Picture in high quality
[Download Pictures
28/10/2026 13:00 CEST
Don't miss these key takeways
drop dowm
-
Revenue reached €46.8 billion (+8%), with strong net interest income and net fee income growth, driven by more customers, higher activity and increased volumes across global businesses[2].
-
ONE Transformation is delivering efficiency gains (costs -1% excluding M&A) as well as higher revenue, resulting in strong growth in net operating income (+14%) and an improvement in the efficiency ratio to 42.6%.
-
Loans and customer fundsboth increased 16% in constant euros, driven by higher customer activity and the incorporation of TSB and Webster. Excluding these acquisitions, loans increased by 6% and customer funds by 8%.
-
Underlying profit in Q3 reached €3.8 billion, up 19%.
-
Santander completed the acquisition of Webster on 20 August, strengthening Santander’s US franchise, expanding its customer base by 4.2 million customers and adding a high-quality, relationship-driven deposit base.
-
The 2026 interim cash dividend of 12.70 euro cents per share will be paid on 2 November. Total remuneration against H1’26 amounts to approximately €3,660 million.
-
Santander is comfortably on track to meet its 2026 targets, which exclude the impact of M&A: mid-single-digit revenue growth, costs down, both in constant euros; higher profit (vs €14.1 billion in 2025); and a CET1 ratio of 12.8-13%[3].
"; htmlDivScript.append(htmlScript); }
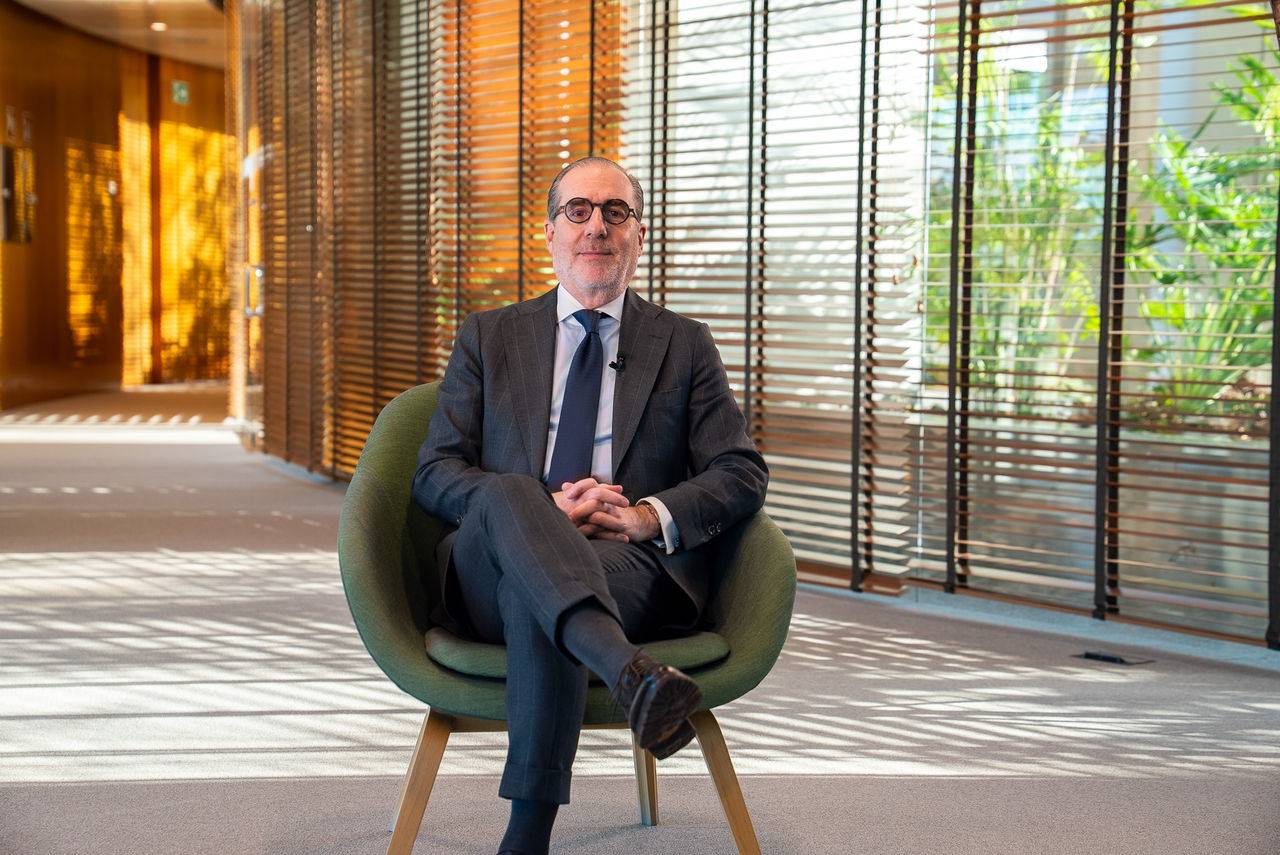
Héctor Grisi, chief executive officer, Banco Santander
Santander continued to grow its customer base, adding 17 million customers over the last twelve months to 189 million. This reflects strong commercial momentum across all businesses and the addition of eight million customers from TSB and Webster following the completion of both acquisitions, on 30 April and 20 August, respectively.
The bank continued to improve profitability and create value for shareholders. Underlying return on tangible equity (RoTE) was 16.0% (+1.1 percentage points). Statutory earnings per share (EPS) increased 25% and tangible net asset value (TNAV) plus cash dividend per share increased 11%, reflecting higher profitability and disciplined capital allocation.
Business volumes remained strong. Loans and customer funds (deposits + mutual funds) both increased 16% in constant euros, supported by solid commercial momentum across the global businesses and the incorporation of TSB and Webster. Excluding acquisitions, loans increased 6% and customer funds 8% (deposits +6%) in constant euros. Loan growth was driven by mortgages in Retail, auto lending in Openbank and double-digit loan growth in CIB and Wealth with a focus on capital-efficient growth.
Total revenue increased 8% to €46,807 million. Net interest income increased 10% (+7% excluding M&A) to €34,614 million and net fee income increased 9% (also +9% excluding M&A) to €10,349 million, reflecting higher customer activity, deeper customer relationships and business volume growth across all global businesses. Around 95% of group revenue is linked to customer activity.
Total costs fell 1% excluding TSB and Webster (-2% in constant euros), reflecting continued efficiency gains from ONE Transformation, the group's programme to move to a common operating model built on shared global platforms. Net operating income increased 14% to €26,882 million and the efficiency ratio improved by 2.8 percentage points to 42.6%, supported by structurally lower costs and higher revenue. The group also continued to deploy AI across its businesses at scale. This generated €194 million of business value (higher revenue, lower costs and lower loan-loss provisions) during the year through better customer service, higher productivity and commercial growth.
Loan-loss provisions increased 13% (+10% in constant euros), mainly reflecting broader market trends in Argentina. Excluding Argentina, provisions increased 6% in constant euros, in line with organic loan growth. Credit quality remained solid, with a cost of risk of 1.16%, supported by prudent risk management, diversified exposure and low unemployment levels across the bank's markets. The non-performing loan ratio improved to 2.90% from the previous quarter (-3 basis points) and remains at low levels, with a coverage ratio of 64%.
The CET1 capital ratio stood at 12.7%. Excluding the -147 basis point impact from the Webster acquisition, the ratio increased 14 basis points in the quarter, with 19 basis points of net organic capital generation. Santander remains on track to meet its year-end CET1 target of 12.8% to 13%, at the high end of its 12-13% operating range.
Santander continued to deliver attractive shareholder returns. In September, the board approved an interim cash dividend of 12.70 euro cents per share against 2026 results, 10% higher than its 2025 equivalent, to be paid on 2 November. In August, the bank launched a share buyback programme of up to c.€1.8 billion against H1 2026 results. Total shareholder remuneration against H1 2026 results will be approximately €3,660 million, 8% higher than a year earlier and equivalent to about 50% of H1 underlying profit.
With that programme, Santander will have delivered c.€9 billion towards its plan to distribute at least €10 billion through share buybacks against 2025 and 2026 results and excess capital[4].
Outlook
Santander reiterates all its 2026 targets, which exclude the impact of M&A in 2025 and 2026. These are mid-single-digit revenue growth and lower costs in constant euros, profit above the €14.1 billion reported in 2025, and a CET1 ratio between 12.8% and 13%3. Revenue growth is expected to continue to be supported by customer activity, with net fee income growing faster than net interest income. Cost discipline and ONE Transformation will continue to drive positive operating leverage. Santander also reiterates the three-year plan set out at its Investor Day last February: by 2028, the group targets a RoTE above 20%, profit above €20 billion and more than 210 million customers, supported by scale, network effects and continued improvements in productivity and capital allocation.

We once again delivered strong results in the first nine months, with earnings per share up 25% and growing momentum across the group. We added 17 million customers over the last twelve months, driven by strong commercial activity and the addition of TSB and Webster, while loans and customer funds both increased 16% year-on-year.
Ana Botín, Banco Santander executive chair
Global businesses (9M 2026 vs 9M 2025)
To better reflect the performance of each business, the year-on-year changes provided below are presented in constant euros unless stated otherwise. Variations in current euros are available in the financial report.
Retail & Commercial Banking’s underlying profit grew 12% to €6,445 million, supported by higher activity and net fee income, lower costs (-1% or -5% excluding M&A) and efficiency gains from the bank’s global platforms, which are also improving customer service. Loans grew by 16% (+3% excluding M&A), mainly driven by higher mortgage lending, while deposits increased by 16% (+6% excluding M&A), reflecting strong customer activity across its footprint. ONE Transformation continues to progress at pace, with product digitalization driving digital sales (+19%), the customer interaction platform now deployed in Spain and the global app launched in Uruguay, now live in five countries. RoTE improved to 17.7%.
Openbank, which integrates Santander's global consumer finance businesses and its digital bank, achieved a profit before tax of €2,544 million, excluding UK motor finance provisions, up 13%, supported by revenue growth, mainly driven by higher net interest income, and lower costs. Underlying profit amounted to €1,407 million, affected by the UK motor finance provisions and the end of electric vehicle tax incentives in the US in 2025. The efficiency ratio improved to 40.4%, while cost of risk stood at 2.10%. Loans increased 7% (+3% excluding Webster), driven by auto lending, while deposits increased 37% (+2% excluding Webster), supported by the digital bank.
CIB reported an underlying profit of €2,433 million (+15%), driven by strong revenue growth (+14%) across all business lines, especially in Global Banking and Global Markets supported by continued success of growth initiatives and a diversified business model. The solid execution of the strategy, focused on disciplined capital allocation, drove RoTE to 19.2%, while maintaining a leading position in efficiency.
Wealth Management & Insurance, which comprises the Private Banking and the Insurance & Asset Management Solutions businesses, increased its underlying profit by 19% to €1,651 million, driven by revenue growth on the back of client inflows and the focus on fee-generating activities. Assets under management reached new record levels of €588bn (+11%) thanks to solid commercial activity and market performance, while Insurance’s gross written premiums increased 20% to €10 billion.
Payments, which brings together the group’s digital payment capabilities and provides global technology solutions to Santander businesses and third-party clients, generated an underlying profit of €105 million, more than double the previous year, driven by strong revenue growth (+15%) as it continued to scale its global platforms and expand its integrated payments ecosystem. Getnet’s total payment volume increased 9%, while Getnet Platforms processed 14 billion account-to-account and card transactions, three times more than in the same period of last year. Ebury, Santander's cross-border payments and foreign exchange platform for small and medium-sized businesses, increased its active customers by 25% to 29,500. The EBITDA margin improved by 2.4 percentage points to 34.0%, reflecting the benefits of greater scale and operating leverage.
Banco Santander is one of the world's largest banks, with 186,000 employees, serving 189 million customers, 3.6 million shareholders and a market capitalization of €179 billion at the end of September 2026.
[1] All references to M&A across the press release refer to TSB and Webster.
[2] All figures are year-on-year unless otherwise stated. Volumes (lending, deposits, etcetera) in constant euros. Reconciliation of underlying results to statutory results, available in the ‘Alternative Performance Measures’ section of the financial report at CNMV and at santander.com.
[3] Targets market dependent. Based on macro assumptions aligned with international economic institutions. Targets assuming cost of risk stable. 2026 targets are set excluding Poland, TSB and Webster. CET1 ratio target including all the impacts from inorganic transactions.
[4] Total share buybacks as of 9M’26 including: i) €1.7bn share buyback against H1’25 results (completed); ii) €1.8bn share buyback against H2’25 results (completed); iii) €3.2bn additional share buyback to distribute approx. 50% of the CET1 capital generated following the completion of the sale of 49% of Santander Bank Polska to Erste Group on 9 January 2026 (completed); and €1.8bn share buyback against H1’26 results (underway). The board of directors intends to: i) apply an ordinary shareholder remuneration policy for 2026 to 2028 results that entails allocating approximately 50% of the Group’s underlying profit (excluding non-cash, non-capital ratios impact items), split approximately evenly between cash dividends and share buybacks for 2026 results; and additionally ii) distribute excess capital at the end of the 2026-2028 period to shareholders. From 2027 results on, the ordinary shareholder remuneration policy is expected to comprise around 35% of Group underlying profit (on the same basis) in cash dividends and around 15% in share buybacks. Execution of the shareholder remuneration policy and of the distribution to shareholders of excess capital at the end of the 2026-2028 period is subject to future corporate and regulatory decisions and approvals.
Note: Figures are presented on a basis reflecting the changes made to the presentation of the Group’s financial information, effective from the first quarter of 2026 and communicated through Other Relevant Information filed with CNMV on 10 February. Group underlying profit excludes: i) charges for intangible asset impairments and integration costs associated with the M&A transactions in Q2’26 and Q3’26 (-€666mn); ii) the capital gain resulting from the disposal of the Poland business in Q1'26 (€1,895mn); and iii) results related to the business subject to the Poland disposal in 9M'25 (€713mn). In the Group's consolidated balance sheet, balances as at 30 September 2026 include TSB and Webster, affecting comparisons with prior periods.
Download full press release 1.5 MB
2025 Annual Review

Privacy Preference Center
Privacy Preference Center
-
Your Privacy
-
Technical cookies
-
Analytical Cookies
-
Behavioural advertising cookies
-
Personalisation or preference cookies
Your Privacy
When you visit any website, it may store or retrieve information on your browser, mostly in the form of cookies. This information might be about you, your preferences, or your device, and is mostly used to make the site work as you expect. The information does not usually identify you directly, but it can give you a more personalized web experience. Because we respect your right to privacy, you can choose not to allow some types of cookies. Click on the different category headings to learn more and change our default settings. Blocking some types of cookies may impact your experience of the site and the services we are able to offer. More information
Technical cookies
Always Active
These cookies are necessary to ensure the basic functioning of the Site with greater security and cannot be deactivated. For example, they allow identification of the session, access to restricted areas, use of security elements during browsing, etc.
Analytical Cookies
Analytical Cookies
These cookies, either our own or those of third parties, are used to obtain information on the performance of the Site and the use made of it by the user, such as, for example, quantifying the number of users who have visited the Site, measuring and analysing statistics on how users arrive at the Site and what use they make of it. We also use these cookies to develop analytical models based on your commercial profile prepared by the Company.
Behavioural advertising cookies
Behavioural advertising cookies
These cookies, whether first-party or third-party, store information about user behaviour gathered through continuous observation of browsing habits (such as repeated visits to a specific site, interactions, keywords, online content creation, etc.), allowing a specific profile to be developed in order to display advertising based on that profile or to optimise advertising campaigns.
Personalisation or preference cookies
Personalisation or preference cookies
These cookies make it possible to store information so that the user can access the service with specific characteristics or that can distinguish their experience from that of other users without having expressly requested it, such as, for example, the language, the number of results to be shown when the user makes a search, the appearance or content of the service in accordance with the type of browser.
Cookie List
Leg.Interest
checkbox label label
checkbox label label
checkbox label label
Clear
- checkbox label label
Apply Cancel
Allow all

 0 0
 0 0

 0 0
 0 0
 0 0
 0 0
 0
 0 0
 0 0
 0 0
 0 0
 0 0
 0 0
 0 0
 0 0
 0 0