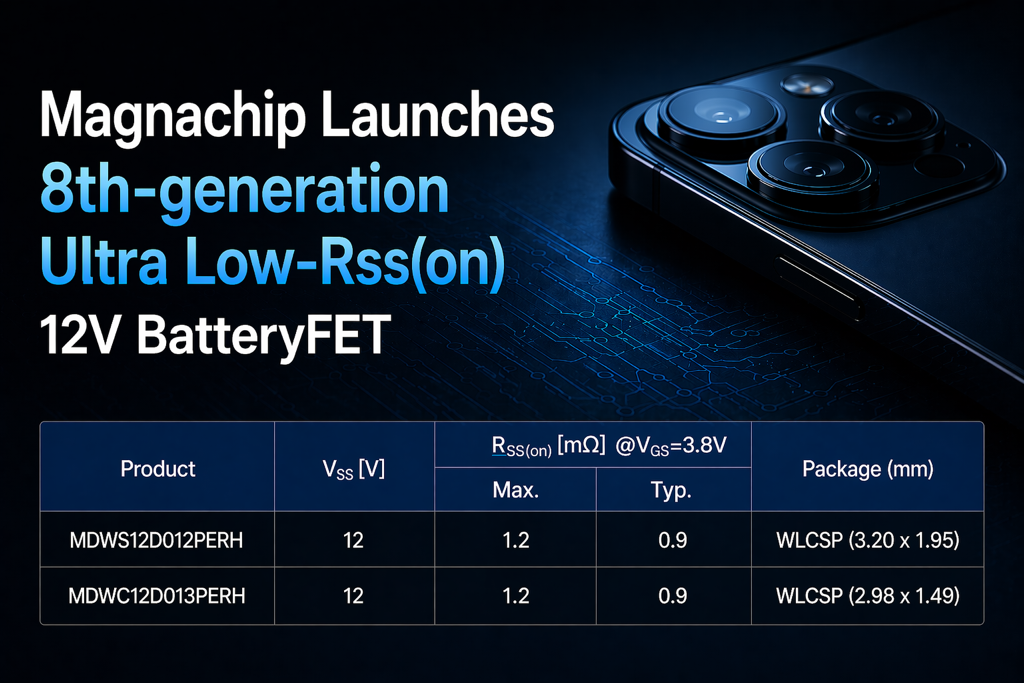
Magnachip Semiconductor Corporation is a designer and manufacturer of analog and mixed-signal power semiconductor platform solutions. The company operates two primary business segments: Power Analog Solutions, which produces metal oxide semiconductor field effect transistors (MOSFETs) and insulated-gate bipolar transistors (IGBTs), and Power IC, which develops AC-DC/DC-DC converters, LED drivers, regulators, power management integrated circuits (PMICs), and level shifters. These products serve industrial, automotive, communication, consumer, and computing applications, including televisions, smartphones, wearable devices, personal computers, servers, e-bikes, solar inverters, LED lighting, and motor drives. The company’s operations are centered in Korea, where it maintains design and manufacturing facilities. Magnachip Semiconductor was acquired from SK hynix in October 2004 and completed its initial public offering in March 2011. In 2020, the company sold its Foundry Services Group business to SK keyfoundry Inc. In 2025, the company transitioned to a pure-play power semiconductor model by liquidating its subsidiary Magnachip Mixed-Signal, Ltd., which operated the discontinued Display business. The company has announced a strategic investment partnership with Navitas Semiconductor.

Summarised from the company's own disclosures, fiscal year ended Mar 2026

Industry Semiconductors Homepage magnachip.com
Sector Technology IR page magnachip.com/magnachip-announces-strategic-investment-by-navitas-semiconductor
Tags
power semiconductors, analog semiconductors, mixed-signal semiconductors, mosfets, igbts, power management ics, automotive electronics, consumer electronics, industrial power, led drivers, Power Analog Solutions, Power IC, AC-DC/DC-DC converters, regulators, PMICs, level shifters, Magnachip Mixed-Signal Ltd., SK hynix, SK keyfoundry Inc., Navitas Semiconductor
Press page magnachip.com/about-us/newsroom

Metrics

Valuation  
Market cap $ 88.823M
Market cap (USD) $ 88.823M
P/E -2.62
PEG —
P/BV 0.36
P/S 0.51
P/OCF -5.65
P/FCF -2.65
Dividend yield —
Turnover / mcap —
Returns  
ROE -11.3%
ROI -10.1%
ROIC -9.2%
Profit margin -16.6%
Growth  
Revenue growing No
Profits growing Yes
Revenue up 3y No
Revenue up 5y No
Earnings growth 3y (net profit CAGR) —
Quality  
Profitable No
Margin expanding Yes
Buying back stock Yes
Diluting (TTM) Yes
Debt/Equity 19.2%
Podcast bulls (TTM) Sign up
Podcast bears (TTM) Sign up
Podcast sentiment (TTM) Sign up
Podcast sentiment % (TTM) Sign up
News sentiment (TTM) 2
Quality score -41.2%
Insiders  
Buys, 1w Sign up
Buys, 1m Sign up
Buys, 1y Sign up
Sells, 1w Sign up
Sells, 1m Sign up
Sells, 1y Sign up

Sign up to see this company's insider trades

Figure FY 2025 FY 2024 FY 2023 FY 2022 FY 2021 FY 2020 FY 2019 FY 2018 FY 2017 FY 2016 FY 2015 FY 2014 FY 2013 FY 2012 FY 2011 FY 2007 FY 2006
Revenue 178.86M 231.737M 230.051M 337.658M 474.23M 507.059M 792.195M 750.898M 679.672M 687.969M 633.712M 698.218M 734.177M 819.592M 772.831M 792.356M —
Net profit -29.724M -54.308M -36.622M -8.036M 56.708M 344.965M -21.826M -3.9M 84.936M -29.615M -84.867M -117.232M -64.203M 193.301M 21.793M -180.55M —
Free cash flow -54.2M -17.733M -9.969M -18.229M 55.531M -28.63M 27.542M 10.288M -51.105M -11.096M -16.327M -54.888M 26.272M 59.581M 56.358M -109.005M —

Figure FY 2025 FY 2024 FY 2023 FY 2022 FY 2021 FY 2020 FY 2019 FY 2018 FY 2017 FY 2016 FY 2015 FY 2014 FY 2013 FY 2012 FY 2011 FY 2007 FY 2006
Share price 2.55 4.02 7.5 9.39 20.97 13.52 11.61 6.21 9.95 6.2 5.29 12.99 19.5 15.74 6.72 — —
Price performance 12m -0.37 -0.46 -0.2 -0.55 0.55 0.16 0.87 -0.38 0.61 0.17 -0.59 -0.33 0.24 1.34 — — —

Filed figures

Figure Dec 2016 Dec 2017 Dec 2018 Dec 2019 Dec 2020 Dec 2021 Dec 2022 Dec 2023 Dec 2024 Dec 2025
Balance sheet detail
Trade receivables (USD) 61.8M 92M 80M 95.6M 64.4M 51M 35.4M 32.6M 28.4M 26M
↳ YoY growth -2.7% +49.0% -13.1% +19.5% -32.7% -20.9% -30.6% -7.7% -13.0% -8.4%
↳ 5y CAGR -13.3% -8.5% +0.3% +5.6% +0.3% -3.8% -17.4% -16.4% -21.6% -16.6%
Borrowings, current (USD) — — — — 83.5M — — — — 0.00
Borrowings, non-current (USD) 221M 303M 304M 305M 0.00 — — 0.00 27.2M 44.6M
Lease liabilities (USD) — — — 11.5M 4.63M 4.28M 5.49M 4.81M 3.22M 2.12M
Cash and deposits (USD) 83.4M 129M 132M 152M 280M 280M 225M 158M 139M 104M
Intangible assets (USD) 3.09M 4.06M 3.95M 4.01M 2.73M 2.38M 1.93M 1.54M 507,000 454,000
Right-of-use assets (USD) — — — 11.5M 4.63M 4.28M 5.27M 4.64M 3.11M 2.07M
Net debt (borrowings + leases - cash) (USD) 138M 175M 171M 165M -192M — — -153M -108M -57M
Cash flow detail
Operating cash flow (USD) 7.63M -18.4M 39.2M 50.5M 7.47M 87.7M 5.17M -3.01M -6.13M -24.2M
Purchases of property, plant and equipment (USD) -18.7M -32.7M -28.9M -23M -36.1M -32.2M -23.4M -6.96M -11.6M -30M
Purchases of intangible assets (USD) -1.05M -1.21M -961,000 -1.1M -741,000 -614,000 -390,000 -263,000 -316,000 -207,000
Change in receivables (cash effect) (USD) 285,000 -22.2M 8.29M -19.8M -19.3M 7.51M 10.3M 1.91M 2.72M -2.99M
Change in inventories (cash effect) (USD) -557,000 -8.08M -30.7M -4.21M -816,000 -5.94M -12.6M 2.37M -1.58M -5.8M
Change in payables (cash effect) (USD) -4.16M 10.3M -8.39M — — — — — — —
Share buybacks (cash effect) (USD) — -11.4M -1.61M -2.7M -1.13M -1.65M -14M -51.8M -12.9M -4.38M
Interest paid (cash effect) (USD) -14.9M -17.6M -19.3M -19.1M -22.2M -2.09M — 0.00 -966,000 -1.25M
Income taxes paid (cash effect) (USD) -693,000 -1.03M -920,000 -2.08M -23.1M -12.7M -19M -1.44M -1.34M -1.93M
Share-based compensation (USD) 3.84M 2.34M 5.21M 6.95M 6.7M 7.7M 6.04M 7.22M 6.21M 2.18M
Operating cash flow before change in receivables (USD) 7.35M 3.77M 30.9M 70.3M 26.7M 80.2M -5.11M -4.92M -8.85M -21.2M
Free cash flow (OCF - PPE - intangibles) (USD) -12.1M -52.3M 9.33M 26.4M -29.4M 54.9M -18.6M -10.2M -18M -54.4M
Income detail
Research and development expense (USD) 72.2M 70.5M 78M 75.4M 45.7M 51.2M 52.3M 51.6M 51.2M 27.3M
↳ 5y CAGR -1.2% -2.2% -2.3% -4.1% -11.3% -6.6% -5.8% -8.0% -7.4% -9.8%
Total comprehensive income (USD) -15.4M 37.8M 9.1M -4.38M 351M 50.8M -18.4M -38.7M -61.5M -26.6M
Comprehensive income to owners (USD) -15.4M 37.8M 9.1M -4.38M 351M 50.8M -18.4M -38.7M -61.5M -26.6M
Provision for credit losses (USD) — — — — -131,000 -302,000 — — -4,000 —
Credit cost ratio (credit losses / average receivables) (%) — — — — 0.2% 0.5% — — 0.0% —
Reported Feb 21, 2017 Feb 22, 2018 Feb 22, 2019 Feb 21, 2020 May 10, 2021 Feb 23, 2022 Feb 22, 2023 Mar 14, 2025 Mar 14, 2025 May 8, 2026

Sign up to see institutional holdings

Sign Up

Podcast Mentions

Sign up to see podcast mentions and sentiment

Sign Up

Magnachip Reports Results for Third Quarter 2026 Bull 2 Bear 4 Results

Q3 Results Summary

•Consolidated revenue from continuing operations (which includes Power Analog Solutions (“PAS”) and Power IC (“PIC”) businesses) was $44.0 million, within the guidance range of $41.5 million to $45.5 million.

•Consolidated gross profit margin from continuing operations of 14.0% was below the guidance range of 17.0% to 19.0%, primarily due to unfavorable foreign exchange movements.

Recent Highlights

•Announced a $5 million strategic equity investment by Navitas Semiconductor, further strengthening the companies' partnership to develop differentiated next-generation power semiconductor solutions.

•Launched 15 new sixth-generation E6 Super-Junction MOSFETs targeting TVs, notebook adapters, PC power supplies and other consumer and industrial power applications.

•Continued execution of its new-generation power semiconductor roadmap, expanding its portfolio of products to strengthen competitiveness, increase profitability, and address new market opportunities.

SEOUL, South Korea, Nov. 4, 2026 – Magnachip Semiconductor Corporation (NYSE: MX) (“Magnachip” or the “Company”) today announced financial results for the third quarter 2026.

2026. 10. 05.2026. 10. 05.

[](mailto: ?body=https://www.magnachip.com/magnachip-launches-15-new-gen6-e6-super-junction-mosfets-for-tvs-notebook-adapters-and-pc-power-supplies/)

– Well-Balanced thermal, switching and EMI performance for compact power designs
– 500 V and 600 V options for greater flexibility in PCB layout and thermal design

SEOUL, South Korea — Magnachip Semiconductor Corporation (“Magnachip”) today expanded its power semiconductor portfolio with 15 new sixth-generation (Gen6) E6 super-junction (SJ) MOSFETs for consumer and computing power applications.

As consumer and computing systems deliver higher performance in increasingly compact form factors, power designers need to manage efficiency, thermal performance, switching noise and PCB space simultaneously. Voltage ratings, on-resistance values and package requirements also vary according to system power levels and PCB design constraints, making MOSFET selection increasingly important.

The new E6 Series addresses these challenges with a balanced combination of thermal, switching and EMI performance. The MOSFETs are designed to help manage switching losses and oscillation while supporting design margin for voltage transients and avalanche conditions. These characteristics can help designers reduce thermal stress and switching noise in compact power designs while maintaining margin for normal operating and transient conditions.

Magnachip tested its 600 V, 280 mΩ E6 MOSFET in a TO-220SFA package in the power factor correction (PFC) stage of a TV switch-mode power supply (SMPS). At a 100 Vac input and under the same test conditions, the E6 MOSFET operated at approximately 5.3% lower temperature than Magnachip’s previous-generation MOSFET. This result indicates the potential of the E6 Series to offer additional thermal design margin in comparable PFC circuits.

The E6 Series includes 500 V and 600 V MOSFETs. The 600 V lineup offers DPAK (TO-252), TO-220FA and TO-220SFA packages across key on-resistance classes, allowing designers to choose from a range of MOSFET options to better align with their thermal and PCB mounting requirements while achieving the required Rds (on) rating.

“As power systems become more compact, designers need MOSFETs that help them manage heat and switching noise while meeting efficiency targets,” said Hyuk Woo, Chief Technology Officer of Magnachip Semiconductor. “We developed the E6 Series around these requirements for TV and computing power applications, offering customers performance and package options suited to their operating conditions.”

The E6 portfolio targets TV SMPS, notebook adapters, PC power supplies, and consumer and industrial power applications below 1 kW. The MOSFETs are now in mass production.

Resources:

Product brief: https://www.magnachip.com/wp-content/uploads/2026/09/E6_SJ_MOSFET_ProductBrief-3.pdf

Related Links:

Power Solutions > SJ MOSFETs > 500V

Power Solutions > SJ MOSFETs > 600V

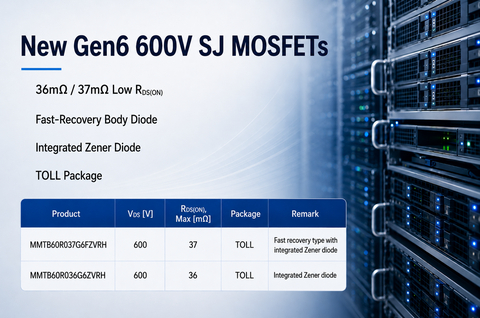
 Related Articles: Magnachip Launches New 6th-Generation 600V SJ MOSFETs for AI Servers and EV Charging Applications

About Magnachip Semiconductor

Magnachip is a designer and manufacturer of analog and mixed-signal power semiconductor platform solutions for various applications, including industrial, automotive, communication, consumer and computing. The Company provides a broad range of standard products to customers worldwide. Magnachip, with about 45 years of operating history, owns a substantial number of registered patents and pending applications, and has extensive engineering, design and manufacturing process expertise. For more information, please visit www.magnachip.com . Information on or accessible through Magnachip’s website is not a part of, and is not incorporated into, this release.
2026. 09. 21.2026. 09. 21.

[](mailto: ?body=https://www.magnachip.com/magnachip-announces-strategic-investment-by-navitas-semiconductor/)

– Investment deepens strategic partnership and supports development of differentiated nextgeneration power semiconductor solutions

 SEOUL, South Korea–(BUSINESS WIRE)—Magnachip Semiconductor Corporation (NYSE: MX) (“Magnachip” or the “Company”), a designer and manufacturer of analog and mixed-signal power semiconductor platform solutions, today announced that Navitas Semiconductor Corporation (Nasdaq: NVTS) (“Navitas”) has agreed to make a $5 million strategic equity investment in Magnachip.

Under the terms of a privately negotiated stock purchase agreement, Magnachip will issue and sell 1,461,988 shares of its common stock to Navitas at a purchase price of $3.42 per share, for aggregate proceeds of $5 million. The transaction is expected to close on or about September 24, 2026, subject to the satisfaction or waiver of customary closing conditions. The investment builds on the growing strategic partnership between Magnachip and Navitas following the announcement in July 2026 to accelerate the adoption of silicon carbide technologies in high-voltage and ultra-highvoltage power markets. Under that partnership, Magnachip is licensing Navitas’ GeneSiC™ Trench-Assisted Planar™ technology covering 1,200 V, 2,300 V, 3,300 V and higher-voltage applications. Magnachip is also gaining access to Navitas’ SiC supply chain and materials ecosystem, with plans to port, qualify and internalize the technology at Magnachip’s fabrication facility in South Korea. The partnership also creates opportunities for broader technology and product collaboration beyond the initial GeneSiC licensing agreement. The companies are initially targeting applications including energy and grid infrastructure, energy storage, industrial electrification, automotive and other high-power systems.

“Navitas’ investment represents an important next step in our strategic partnership and demonstrates a shared commitment to the opportunities we are pursuing together,” said Chae Lee, Chief Executive Officer of Magnachip. “By combining Navitas’ proven GeneSiC technology and materials ecosystem with Magnachip’s power semiconductor expertise, manufacturing capabilities and customer relationships, we believe we can accelerate our entry into attractive high-voltage and ultra-high-voltage markets. More importantly, we believe the combination of Navitas’ SiC technology with Magnachip’s silicon power technologies and manufacturing capabilities creates opportunities to develop a new generation of differentiated power solutions that address emerging customer needs that we believe are not adequately served by products available today. We look forward to deepening our collaboration as we execute our long-term growth strategy.”

“Magnachip is an important strategic partner for Navitas, and this investment reflects our confidence in the relationship and the value we believe the two companies can create together in the years ahead,” said Chris Allexandre, President and Chief Executive Officer of Navitas. “Our initial technology and licensing collaboration established a strong foundation. This investment further aligns our interests and reflects our shared belief that the combination of our complementary technologies can create new opportunities across high-voltage and ultra-high voltage applications. We look forward to working closely with Magnachip to expand the adoption of advanced GeneSiC technologies and explore opportunities for broader technology and product collaboration.” Additional information concerning the transaction will be included in a Current Report on Form 8-K to be filed by Magnachip with the U.S. Securities and Exchange Commission.

Safe Harbor for Forward-Looking Statements

Information in this press release regarding Magnachip’s forecasts, business outlook, expectations and beliefs are forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 that involve risks and uncertainties. These statements include expectations regarding our financial performance and business outlook, including the expected closing of the investment, the anticipated benefits of Magnachip’s relationship with Navitas, the development, qualification and commercialization of silicon carbide technologies, Magnachip’s entry into high-voltage and ultra-high-voltage markets, and the companies’ ability to create value through the collaboration, and other future events. All forwardlooking statements included in this release are based upon information available to Magnachip as of the date of this release. These statements are not guarantees of future performance and actual results could differ materially from our current expectations. Factors that could cause or contribute to such differences include, among others: changes in macroeconomic conditions, trade policies, geopolitical conditions and market conditions; manufacturing capacity constraints, supply chain disruptions and changes in customer demand; the impact of competitive products and pricing; our ability to establish, maintain and expand strategic relationships with customers and business partners, and to realize the anticipated benefits of those relationships; customer acceptance of our products and technologies; our ability to develop, introduce and ramp new products into volume production; changes in semiconductor industry supply and demand, including overcapacity and manufacturing utilization; financial stability in foreign markets and the impact of foreign exchange rates; unanticipated costs and expenses; changes in, or compliance with, applicable trade, export and other laws and regulations; public health issues; other business interruptions; and other risks described in Magnachip’s filings with the SEC, including our Annual Report on Form 10-K filed on March 16, 2026, and subsequent registration statements, amendments or other reports that we may file from time to time with the SEC and/or make available on our website. Magnachip assumes no obligation and does not intend to update the forward-looking statements provided, whether as a result of new information, future events or otherwise.

About Magnachip Semiconductor

Magnachip is a designer and manufacturer of analog and mixed-signal power semiconductor platform solutions for various applications, including industrial, automotive, communication, consumer and computing. The Company provides a broad range of standard products to customers worldwide. Magnachip, with about 45 years of operating history, owns a substantial number of registered patents and pending applications, and has extensive engineering, design and manufacturing process expertise. For more information, please visit www.magnachip.com.

About Navitas Semiconductor

Navitas Semiconductor (Nasdaq: NVTS) is a nextgeneration power semiconductor leader in gallium nitride (GaN) and IC integrated devices, and high-voltage silicon carbide (SiC) technology, driving innovation across AI data centers, energy and grid infrastructure, performance computing and industrial electrification. With more than 30 years of combined expertise in wide-bandgap technologies, GaNFast™ power ICs integrate GaN power, drive, control, sensing, and protection, delivering faster power delivery, higher system density, and greater efficiency. GeneSiC™ high-voltage SiC devices leverage patented trench-assisted planar technology to provide industry-leading voltage capability, efficiency, and reliability for medium-voltage grid and infrastructure applications. Navitas has over 300 patents issued or pending and is the world’s first semiconductor company to be CarbonNeutral®-certified.

Prompts

Magnachip Semiconductor Corporation (ticker MX), listed in United States.

ETFs Holding Magnachip Semiconductor Corporation

ETF Weight in ETF Shares Market value As of
IALT short -0.14% -164,121 $ -10.98M Nov 16, 2026
DFAS 0.00% 250,810 $ 707.284K Nov 12, 2026
DXUV 0.00% 12,196 $ 34.393K Nov 12, 2026
DFAC 0.00% 11,292 $ 31.843K Nov 12, 2026
DCOR 0.00% 4,788 $ 13.502K Nov 12, 2026
AVUS 0.00% 5,631 $ 13.177K Nov 16, 2026
AVSC 0.00% 58,378 $ 136.605K Nov 16, 2026
BSVO 0.00% 6,141 $ 10K Nov 18, 2026