NerdWallet, Inc. is a digital financial services platform that provides consumers and small and mid-sized businesses with guidance, comparison tools, and access to regulated financial services. The company operates three primary business segments: editorial and content publishing, marketplace and referral services, and financial services. Its platform enables users to compare and connect with third-party providers for credit cards, consumer loans, small business financing, home lending, insurance, banking, and investment products. NerdWallet generates revenue through referral fees, lead generation, partner-based monetization, and brokering and advisory services. The company serves markets in the United States, Canada, and the United Kingdom. Key subsidiaries include Next Door Lending, LLC for mortgage brokerage, NerdWallet Advisory LLC for financial advisor matching, NerdWallet Wealth Partners, LLC for fiduciary investment advisory services, and NerdWallet Insurance Experts, LLC for insurance brokerage. The platform utilizes proprietary technology for data ingestion, partner integrations, user segmentation, and personalized insights to facilitate financial product discovery and application.

Summarised from the company's own disclosures, fiscal year ended Feb 2026

Industry Internet Content & Information Homepage nerdwallet.com
Sector Communication Services IR page investors.nerdwallet.com
Tags
financial comparison, credit cards, personal loans, small business financing, mortgage brokerage, insurance brokerage, investment advisory, lead generation, financial education, digital marketplace, NerdWallet, Fundera, NerdWallet Insurance Services, NerdWallet Advisory, NerdWallet Compare, Next Door Lending LLC, NerdWallet Advisory LLC, NerdWallet Wealth Partners LLC, NerdWallet Insurance Experts LLC
Press page nerdwallet.com/mortgages/news

Metrics

Valuation  
Market cap $ 555.704M
Market cap (USD) $ 555.704M
P/E 11.26
PEG —
P/BV 1.63
P/S 0.63
P/OCF 3.78
P/FCF 3.81
Dividend yield —
Turnover / mcap —
Returns  
ROE 13.2%
ROI 12.8%
ROIC 12.2%
Profit margin 5.8%
Growth  
Revenue growing Yes
Profits growing Yes
Revenue up 3y Yes
Revenue up 5y —
Earnings growth 3y (net profit CAGR) —
Quality  
Profitable Yes
Margin expanding Yes
Buying back stock Yes
Diluting (TTM) No
Debt/Equity —
Podcast bulls (TTM) Sign up
Podcast bears (TTM) Sign up
Podcast sentiment (TTM) Sign up
Podcast sentiment % (TTM) Sign up
News sentiment (TTM) 4
Quality score 75.0%
Insiders  
Buys, 1w Sign up
Buys, 1m Sign up
Buys, 1y Sign up
Sells, 1w Sign up
Sells, 1m Sign up
Sells, 1y Sign up

Sign up to see this company's insider trades

Figure FY 2025 FY 2024 FY 2023 FY 2022 FY 2021 FY 2020
Revenue 836.6M 687.6M 599.4M 538.9M 379.6M 0
Net profit 48.7M 30.4M -11.8M -10.2M -42.5M 0
Free cash flow 130.3M 71.2M 71.4M 20.4M 4.9M —

Figure FY 2025 FY 2024 FY 2023 FY 2022 FY 2021 FY 2020
Share price 13.55 13.3 14.72 9.6 15.55 —
Price performance 12m 0.02 -0.1 0.53 -0.38 — —

Filed figures

Figure Dec 2018 Dec 2019 Dec 2020 Dec 2021 Dec 2022 Dec 2023 Dec 2024 Dec 2025
Balance sheet detail
Trade receivables (USD) — — 37.3M 57.6M 87M 75.5M 102M 111M
↳ YoY growth +54.4% +51.0% -13.2% +35.4% +8.6%
↳ 5y CAGR +24.4%
Borrowings, non-current (USD) — — 30.2M 0.00 — — — —
Lease liabilities (USD) — — 14.8M 15.1M 12.7M 9.6M 6.4M 8M
Cash and deposits (USD) 52.4M 67.6M 83.4M 168M 83.9M 100M 66.3M 98.3M
Intangible assets (USD) — — 35.6M 27.6M 64.1M 46.9M 33.3M 21.5M
Right-of-use assets (USD) — — 14M 13.9M 11.3M 7.2M 5.3M 7.1M
Net debt (borrowings + leases - cash) (USD) — — -38.4M -153M — — — —
Cash flow detail
Operating cash flow (USD) — 31.4M 15.4M 7.2M 25M 72.1M 71.8M 132M
Purchases of property, plant and equipment (USD) — -700,000 -1.3M -2.3M -4.6M -700,000 -600,000 -1.3M
Change in receivables (cash effect) (USD) — -12.9M 1M -20.2M -18.7M 10.7M -27M -9.4M
Change in payables (cash effect) (USD) — -300,000 3.6M -2.2M -5.6M -1.8M 6.6M -3.6M
Share buybacks (cash effect) (USD) — — — — — -20M -80.1M -70.2M
Interest paid (cash effect) (USD) — -1.5M -1.4M -2.5M -1.9M -300,000 -300,000 -300,000
Income taxes paid (cash effect) (USD) — -1.5M -1.2M -300,000 -4M -13.5M -16M -15.1M
Share-based compensation (USD) — 5M 6.4M 17.9M 34.4M 38.8M 37.7M 28.6M
Operating cash flow before change in receivables (USD) — 44.3M 14.4M 27.4M 43.7M 61.4M 98.8M 141M
Free cash flow (OCF - PPE - intangibles) (USD) — 30.7M 14.1M 4.9M 20.4M 71.4M 71.2M 130M
Income detail
Research and development expense (USD) — 46M 50.9M 62.2M 77.6M 80.5M 82.5M 66.7M
↳ 5y CAGR +12.4% +5.6%
Total comprehensive income (USD) — 24.2M 5.9M -42.6M -11.6M -11.2M 30.5M 49M
Comprehensive income to owners (USD) — 24.2M 5.9M -42.6M -11.6M -11.2M 30.5M 49M
Reported Mar 24, 2022 Mar 24, 2022 Mar 24, 2022 Mar 24, 2022 Feb 23, 2023 Feb 25, 2026 Feb 25, 2026 Feb 25, 2026

Sign up to see institutional holdings

Sign Up

Podcast Mentions

Sign up to see podcast mentions and sentiment

Sign Up

Advertiser disclosure

You're our first priority. Every time.

We believe everyone should be able to make financial decisions with confidence. While we don't cover every company or financial product on the market, we work hard to share a wide range of offers and objective editorial perspectives.

So how do we make money? Our partners compensate us for advertisements that appear on our site. This compensation helps us provide tools and services - like free credit score access and monitoring. With the exception of mortgage, home equity and other home-lending products or services, partner compensation is one of several factors that may affect which products we highlight and where they appear on our site. Other factors include your credit profile, product availability and proprietary website methodologies.

However, these factors do not influence our editors' opinions or ratings, which are based on independent research and analysis. Our partners cannot pay us to guarantee favorable reviews. Here is a list of our partners.

U.S. Added an Unexpected 165,000 Jobs in October

The unemployment rate ticked down to 4.1% in October.

Anna HelhoskiWritten by

Anna Helhoski

Anna Helhoski

Senior Writer & Content Strategist

17 years of experience

Expertise

  • Economic news and policy

  • Consumer trends

Anna Helhoski is a senior writer covering economic news and trends in consumer finance at NerdWallet. She is an on-air contributor and producer of Money News segments for NerdWallet's Smart Money podcast. She is also an authority on student loans. She joined NerdWallet in 2014. Her work has been syndicated in news outlets nationwide including The Associated Press, The New York Times, The Washington Post, The Los Angeles Times and USA Today. She previously covered local news in the New York metro area for the Daily Voice and New York state politics for The Legislative Gazette. She holds a bachelor's degree in journalism from Purchase College, State University of New York.

Published inABC NewsBloombergCBS NewsCNBC
Rick VanderKnyffEdited by

Rick VanderKnyff

Rick VanderKnyff

Senior Editor & Content Strategist

43 years of experience

Expertise

  • Financial journalism

  • Editing

  • Audience engagement

Rick VanderKnyff leads the news and MoneyNerd teams at NerdWallet. Previously, he has worked as a channel manager at MSN.com, as a web manager at University of California San Diego, and as a copy editor and staff writer at the Los Angeles Times. He holds a Bachelor of Arts in communications and a Master of Arts in anthropology.

Updated Nov 6, 2026

Fact Checked

How is this page expert verified?

NerdWallet's content is fact-checked for accuracy, timeliness and relevance. It undergoes a thorough review process involving writers and editors to ensure the information is as clear and complete as possible.

More on our editorial rigor

[

Addas a preferred source on Google](https://google.com/preferences/source?q=nerdwallet.com)

U.S. Added an Unexpected 165,000 Jobs in October

NerdWallet is committed to editorial integrity.

Helpful Resources

Are We in a Recession?

U. Michigan: Consumer Sentiment Rising in November

How Is the Economy Doing Right Now?

Fed Keeps Rate Steady in October 2026

Updated on Nov. 6.

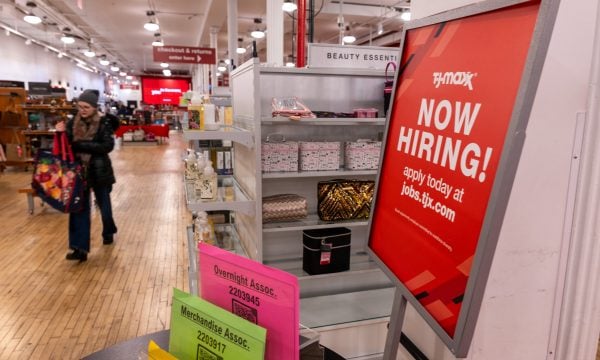
October hiring beats expectations

Unemployment was 4.1% in October, down 0.1 percentage point from September, according to the monthly jobs report released by the Bureau of Labor Statistics on Nov. 6.

Total employment grew by 165,000 — well above economists’ forecast of 65,000. In addition, August’s hiring numbers were revised up by 53,000 to 186,000, while September was revised up by 31,000 to 60,000. Together there were 84,000 more jobs added in August and September than originally reported.

Job gains:

  • Manufacturing (+19,000)

  • Professional and business services (+70,000)

  • Health care (+42,000)

  • Transportation and warehousing (+25,000)

More details below.

What are the weekly jobless claims?

Initial jobless claims went down for the week ending Oct. 31, according to the report released on Nov. 5.

Why it matters: The weekly jobless claims, or initial claims, are the number of unemployment insurance claims filed in the past week. They provide an indicator of the strength — or weakness — of the labor market.

Learn moreLearn more

Jobless claims were 189,000 for the week ending Oct. 31, down by 6,000 from the previous week’s revised level of 195,000.

» MORE: Laid off? Take these steps to get help

The new four-week moving average — a measurement of the number of people who filed for unemployment insurance for the first time over the last four weeks — was 194,750, down by 2,250 from the previous week's revised average of 197,000.

What's the insured unemployment rate?

Not all types of unemployment are included as part of the insured unemployment rate. It only includes "covered unemployment," as in people who receive unemployment benefits. Those who quit their jobs, for example, aren't included in the insured unemployment rate because they aren't eligible for unemployment benefits.

The advance seasonally adjusted insured unemployment rate — the rate of continuous covered unemployment claims divided by covered employment — was 1.1% for the week ending Oct. 24, unchanged from the previous week’s unrevised rate.

Job openings barely budged in September

There were 7.5 million job openings in September, little changed from August, which was revised to 7.2 million, according to the latest Job Openings and Labor Turnover Summary (JOLTS), released by the U.S. Bureau of Labor Statistics (BLS) on Nov. 3. The job openings rate was 4.5% in September.

The latest figures continue to show relatively little movement in the labor market.

Here are some other highlights from the report:

  • Hires increased in accommodation and food services (+158,000).

  • Hires changed little at 5.4 million, with the hiring rate at 3.4%.

  • Total separations changed little at 5.3 million, with the rate holding at 3.3%.

  • Quits increased to 3.4 million, while the quit rate was little changed at 2.1%.

  • Layoffs and discharges changed little at 1.6 million, with the rate remaining at 1%.

  • Job openings increased in state and local government, excluding education (+104,000).

The unemployment rate held steady at 4.1% in August, unchanged from July, according to the August jobs report released Sept. 4 by the Bureau of Labor Statistics (BLS).

Meet MoneyNerd, your shortcut to smart money moves

So much news ... so little time. NerdWallet's editors surface the financial moves worth thinking about this week, so you can act on them, or get on with your life. Delivered free, twice a week.

SUBSCRIBE FOR FREE

CTA image

What is the current unemployment rate?

The current unemployment rate is 4.1% for October, down by 0.1 percentage point from September.

The unemployment rate has risen since hitting a 50-year low of 3.4% in April 2023. Since May 2024, the unemployment rate has mostly stayed between 4% and 4.2%.

How the unemployment rate is calculatedHow the unemployment rate is calculated

The unemployment rate is calculated by dividing the number of unemployed people by the number of people in the labor force. (The labor force is considered the sum of those who are currently working or looking for work.) The result is then multiplied by 100 to get a percentage:

Number of unemployed people / Labor force x 100 = X%, which is the unemployment rate

Will unemployment go up soon?Will unemployment go up soon?

The labor market showed signs of weakening throughout 2025 and that trend has continued into 2026.

The recent rise in unemployment was a byproduct of monetary policymakers’ effort to curb inflation by hiking interest rates. The Federal Reserve raised the federal funds rate 11 times between March 2022 and July 2023. Now that inflation is consistently slowing, the Fed has taken steps to prevent unemployment from rising further.

The Fed cut rates in 2024 at its September, November and December meetings. It paused rates at every meeting so far in 2025, but has indicated that there could be some rate cuts in 2025.

The Fed cut rates three times in 2025 before pausing in January. It also paused rates in March and April.

» MORE: What is the minimum wage?

Are wages increasing?

Wage growth is lower than it was a year ago and now closer to pre-pandemic levels, according to data from the Federal Reserve Bank of Atlanta. The three-month moving average of median hourly wage growth — when measured over the previous 12 months — has slowed from its peak in the summer of 2022.

For June, the three-month wage growth percent change was 3.8%, unchanged from May.

What does the Employment Cost Index show?What does the Employment Cost Index show?

Increases in compensation costs in the second quarter of 2026 matched the last quarter of 2025 but were slower than a year ago, according to the most recent quarterly BLS Employment Cost Index, which measures wage and salary growth. Wages and salaries, as well as benefits, comprise total compensation costs.

The June 2026 report, released on July 31, shows compensation costs increased by 0.9% in the second quarter of 2026.

Year-over-year measurements show that compensation cost increases held steady in Q2 2026 (3.4%), matching the pace of the first quarter of 2026, but slower than the rates seen throughout 2024.

  • Q2 2026: 3.4%

  • Q1 2026: 3.4%

  • Q4 2025: 3.4%

  • Q3 2025: 3.6%

  • Q2 2025: 3.6%

  • Q1 2025: 3.6%

  • Q4 2024: 3.8%

  • Q3 2024: 3.9%

  • Q2 2024: 4.0%

  • Q1 2024: 4.2%

For the 12-month period ending in June 2026, wages and salaries increased 3.1%, compared to 3.5% for the 12-month period ending in March 2026.

Benefit costs had matched the increase in the 12-month period ending in June (3.8%) compared to the 12-month period ending in March 2026.

» MORE: What is the median household income?

More key jobs data and what it means

What happened in October?What happened in October?

The economy grew by 165,000 jobs in October, according to the BLS, while economists had expected fewer gains. Revisions also show job growth was stronger than previously reported in both August and September. Here’s how many jobs were added in previous months.

  • 60,000 in September 2026

  • 186,000 in August 2026

  • -10,000 in July 2026

  • 31,000 in June 2026.

  • 63,000 in May 2026.

  • 148,000 in April 2026.

  • 214,000 in March 2026.

  • -156,000 in February 2026.

  • 160,000 in January 2026.

  • 48,000 in December 2025.

  • 41,000 in November 2025.

  • -173,000 in October 2025.

What is the labor force participation rate?What is the labor force participation rate?

The labor force participation rate went up by 0.1 percentage points from 61.8% in September to 61.9% in October, according to the Bureau of Labor Statistics.

Why it matters: The labor force participation rate is the percentage of the population that is working or looking for work.

The rate is calculated as the labor force divided by the total population that’s eligible to work. (The Bureau of Labor Statistics defines the total population that’s eligible to work as the “civilian noninstitutional population,” which refers to people ages 16 and older who are not in military service or incarcerated.) The result is multiplied by 100 to get a percentage:

Labor force / Civilian noninstitutional population x 100 = X%, which is the labor force participation rate

Since October 2002, the labor force participation rate was lowest in April 2020 (60.1%) and highest in June 2003 (66.5%), according to BLS data.

How many job openings were there in September?How many job openings were there in September?

The latest Job Openings and Labor Turnover Summary (JOLTS), released on Nov. 3, shows job openings were 7.5 million in September compared to:

  • 7.2 million in August.

  • 7.3 million in July.

  • 7.2 million in June.

  • 7.6 million in May

  • 7.6 million in April

  • 6.9 million in March

  • 6.9 million in February

  • 7.2 million in January 2026

  • 6.6 million in December 2025

  • 6.9 million in November 2025

  • 7.4 million in October 2025

  • 7.7 million in September 2025

The seasonally adjusted job openings rate was 4.5% in September up 0.2 percentage point from August.

What is the layoff rate? What is the layoff rate?

The rate of layoffs in September (1%) was unchanged from August and July, according to the most recent JOLTS report.

What is the quit rate?What is the quit rate?

The JOLTS report shows the quit rate in September was 2.1%, little changed from August. The number of workers who voluntarily left their jobs increased to 3.4 million. Quits increased in accommodation and food services (+197,000) but decreased in arts, entertainment, and recreation (-19,000). Over the year, quits rose by 375,000.

Why it matters: Economists say quit rates are a key factor in the health of employment prospects since quitting shows that workers feel safe making a job switch within their sector or outside it entirely.

The current quit rate is slightly below pre-pandemic levels after peaking at 3% in both Nov. 2021 and April 2022.

When is the next jobs report?When is the next jobs report?

The next jobs report will show data for November and it will be released on Dec. 4

(Photo by Spencer Platt/Getty Images News via Getty Images)

Explore more on

The Financial Glow UpMaking MoneyPaying Your Bills

[

Addas a preferred source on Google](https://google.com/preferences/source?q=nerdwallet.com)

Back to top

About the author

Anna Helhoski

Anna Helhoski

Anna Helhoski is a senior writer covering economic news and trends in consumer finance at NerdWallet. She is an on-air contributor and producer of Money News segments for NerdWallet's Smart Money podcast. She is also an authority on student loans. She joined NerdWallet in 2014. Her work has been syndicated in news outlets nationwide including The Associated Press, The New York Times, The Washington Post, The Los Angeles Times and USA Today. She previously covered local news in the New York metro area for the Daily Voice and New York state politics for The Legislative Gazette. She holds a bachelor's degree in journalism from Purchase College, State University of New York.

Published in
ABC News

Bloomberg

CBS News

CNBC

Related articles

[

How Is the Economy Doing Right Now?

Anna Helhoski's profile picture

Anna Helhoski](https://www.nerdwallet.com/finance/learn/state-of-the-economy)

[

U.S.-Canada Trade Negotiations Fall Apart

Rick VanderKnyff's profile picture

Rick VanderKnyff](https://www.nerdwallet.com/finance/learn/tariff-news)

[

How Could the DHS Shutdown Affect You?

Anna Helhoski's profile picture

Anna Helhoski](https://www.nerdwallet.com/finance/learn/how-does-a-government-shutdown-affect-you)

NERDWALLET REPORTS THIRD QUARTER RESULTS Bull 0 Bear 3 Results

Revenue of $239.6 million, up 11% Year-Over-Year

FINANCIAL HIGHLIGHTS

•Revenue of $239.6 million

•GAAP income from operations of $19.4 million

•GAAP net income of $14.9 million, or $0.23 income per diluted share

•Non-GAAP operating income of $30.4 million

•Adjusted EBITDA of $39.8 million

SAN FRANCISCO, CA—November 5, 2026—NerdWallet, Inc. (Nasdaq: NRDS), which provides trustworthy financial guidance, products and services to consumers and small and mid-sized businesses (SMBs), today reported financial results for its third quarter ended September 30, 2026.

“Providing clarity for all of life’s financial decisions is how we earn the trust of the consumers and small businesses we serve,” said Tim Chen, Co-Founder and CEO of NerdWallet. “We’re building on that foundation by doing more for them and giving them more reasons to return to NerdWallet, and we're encouraged by the progress we're making.”

THIRD QUARTER 2026 HIGHLIGHTS

As previously announced, effective with the first quarter of 2026, we present revenue disaggregated by our user groups: Consumer and SMB.

I Don’t Buy With a Little Help From My Friends Bull 0 Bear 0 Other

To save money on holiday gifts this year, Americans are using these 5 strategies that require coordination with friends and family.

Kurt WoockWritten by

Kurt Woock

Kurt Woock

Lead Writer & Content Strategist

8 years of experience

Expertise

  • Personal finance

Kurt Woock started writing for NerdWallet in 2021. Prior to joining NerdWallet, Kurt was a writer and educator for Colorado PERA, a retirement system for public employees. Before that he was a legislative editor for the Colorado General Assembly. Kurt has a B.A. from Valparaiso University and an M.A. in journalism from the University of Missouri-Columbia. He lives in Chicago.

Published inMarketWatchMSNNasdaq.com

Erin El IssaEdited by

Erin El Issa

Erin El Issa

Senior Writer & Content Strategist

11 years of experience

Expertise

  • Data analysis

  • personal finance

Erin El Issa writes data-driven studies across personal finance topics. She loves numbers and aims to demystify data sets to help consumers improve their financial lives. Before becoming a Nerd in 2014, she worked as a tax accountant and freelance personal finance writer. Erin's work has been cited by The New York Times, CNBC, The Guardian, the "Today" show, Forbes and elsewhere. In her spare time, Erin reads and crochets voraciously and tries in vain to keep up with her two kids. She is based in Ann Arbor, Michigan.

Published inCBS NewsMarketWatchMSNNasdaq.com

Published Oct 30, 2026

Fact Checked

How is this page expert verified?

NerdWallet's content is fact-checked for accuracy, timeliness and relevance. It undergoes a thorough review process involving writers and editors to ensure the information is as clear and complete as possible.

More on our editorial rigor

[

Addas a preferred source on Google](https://google.com/preferences/source?q=nerdwallet.com)

Person, Adult, Female

NerdWallet is committed to editorial integrity.

Helpful Resources

How to Pay Off Debt: Top Strategies for 2026

Credit Score Ranges: What They Mean and How They Work

How to budget money in 5 steps

28 Proven Ways to Save Money

Gift giving can bust a budget, so some Americans plan to have conversations with friends and family this year about setting limits around holiday gifting.

This isn’t as Scroogey as you might think: 55% of holiday spenders plan to use at least one money-saving strategy that likely involves coordinating with loved ones, according to a new NerdWallet survey conducted online by The Harris Poll.

Money can be a taboo subject, especially among family and friends. But a focused discussion on gift boundaries could be the difference between staying within your budget and piling up debt this holiday season.

Ways holiday spenders plan to save, and how you can, too

Situation 1

Loved ones have different budgets.

What other Americans are doing: 28% of holiday spenders plan to set a per-gift dollar limit with family or friends.

Why this works: It’s simple and easy to remember. Unlike some other ideas on this list, you can probably coordinate this one over text.

For best results: If you’re the one bringing up the topic, you should come with a dollar amount that would be reasonable for everyone in your gift exchange group, so no one feels excluded or overextended.

Situation 2

Your circle of friends and family has a lot of kids.

What other Americans are doing: 23% of holiday spenders plan to buy gifts for children in a family, but not the adults.

Why this works: Cutting out adult gifts altogether can rescue a gift budget that has undergone major “kidflation” as new children join the family.

For best results: If you still want to include adults, give a gift that’s fun for the whole family, like a board game or an experience. And make sure your kid-free loved ones are on board.

Situation 3

You traditionally exchange gifts one-on-one with a friend, but the last few gifts you’ve given — and received — were duds.

What other Americans are doing: 18% of holiday spenders plan to skip exchanging gifts with at least one friend or family member.

Why this works: If you’re feeling gift fatigue, there’s a chance they are, too.

For best results: Frame this as an improvement to the gift-giving tradition rather than a scaling back. Propose an alternative way to celebrate your friendship, like swapping out the $40 gift that’ll probably get shelved for a $7 coffee together.

Situation 4

You have a lot of loved ones.

What other Americans are doing: 16% of holiday spenders plan to do a secret Santa gift exchange, or another game that requires purchasing only one gift.

Why this works: 15% of holiday spenders list buying gifts for more people than they originally planned for as among the reasons they’re most likely to overspend this holiday season. This strategy keeps your list in check, even if the number of people playing grows.

For best results: There are bound to be people in your group for whom the rules to the game are important. If you’re the one organizing, be ready to answer questions — can you trade or steal gifts, for example, and, if so, how many times? Also, this works best for family or friend groups who aren’t likely to go rogue and buy extra gifts anyway.

Situation 5

You have no idea what your college friend’s kids (or spouse) are into.

What other Americans are doing: 12% of holiday spenders plan to give one shared gift per family instead of individual gifts.

Why this works: In addition to saving money, this avoids the awkwardness that comes with uninformed gift giving.

For best results: Presentation is key. Don’t sheepishly give an UNO game you clearly bought on the drive over. You may be cutting back, but enthusiasm is free.

Start the conversations soon

Talking about the holidays and talking about money can be stressful conversation topics. About four in five Americans avoid discussing some money topics with family and friends, according to a 2026 survey by the CFP Board. So discussing both at once may seem daunting. But without a doubt, you’re not the only one thinking about them.

Nearly 9 in 10 (86%) holiday spenders plan to use at least one money-saving strategy this holiday season. Start with an icebreaker: “Hey, have you noticed how expensive everything is lately? Would you be open to talking about how we can do gifts this year while keeping spending under control?” This conversation might be the thing that’s secretly on everyone’s wish list.

[

Addas a preferred source on Google](https://google.com/preferences/source?q=nerdwallet.com)

Back to top

About the author
Kurt Woock

Kurt Woock

Kurt Woock started writing for NerdWallet in 2021. Prior to joining NerdWallet, Kurt was a writer and educator for Colorado PERA, a retirement system for public employees. Before that he was a legislative editor for the Colorado General Assembly. Kurt has a B.A. from Valparaiso University and an M.A. in journalism from the University of Missouri-Columbia. He lives in Chicago.

Published in

MarketWatch

MSN

Nasdaq.com

Related articles

[

Get Your Free Credit Score

NerdWallet's profile picture

NerdWallet](https://www.nerdwallet.com/free-credit-score)
[

How to Pay Off Debt: Top Strategies for 2026

Lauren Schwahn's profile picture

2

Lauren Schwahn, Jackie Veling](https://www.nerdwallet.com/personal-loans/learn/pay-off-debt)

[GettyImages-1162855475-nerdwallet-budget-calculator

50/30/20 Budget Calculator

Amanda Barroso's profile picture

2

Amanda Barroso, Elizabeth Ayoola](https://www.nerdwallet.com/finance/learn/nerdwallet-budget-calculator)

Prompts

NerdWallet, Inc. (ticker NRDS), listed in United States.

ETFs Holding NerdWallet, Inc.

ETF Weight in ETF Shares Market value As of
DSMC 0.50% 70,165 $ 649.026K Jun 30, 2026
LITL 0.34% 2,753 $ 19.464K Nov 17, 2026
SQLV 0.22% 6,663 $ 61.633K Jun 30, 2026
FSEG 0.17% 1,032 $ 9,546.00 Jun 30, 2026
ESSC 0.15% 5,831 $ 52.479K Jul 31, 2026
PSC 0.12% 297,497 $ 2.752M Jun 30, 2026
VFQY 0.10% 51,427 $ 508.099K Aug 31, 2026
IVSS 0.10% 2,778 $ 25.697K Jun 30, 2026
FESM 0.09% 564,172 $ 5.219M Jun 30, 2026
SEIS 0.08% 51,140 $ 473.045K Jun 30, 2026
VFVA 0.06% 62,522 $ 617.717K Aug 31, 2026
BSVO 0.06% 189,663 $ 1.34M Nov 18, 2026
RESM 0.01% 58 $ 536.50 Jun 30, 2026
DFAT 0.01% 538,055 $ 3.933M Nov 12, 2026
AVUV 0.01% 428,509 $ 3.132M Nov 16, 2026
AVSC 0.01% 47,065 $ 344.045K Nov 16, 2026
DFAS 0.01% 288,811 $ 2.111M Nov 12, 2026
DFSU 0.00% 7,534 $ 55.074K Nov 12, 2026
DFAC 0.00% 143,370 $ 1.048M Nov 12, 2026
EBI 0.00% 676 $ 6,678.88 Aug 31, 2026
DXUV 0.00% 6,050 $ 44.226K Nov 12, 2026
DCOR 0.00% 42,967 $ 314.089K Nov 12, 2026
DFAU 0.00% 7,825 $ 57.201K Nov 12, 2026
DFUS 0.00% 9,818 $ 71.77K Nov 12, 2026
DFUV 0.00% 1,590 $ 11.623K Nov 12, 2026
AVUS 0.00% 10,002 $ 73.115K Nov 16, 2026
AVUQ 0.00% 626 $ 4,576.06 Nov 16, 2026