July 23, 2026 **MOUNT PLEASANT, MI / ACCESS Newswire / July 23, 2026 /** Isabella Bank Corporation (Nasdaq:ISBA) ("Isabella" or the "Company") reported net income of $5.0 million, or $0.69 per diluted share, for the second quarter 2026 compared to…
July 23, 2026
**MOUNT PLEASANT, MI / ACCESS Newswire
/ July 23, 2026 /** Isabella Bank Corporation (Nasdaq:ISBA) ("Isabella" or the "Company") reported net income of $5.0 million, or $0.69 per diluted share, for the second quarter 2026 compared to $5.0 million, or $0.68 per diluted share, for the second quarter 2025.
SECOND QUARTER 2026 HIGHLIGHTS
-
Loans grew $30.7 million during the quarter
-
Net interest margin (NIM) improved to 3.54%, up from 3.14% in second quarter 2025
-
Merger agreement signed with Grand River Commerce, Inc. and its banking subsidiary, Grand River Bank
-
Launched a successful at-the-market stock offering, increasing equity by $11.7 million
-
Added to the Russell 2000® Index
"Isabella Bank Corporation had another strong quarter, driven by continued loan growth and margin expansion," said CEO Jerome Schwind. "We also had a series of important events during the quarter aligned with our long-term strategy that will fuel our continued disciplined growth.
"We announced an agreement to acquire Grand River Commerce and Grand River Bank," Schwind added. "We believe this acquisition will enable us to enter the fast-growing Grand Rapids market with a strong portfolio and customer base. We look forward to welcoming the customers of Grand River Bank to the Isabella Bank family upon completion of the proposed transaction.
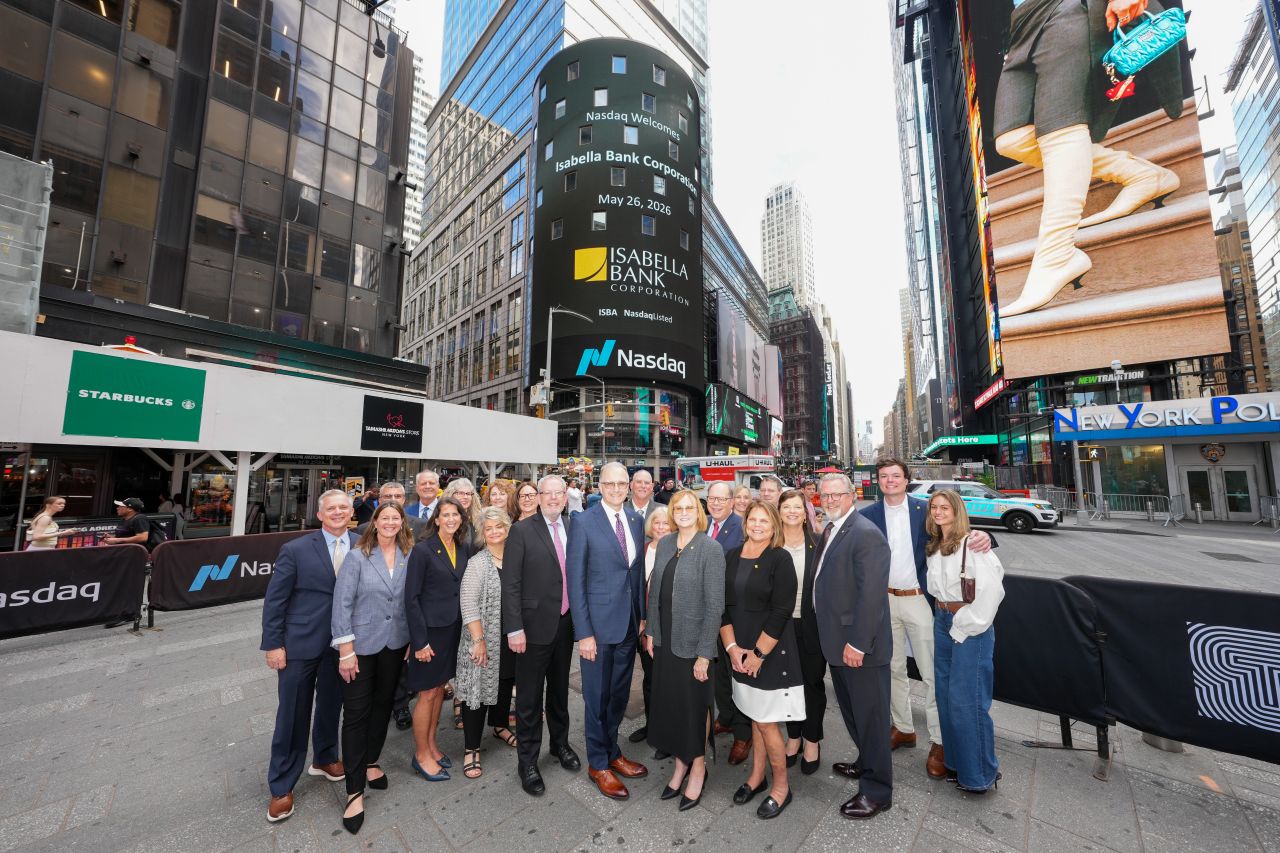
"We also launched a successful at-the-market offering of our common stock and were added to the Russell 2000® Index in June. In May, we celebrated one year of being listed on Nasdaq by ringing the closing bell," he added.
FINANCIAL CONDITION (June 30, 2026 to December 31, 2025 comparison)
Total assets increased $10.2 million, or 0.5%, to $2.2 billion as of June 30, 2026. This increase was primarily due to an increase of $53.3 million in loans and an increase of $15.7 million in cash and cash equivalents. These increases were offset by a $58.5 million decline in available-for-sale (AFS) securities.
The AFS securities portfolio decreased $58.5 million, or 11.8%, to $439.3 million as of June 30, 2026. The decrease was a result of maturities and principal paydowns of $121.8 million, offset by $64.4 million in purchases. Net unrealized losses on AFS securities were $10.8 million as of June 30, 2026, compared to $9.9 million at December 31, 2025. Net unrealized losses as a percentage of the amortized cost of AFS securities were consistent compared to December 31, 2025, at 2%.
Loans increased $53.3 million, or 3.5%, to $1.6 billion as of June 30, 2026, primarily by growth in the commercial real estate and residential real estate portfolios of $33.5 million and $22.1 million, respectively. Most residential originations were adjustable rate products, which are retained on the balance sheet rather than sold in the secondary market. The consumer loan portfolio continues to decrease amid declining demand, competition, and adherence to credit quality standards.
The allowance for credit losses (ACL) increased $752,000, or 5.5%, to $14.5 million as of June 30, 2026. The increase is due to loan growth and an increase in loss rates driven by loans charged off during the year. Nonaccrual loans were $7.8 million as of June 30, 2026 compared to $4.6 million at December 31, 2025. Past due and accruing accounts between 30 to 89 days as a percentage of total loans was 0.06% at June 30, 2026, compared to 0.44% at year-end 2025.
Total deposits decreased $9.7 million, or 0.5%, to $1.8 billion as of June 30, 2026. The decline was a result of a $20.7 million decline in certificates of deposit, a $14.0 million decline in interest bearing demand deposits, and a $12.3 million decline in noninterest bearing demand deposits. These declines were offset by a $20.4 million increase in savings deposits and a $16.8 million increase in money market accounts.
Total equity was $248.7 million, or $32.60 per share, at June 30, 2026 compared to $231.4 million, or $31.60 per share, as of December 31, 2025. The increase in total equity is primarily due to the issuance of 303,371 shares as part of the previously announced at-the-market stock offering, increasing total equity by $11.7 million. Tangible book value per share (non-GAAP) was $26.27 as of June 30, 2026, compared to $25.01 as of December 31, 2025. Net unrealized losses in the AFS securities portfolio reduced tangible book value per share (non-GAAP) by $1.14 and $1.09 for the respective periods.
RESULTS OF OPERATIONS (for the three and six months ended June 30, 2026, and 2025, unless otherwise noted)
Net income for the three months ended June 30, 2026 was $5.0 million, or $0.69 per diluted share, compared with $5.0 million, or $0.68 per diluted share, for the three months ended June 30, 2025. Net income for the six months ended June 30, 2026 was $10.0 million, or $1.37 per diluted share, compared with $9.0 million, or $1.21 per diluted share, for the six months ended June 30, 2025.
Net interest income was $18.1 million for the three months ended June 30, 2026 and $15.1 million for the three months ended June 30, 2025, representing 3.54% and 3.14% of earning assets, or NIM on a fully tax equivalent basis (non-GAAP), respectively. The book yield from securities was 2.82% and 2.38% for the three months ended June 30, 2026 and 2025, respectively. The yield on loans increased to 5.86% for the three months ended June 30, 2026 from 5.71% for the three months ended June 30, 2025. The increase in loan yields was primarily due to higher rates on new loans and variable rate commercial loans that continue to reprice. The cost of interest-bearing liabilities for the three months ended June 30, 2026 decreased to 2.09% from 2.24% for the three months ended June 30, 2025 primarily due to lower rates on money market and certificate of deposit products.
Net interest income was $35.0 million for the six months ended June 30, 2026 and $29.7 million for the six months ended June 30, 2025, representing 3.43% and 3.10% of earning assets, or NIM on a fully tax equivalent basis (non-GAAP), respectively. The book yield from securities was 2.67% and 2.31% for the six months ended June 30, 2026 and 2025, respectively. The yield on loans increased to 5.82% for the six months ended June 30, 2026 from 5.72% for the six months ended June 30, 2025. The increase in loan yields was primarily due to higher rates on new loans and variable rate commercial loans that continue to reprice. The cost of interest-bearing liabilities for the six months ended June 30, 2026 decreased to 2.12% from 2.25% for the six months ended June 30, 2025 primarily due to lower rates on money market and certificate of deposit products.
The provision for credit losses was $895,000 for the three months ended June 30, 2026, driven by a $465,000 increase in the ACL on loans and net charge offs totaling $384,000. The provision for credit losses for the three months ended June 30, 2025 was a credit of $1.1 million, which reflects $1.4 million in net recoveries, offset by a $242,000 increase in the ACL on loans and an increase in the reserve for unfunded commitments. Recoveries of $1.6 million during second quarter 2025 were related to overdrawn deposit accounts from a single customer that were charged off during the third quarter of 2024.
The provision for credit losses was $1.5 million for the six months ended June 30, 2026, as compared to a credit of $1.2 million for the six months ended June 30, 2025. Net charge offs for the six months ended June 30, 2026 totaled $637,000, while there were net recoveries of $1.5 million for the six months ended June 30, 2025.
Noninterest income for the three months ended June 30, 2026 and 2025 was $4.4 million and $3.7 million, respectively. Service charges and fees increased $479,000 as a result of internal initiatives designed to align fees with the market. Earnings on bank-owned life insurance (BOLI) policies increased $134,000 compared to second quarter 2025 due to additional investments in a separate account BOLI in 2025. Wealth management fees grew $132,000 due to growth in assets under management since second quarter 2025.
Noninterest income for the six months ended June 30, 2026 and 2025 was $8.7 million and $7.2 million, respectively. Service charges and fees increased $877,000 as a result of internal initiatives designed to align fees with the market. Wealth management fees grew $261,000 due to growth in assets under management. Earnings on BOLI policies increased $210,000 due to additional investments in a separate account BOLI in 2025. Other noninterest income in 2026 includes a $137,000 gain related to a death benefit from a BOLI policy.
Noninterest expenses for the three months ended June 30, 2026 and 2025 were $15.4 million and $13.7 million, respectively. Compensation and benefit expenses increased $651,000, reflecting annual merit increases, incentives, and higher medical insurance claims. Occupancy and equipment increased $240,000 and merger-related expenses of $505,000 were included in noninterest expenses in second quarter 2026.
Noninterest expenses for the six months ended June 30, 2026 and 2025 were $30.0 million and $27.0 million, respectively. Compensation and benefit expenses increased $1.2 million for the same reasons as the quarterly comparison. Occupancy and equipment expenses increased $480,000 and merger-related expenses during second quarter 2026 totaled $505,000.
Income tax expense for both of the three months ended June 30, 2026 and 2025 was $1.1 million, while the effective tax rate (ETR) was 18% for both periods. Income tax expense for both of the six months ended June 30, 2026 and 2025 was $2.1 million, while the ETR was 17% for the six months ended June 30, 2026 and 19% for the six months ended June 30, 2025. The ETR in the first six months of 2025 included a one-time tax expense totaling $166,000 due to the taxes owed from the lifetime earnings on BOLI policies that were surrendered during first quarter 2025. Excluding the one-time charge, the ETR was 17% for the first six months of 2025.