|
Banyan Tree Holdings Limited is an investment holding company that provides project design and management services for a global hospitality portfolio. The group operates hotels and resorts, spas and galleries, and branded residences across multiple countries, with a significant presence in China, Indonesia, Thailand, and the United States. Its business segments include hotel operations, managed hotel services, and the development and sale of luxury residential properties. The company manages a multi-branded ecosystem comprising 12 global brands, including the flagship Banyan Tree, Angsana, Garrya, Homm, Dhawa, and Bellaguna. Recent portfolio expansions include the acquisition of Newmark Hotels & Reserves in Africa and the launch of properties in Switzerland and the USA. The group also offers an experiential membership program called withBanyan and a digital platform named Beyond. Its residential segment focuses on luxury developments such as Bellaguna Lake Residences and Banyan Tree Beach Residences Varuna. Summarised from the company's own disclosures, fiscal year ended Jun 2026 |
Industry Lodging | Homepage groupbanyan.com |
| Sector Consumer Cyclical | IR page groupbanyan.com/investor-relations | |
|
Tags
luxury hotels, branded residences, spa services, hotel management, real estate development, hospitality brands, membership programs, Banyan Tree, Angsana, Garrya, Homm, Dhawa, Bellaguna, Newmark, withBanyan, Beyond, Mamula Island by Banyan Tree, Banyan Tree Residences West Palm Beach, Banyan Tree Mount Emei, Homm Palembang Radial, Angsana Bogor Gunung Geulis, Bellaguna Lake Residences, Bellaguna Golf Residences, Banyan Tree Beach Residences Varuna
|
Press page — |
Metrics
| Valuation | |
|---|---|
| Market cap | S$ 351.396M |
| Market cap (USD) | $ 272.491M |
| P/E | 7.47 |
| PEG | 0.03 |
| P/BV | 0.39 |
| P/S | 0.69 |
| P/OCF | -25.21 |
| P/FCF | — |
| Dividend yield | — |
| Turnover / mcap | — |
| Returns | |
|---|---|
| ROE | 4.9% |
| ROI | 3.7% |
| ROIC | 3.7% |
| Profit margin | 8.9% |
| Growth | |
|---|---|
| Revenue growing | Yes |
| Profits growing | Yes |
| Revenue up 3y | Yes |
| Revenue up 5y | Yes |
| Earnings growth 3y (net profit CAGR) | 281.2% |
| Quality | |
|---|---|
| Profitable | Yes |
| Margin expanding | Yes |
| Buying back stock | — |
| Diluting (TTM) | No |
| Debt/Equity | 29.0% |
| Podcast bulls (TTM) | Sign up |
| Podcast bears (TTM) | Sign up |
| Podcast sentiment (TTM) | Sign up |
| Podcast sentiment % (TTM) | Sign up |
| News sentiment (TTM) | 0 |
| Quality score | 60.0% |
| Insiders | |
|---|---|
| Buys, 1w | Sign up |
| Buys, 1m | Sign up |
| Buys, 1y | Sign up |
| Sells, 1w | Sign up |
| Sells, 1m | Sign up |
| Sells, 1y | Sign up |
Sign up to see this company's insider trades
| Figure | FY 2025 | FY 2024 | FY 2023 | FY 2022 | FY 2021 | FY 2020 | FY 2019 | FY 2018 | FY 2017 | FY 2016 | FY 2015 | FY 2014 | FY 2013 | FY 2012 | FY 2011 | FY 2010 | FY 2009 | FY 2008 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue | 477.363M | 380.638M | 327.911M | 271.328M | 221.228M | 157.832M | 346.954M | — | — | — | — | — | — | 338.416M | 329.492M | — | — | — |
| Net profit | 42.487M | 42.104M | 31.708M | 767K | -55.192M | -95.838M | 49.172M | 4.186M | -724K | 15.726M | -22.687M | 31.256M | 10.044M | 14.863M | 1.554M | 17.002M | -48.672M | 2.505M |
Sign up to see institutional holdings
Sign UpPodcast Mentions
Sign up to see podcast mentions and sentiment
Sign UpAnnouncements made on SGXNet, newest first, routine notices (disclosures of interest, daily buy-backs, listing confirmations, coupons) included. The link opens the announcement on SGX. Press releases from the company's own website, newest first.
ANNOUNCEMENT ACQUISITION OF SHARES IN NEWMARK HOTELS PROPRIETARY LIMITED
INTRODUCTION Banyan Tree Holdings Limited (the "Company" and together with its subsidiaries, the "Group") wishes to announce that Banyan Tree Hotels & Resorts Pte. Ltd. ("BTHR" or the "Acquirer"), a direct wholly-owned subsidiary of the Company, has on 17 September 2026 entered into a share purchase and subscription agreement (the "SPSA") for the acquisition and subscription by BTHR of all of the issued shares ("Shares", all of which are ordinary shares) of Newmark Hotels Proprietary Limited ("Newmark") from Garth Musikanth ("Garth") and for the subscription for further shares to be issued by Newmark. Newmark will in turn repurchase all of the Shares from the trustees for the time being of the Natreb Trust ("Natreb Trust") and KCSA PE 1 Proprietary Limited ("Kloof") (Natreb, Kloof and Garth are collectively referred to as, the "Existing NM Shareholders"). The acquisition, subscription and repurchase will be implemented in two (2) tranches (the "Transaction"). Newmark Incorporated in South Africa in 2007 and headquartered in Cape Town, Newmark is an established hospitality management company with a regional presence across Africa. As at the date of this Announcement, Newmark manages a portfolio of 26 hotels, lodges and reserves comprising more than 1,300 keys across seven countries: Mauritius, Namibia, Nigeria, South Africa, Tanzania, Uganda and Zimbabwe. Prior to the Transaction, the shareholders and board of directors of Newmark are as follows: (a)
Shareholders: Natreb Trust, Kloof, and Garth collectively holding 100% of the Shares of Newmark.
(b)
Board of Directors: Neil Markovitz ("Neil") and Garth are the directors of Newmark, and currently hold the following management roles: (A)
Neil, who is also the founder, is the Chief Executive Officer ("CEO") of Newmark; and
(B)
Garth is the Global Chief Finance Officer ("GCFO") of Newmark.
Both individuals will continue in their respective roles after Tranche 1 Closing (as defined below).
RATIONALE FOR THE TRANSACTION AND BENEFIT TO THE GROUP The Company considers that the Transaction will be beneficial to the Group and is consistent with its long-term growth strategy, including the continued diversification of its hospitality portfolio and expansion in markets where the Group has a limited presence. The Company is of the view that Newmark is an established hospitality management company in Africa, with an experienced management team, strong regional presence, deep local market knowledge, trusted owner and partner relationships and a proven operating track record across heritage and city hotels, nature and country lodges, island retreats and private game reserves. The Transaction will extend the Group's geographical reach in Africa and strengthen its regional operating, distribution and development capabilities. Newmark's established platform and network will also provide a base from which the Group can pursue further opportunities across the region. The Transaction will also broaden the Group's portfolio across urban, nature-based, wellbeing and wildlife hospitality. Newmark's mix of city hotels, which generate strong fee contributions, together with its nature-based stays and private game reserves, complements the Group's existing portfolio and expands the scale and diversity of its management business in Africa. Newmark's hospitality management business also advances the Group's asset-right strategy through a portfolio of long-term management contracts and an established pipeline of opportunities for future growth. The combination of Newmark's regional expertise and specialist operating capabilities with the Group's distribution, development and commercial capabilities is expected to support the growth of a distinctive hospitality platform in Africa, one of the world's fastest-growing tourism regions, with particular strengths in nature-based and wildlife hospitality.
INFORMATION ON THE PARTIES
3.1
BTHR BTHR is an existing direct wholly-owned subsidiary of the Company which provides management consultancy services for hotels.
3.2
EXISTING NM SHAREHOLDERS The following information on the Existing NM Shareholders, who are third parties, was provided to the Company by the Existing NM Shareholders: (a)
Natreb Trust is a trust duly established in accordance with the South African Trust Property Control Act, 57 of 1988.
(b)
Kloof is a private company incorporated under the laws of South Africa. 2
(c)
Garth is an individual who serves as GCFO of Newmark.
THE TRANSACTION
4.1
Transaction Structure The SPSA provides that the Transaction shall be carried out in two (2) tranches: (a)
Initial acquisition of 70% stake in Newmark ("Tranche 1 Transactions") The Tranche 1 Transactions will be implemented through a series of transactions resulting in aggregate in: (i)
the transfer to BTHR of 28 Shares held by Garth (representing 70% of all of the Shares held by Garth in Newmark immediately prior to the Tranche 1 Transactions);
(ii)
subscription of 252 new Shares of Newmark by BTHR; and
(iii)
repurchase of 252 Shares held by Natreb Trust and Kloof (representing 70% of all of the Shares held by each of Natreb Trust and Kloof in Newmark immediately prior to the Tranche 1 Transactions). All of the repurchased Shares will be cancelled.
The completion of the above will collectively result in a pro rata reduction of each of the Existing NM Shareholders' original shareholding interest in Newmark to 30%, and will result in BTHR holding the remaining 70% of all issued Shares in Newmark immediately after closing of Tranche 1 Transactions ("Tranche 1 Closing"). (b)
Acquisition of remaining 30% stake in Newmark ("Tranche 2 Transactions") Subject to Tranche 1 Closing, Tranche 2 Transactions will be implemented through a series of transactions resulting in aggregate in: (i)
the transfer to BTHR of the remainder of the Shares held by Garth in Newmark after Tranche 1 Closing (being 12 Shares);
(ii)
subscription of 108 new Shares of Newmark by BTHR; and
(iii)
repurchase of the remainder of the Shares held by each of Natreb Trust and Kloof in Newmark after Tranche 1 Closing (being 108 Shares) ("Tranche 2 Repurchase"). The repurchased Shares will all be cancelled.
After closing of Tranche 2 Transactions ("Tranche 2 Closing"), BTHR will hold 100% of the issued Shares in Newmark. 3
4.2
Consideration for the Transaction The estimated aggregate consideration and subscription amount ("Consideration") payable by BTHR for the purchase of Shares from Garth and the subscription for the 360 Shares to be issued by Newmark is ZAR756 million (approximately S$60 million1), subject to adjustments as set out in the SPSA.2 The Consideration was arrived at after arm's length negotiations, on a willing-buyer and willingseller basis and taking into consideration, inter alia, Newmark's historical performance and future growth potential, and comparable price-earnings multiples for the relevant industry. It is intended that the Consideration will be paid using internal resources. The Consideration shall be payable in two (2) separate tranches as described in paragraphs 4.3 and 4.4.
4.3
Tranche 1 Consideration The amount of the aggregate consideration for the Tranche 1 Transactions ("Tranche 1 Consideration") is ZAR 533 million (approximately S$42 million), payable in cash. This figure is derived from 70% of an adjusted equity value ("Adjusted Equity Value") of Newmark. The Adjusted Equity Value is calculated based on an agreed enterprise value of ZAR 756 million (approximately S$60 million) for Newmark (by applying an agreed earnings multiple on the targeted stabilised EBITDA of Newmark of ZAR 63 million ("Targeted Stabilised EBITDA") for its financial year ending 28 February 2029 ("Newmark FY2029")), after taking into account the cash, debt and working capital of Newmark as at 30 June 2026 (being the end of Newmark's most recent unaudited management accounts for the last six (6) months, "Newmark June 2026 Unaudited Financial Statements"). The Tranche 1 Consideration is subject to any adjustment for leakages as agreed or determined in accordance with the SPSA.
4.4
Tranche 2 Consideration The amount of consideration for the Tranche 2 Transactions ("Tranche 2 Consideration") will be payable in cash and be determined based on 30% of the equity value of Newmark for the financial year ending 28 February 2030 ("Newmark FY2030"), with such equity value being calculated by applying the agreed earnings multiple to the actual EBITDA as reflected in Newmark's audited financial statements for Newmark FY2030 ("Newmark FY2030 Audited Financial Statements") after adjusting for cash, debt, and working capital, and the Tranche 2 Price Adjustment (as defined and discussed below) (if applicable).
1
Unless otherwise stated, all Singapore dollar (S$) equivalent of South Africa Rand (ZAR) amounts in this Announcement are based on actual spot transaction rate of S$1.00: ZAR12.56. This rate is solely for illustrative purposes in this Announcement, and this should not be construed as a representation that the relevant amounts have been or could be converted at this exchange rate or at any other rate. 2 For the purposes of estimating the amount of the Consideration, potential adjustments to Tranche 2 Consideration (including Tranche 2 Price Adjustment (as defined below), if applicable) as set out in paragraph 4.4 of this Announcement and as set out in the SPSA have not been taken into account. It is assumed that no Tranche 2 Trigger Events have occurred. As explained in paragraph 4.4 of this Announcement, the exact adjusted Tranche 2 Consideration cannot be determined as at the date of this Announcement.
4
Price Adjustment Mechanism To keep Newmark on track to continue to achieve good performance post-acquisition by the Company, the Acquirer has built a downward price adjustment mechanism into the Tranche 2 Consideration, which will kick in based on whether Newmark attains the Targeted Stabilised EBITDA in Newmark FY2029 or where applicable, Newmark FY2030. (a)
Based on Newmark's audited financial statements for Newmark FY2029 ("Newmark FY2029 Audited Financial Statements"), if Newmark's actual EBITDA for Newmark FY2029 is lower than the Targeted Stabilised EBITDA, there will be a reduction in the Tranche 2 Consideration equivalent to 70% of the agreed multiple of such shortfall 3. The Acquirer has the discretion to delay the determination of such reduction (if any) to Newmark FY2030 if Newmark's actual enterprise value in Newmark FY2029 is lower than 70% of the agreed enterprise value of ZAR 756 million (approximately S$60 million); and
(b)
the Tranche 2 Consideration may also be reduced to account for agreed indemnified matters ("Agreed Price Reduction") prior to Newmark FY2030,4
such reduction(s) to the Tranche 2 Consideration are referred to as the "Tranche 2 Price Adjustment". Targeted Stabilised EBITDA The Company considers that the Targeted Stabilised EBITDA (which in turn determines the Tranche 2 Price Adjustment, if applicable) is acceptable, taking into consideration the following principal assumptions and commercial bases: (a)
Newmark's historical performance and growth potential, such as: (i)
based on Newmark's audited financial statements for its financial year ending 28 February 2026 ("Newmark FY2026", and such audited financial statements, the "Newmark FY2026 Audited Financial Statements"), Newmark has an EBITDA (less one off transaction costs) of approximately ZAR 28.8 million and Newmark's EBITDA compounded annual growth rate of 17.8% over the past 3 financial years; and
(ii)
pipeline of potential hotel management engagements, based on the various term sheets which Newmark has already signed in relation to a number of
3
Such reduction does not apply to certain limited situations such as the occurrence of a Trigger Event due to a default of the Acquirer under the SPSA and Shareholders' Agreement. Further, as this is structured as a reduction to the Tranche 2 Consideration, the maximum potential amount of such reduction (specifically pursuant to Newmark's actual EBITDA for Newmark FY2029 being lower than the Targeted Stabilised EBITDA) is capped by the amount of the Tranche 2 Consideration. 4 See also paragraph 4.7(c). Such reduction (if any) specifically pursuant to the Agreed Price Reduction will additionally be covered by the said escrow arrangement, as well as guarantees provided by certain shareholders of the Existing NM Shareholders in favour of the Acquirer (to guarantee the performance of the relevant Existing NM Shareholders' obligations to pay their respective proportions of the Agreed Price Reduction which is not otherwise covered by the amount held in escrow).
5
potential engagements. Newmark has also informed the Acquirer of various other opportunities which are currently under discussion with prospective customers. Based on the foregoing, the Company believes that Newmark can achieve the Targeted Stabilised EBITDA by Newmark FY2029; (b)
the continued appointments of Newmark's existing CEO and GCFO. Maintaining an experienced management team in the post-acquisition transition phase will help to provide stability in leadership post-acquisition;
(c)
comparable price-earnings multiples for the relevant industry; and
(d)
the potential for further synergies between Newmark and the Group.
Taking into account the various factors listed in sub-paragraphs (a) to (d) above in its consideration, the board of the directors of the Company ("Board") is of the view that setting a Targeted Stabilised EBITDA, and building in the Tranche 2 Price Adjustment to the Tranche 2 Consideration, are acceptable and beneficial to the Company. As the Tranche 2 Price Adjustment will be deducted from the Tranche 2 Consideration (i.e. reducing any amount payable for the remaining 30% stake in Newmark), the Board considers that this feature is an inherent safeguard for the Acquirer. Tranche 2 Trigger Event(s) (potential impact on calculation of Tranche 2 Consideration) However, upon the occurrence of a Tranche 2 Trigger Event (as defined below) which results in an acceleration of Tranche 2 Closing, the Tranche 2 Consideration will be determined with reference to the equity value of Newmark based on its management accounts for the 12 months immediately prior to the date on which the Tranche 2 Trigger Event occurs, taking into account the cash, debt and working capital of Newmark as at the date immediately prior to the date on which the Tranche 2 Trigger Event occurs ("Trigger Event Equity Value"). Depending on the nature of the Trigger Event, the Tranche 2 Consideration will be either the higher or the lower of 30% of (a) the Adjusted Equity Value and (b) the Trigger Event Equity Value, subject to Tranche 2 Price Adjustment where applicable. Please refer to paragraph 4.5 for further details on Tranche 2 Trigger Events. 4.5
Closing of Tranche 2 Transactions After Tranche 1 Transactions are completed, Tranche 2 Closing will take place after the final determination of the Tranche 2 Consideration in accordance with the SPSA. Tranche 2 Closing may be accelerated upon occurrence of certain events, including but not limited to (a) the cessation of Newmark's existing CEO's employment with Newmark under specific circumstances, (b) any deadlock between the shareholders of Newmark in accordance with the Shareholders' Agreement (as defined below), and (c) any default of any shareholder of Newmark in accordance with the Shareholders' Agreement (collectively, "Tranche 2 Trigger 6
Events", and each, a "Tranche 2 Trigger Event"). If a relevant Tranche 2 Trigger Event has occurred, Tranche 2 Consideration will be computed in the manner set out in paragraph 4.4. 4.6
Shareholders' Agreement The Parties also intend to enter into a shareholders' agreement on the date of Tranche 1 Closing ("Shareholders' Agreement") to regulate the affairs of Newmark and the respective rights of BTHR and the Existing NM Shareholders as shareholders of Newmark.
4.7
Other Key Terms (a)
Funding for Newmark Under the SPSA, if Newmark is unable to carry out the Tranche 2 Repurchase because it fails the solvency and liquidity test set out in the Companies Act of South Africa, BTHR and the Existing NM Shareholders are required to contribute additional funding, based on their shareholding proportions, into Newmark via a subscription of Shares to enable Newmark to satisfy the solvency and liquidity test. The amount of additional funding that BTHR is required to contribute is capped at ZAR10.5 million (approximately S$0.8 million).
(b)
Corporate Guarantee The Company has provided a corporate guarantee in favour of the Existing NM Shareholders to guarantee the performance of BTHR's obligation to pay the Tranche 2 Consideration under the SPSA.
(c)
Agreed Price Reduction To safeguard the payment of the Agreed Price Reduction, the Existing NM Shareholders have agreed to place a portion of the Tranche 1 Consideration in escrow for a period of time. Parties related to the Existing NM Shareholders will also provide guarantees in favour of the Acquirer to guarantee the performance of certain Existing NM Shareholders' obligations to pay their respective proportions of the Agreed Price Reduction which is not otherwise covered by the amount held in escrow.
FINANCIAL INFORMATION ON THE TRANSACTION (a)
Book Value and Net Tangible Asset Value Based on the Newmark June 2026 Unaudited Financial Statements, the book value and net tangible asset value attributable to the entire issued share capital of Newmark (the "Transaction Assets") is S$2.43 million.
7
(b)
Latest Available Open Market Value There is no available open market value of Transaction Assets as the Shares of Newmark are not listed or traded on any securities exchange. No external independent valuation of the Transaction Assets was commissioned for the purpose of the Transaction. A bid process was conducted by the Existing NM Shareholders. The Acquirer had consulted KPMG during the bid process and submitted a successful bid which took into account transacted earnings multiples of various comparable transactions identified by the Acquirer.
(c)
Net Profits Attributable to the Transaction Assets Based on the Newmark June 2026 Unaudited Financial Statements, the net profit of Newmark is S$0.07 million.
RELATIVE FIGURES UNDER CHAPTER 10 OF THE LISTING MANUAL
6.1
Chapter 10 of the Listing Manual of the Singapore Exchange Securities Trading Limited ("Listing Manual") classifies transactions by the Company into (a) non-disclosable transactions, (b) disclosable transactions, (c) major transactions and (d) very substantial acquisitions or reverse takeovers, depending on the size of the relative figures computed on, inter alia, the applicable bases of comparison set out in Rule 1006 of the Listing Manual. The following two bases are relevant to the Transaction (being an acquisition): (a)
Rule 1006(b): the net profits attributable to the assets acquired, compared with the Group's net profits; and
(b)
Rule 1006(c): the aggregate value of the consideration given, compared with the Company's market capitalisation.
8
The relevant relative figures for the Transaction computed on the bases set out above are as follows: Rule 1006(1)
Newmark
Group
Relative Figure (%)
(b) Net profits(2) (S$ million)
0.07(3)
30.42(4)
0.23%
(c) Aggregate Consideration for the Transaction against Company's market capitalisation (S$ million)
60.18(5)
429.48 (6)
14.01%
Notes:
6.2
(1)
Rule 1006(a) of the Listing Manual does not apply to an acquisition of assets. Rule 1006(d) is not applicable as the Transaction does not involve any issue of equity securities by the Company. Rule 1006(e) is not applicable to the Transaction.
(2)
Under Rule 1002(3) of the Listing Manual, "net profits" is defined as profit or loss including discontinued operations that have not been disposed and before income tax and non-controlling interests.
(3)
The net profits are taken from the Newmark June 2026 Unaudited Financial Statements. Consistent with Rule 1002(3), this figure is stated before income tax and non-controlling interests.
(4)
Based on the unaudited consolidated financial statements of the Group for the six (6) months ended 30 June 2026 ("BTH 1H2026 Unaudited Financial Statements").
(5)
Based on the estimated Consideration payable for purchase of Shares from Garth and the subscription for the 360 Shares to be issued by Newmark as elaborated in paragraph 4.2. For the purposes of the estimated Consideration, potential adjustments to Tranche 2 Consideration (including Tranche 2 Price Adjustment, if applicable) as set out in paragraphs 4.4 of this Announcement and as set out in the SPSA have not been taken into account. It is assumed that no Tranche 2 Trigger Events have occurred. As explained in paragraph 4.4 of this Announcement, the exact Tranche 2 Consideration cannot be determined as at the date of this Announcement.
(6)
Based on 867,645,208 ordinary shares in the capital of the Company in issue and the weighted average price of S$0.495 per ordinary share on the SGX-ST on 16 September 2026, being the trading day immediately prior to the date of this Announcement.
Pursuant to Chapter 10 of the Listing Manual, where an acquisition of assets is one where any of the relative figures as computed on the bases set out in Rule 1006 exceeds 5% (but no 9
relative figure exceeds 20%), the transaction is classified as a "disclosable transaction" under Chapter 10 of the Listing Manual. 6.3
As only the relative figure in respect of the Transaction as computed on the bases set out in Rule 1006(c) exceeds 5% (but does not exceed 20%), the Transaction constitutes a "disclosable transaction" under Chapter 10 of the Listing Manual. Accordingly, the approval of the shareholders of the Company will not be required for the Transaction.
ILLUSTRATIVE FINANCIAL EFFECTS
7.1
FOR ILLUSTRATIVE PURPOSES ONLY: The pro forma financial effects of the Transaction on the NTA per Share and earnings per Share ("EPS") presented below are strictly for illustrative purposes only and do not represent the Company's actual financial performance or position after closing of the Transaction. The pro forma financial effects in this paragraph were prepared based on the audited consolidated financial statements of the Group for the financial year ended 31 December 20255 and the following assumptions:
7.2
(a)
all issued Shares of Newmark have been acquired and subscribed for by the Acquirer at the estimated aggregate Consideration (as set out in paragraph 4.2); and
(b)
potential adjustments to Tranche 2 Consideration (including Tranche 2 Price Adjustment, if applicable) as set out in paragraph 4.4 of this Announcement and as set out in the SPSA have not been taken into account. It is assumed that no Tranche 2 Trigger Events have occurred. As explained in paragraph 4.4 of this Announcement, the exact Tranche 2 Consideration cannot be determined as at the date of this Announcement.
NTA per Share FOR ILLUSTRATIVE PURPOSES ONLY: The pro forma financial effects of the Transaction on the consolidated NTA per Share of the Company as at 31 December 2025, on the assumption that the Transaction was completed on 31 December 2025 (being the end of the relevant financial year), are as follows: Before the Transaction
After the Transaction
793
775
866,903,908
866,903,908
0.91
0.89
Consolidated NTA (S$ million) Number of Shares (excluding treasury shares) NTA per Share (S$)
5
Rule 1010(9) prescribes that the Company's most recently completed financial year should be the basis of calculation of illustrative NTA and EPS impact. Newmark has a different financial year end from the Company. Accordingly, the illustrative NTA and EPS impact as shown in paragraphs 7.2 and 7.3 are computed using financial information for Newmark FY2026, which is the most recently completed financial year for Newmark, and based on the Newmark FY2026 Audited Financial Statements.
10
7.3
EPS FOR ILLUSTRATIVE PURPOSES ONLY: The pro forma financial effects of the Transaction on the consolidated EPS of the Company for the financial year ended 31 December 2025, on the assumption that the Transaction was completed on 1 January 2025 (being the start of the relevant financial year), are as follows: Before the Transaction
After the Transaction
Consolidated net profits attributable to shareholders of the Company (S$ million)
42.49
43.49
Weighted average number of issued shares of the Company (excluding treasury shares)
866,799,613
866,799,613
4.90
5.02
EPS (Singapore cents)
DISCLOSURE OF INTERESTS Except in respect of his/her/its shareholding (if any) in the Company, based on the latest information available to the Company, none of the directors or the controlling shareholders of the Company has any interest, direct or indirect, in the Transaction.
NO DIRECTORS' SERVICE CONTRACTS No person is proposed to be appointed as a director of the Company in connection with the Transaction.
DOCUMENT(S) FOR INSPECTION A copy of the SPSA will be made available for inspection during normal business hours at the registered office of the Company at 211 Upper Bukit Timah Road, Banyan Tree House, Singapore 588182, for a period of three (3) months commencing from the date of this Announcement.
11
BY ORDER OF THE BOARD
Eddy See Hock Lye Chief Executive Officer 17 September 2026
12
FOR IMMEDIATE RELEASE
Banyan Group Announces Acquisition of Newmark Hotels & Reserves, Adding 26 Hotels, Lodges, and Reserves Across Seven African Countries Newmark’s deep regional expertise across urban, nature and wildlife hospitality will expand Banyan Group’s scale and nature-based hospitality platform in one of the world’s fastestgrowing tourism regions.
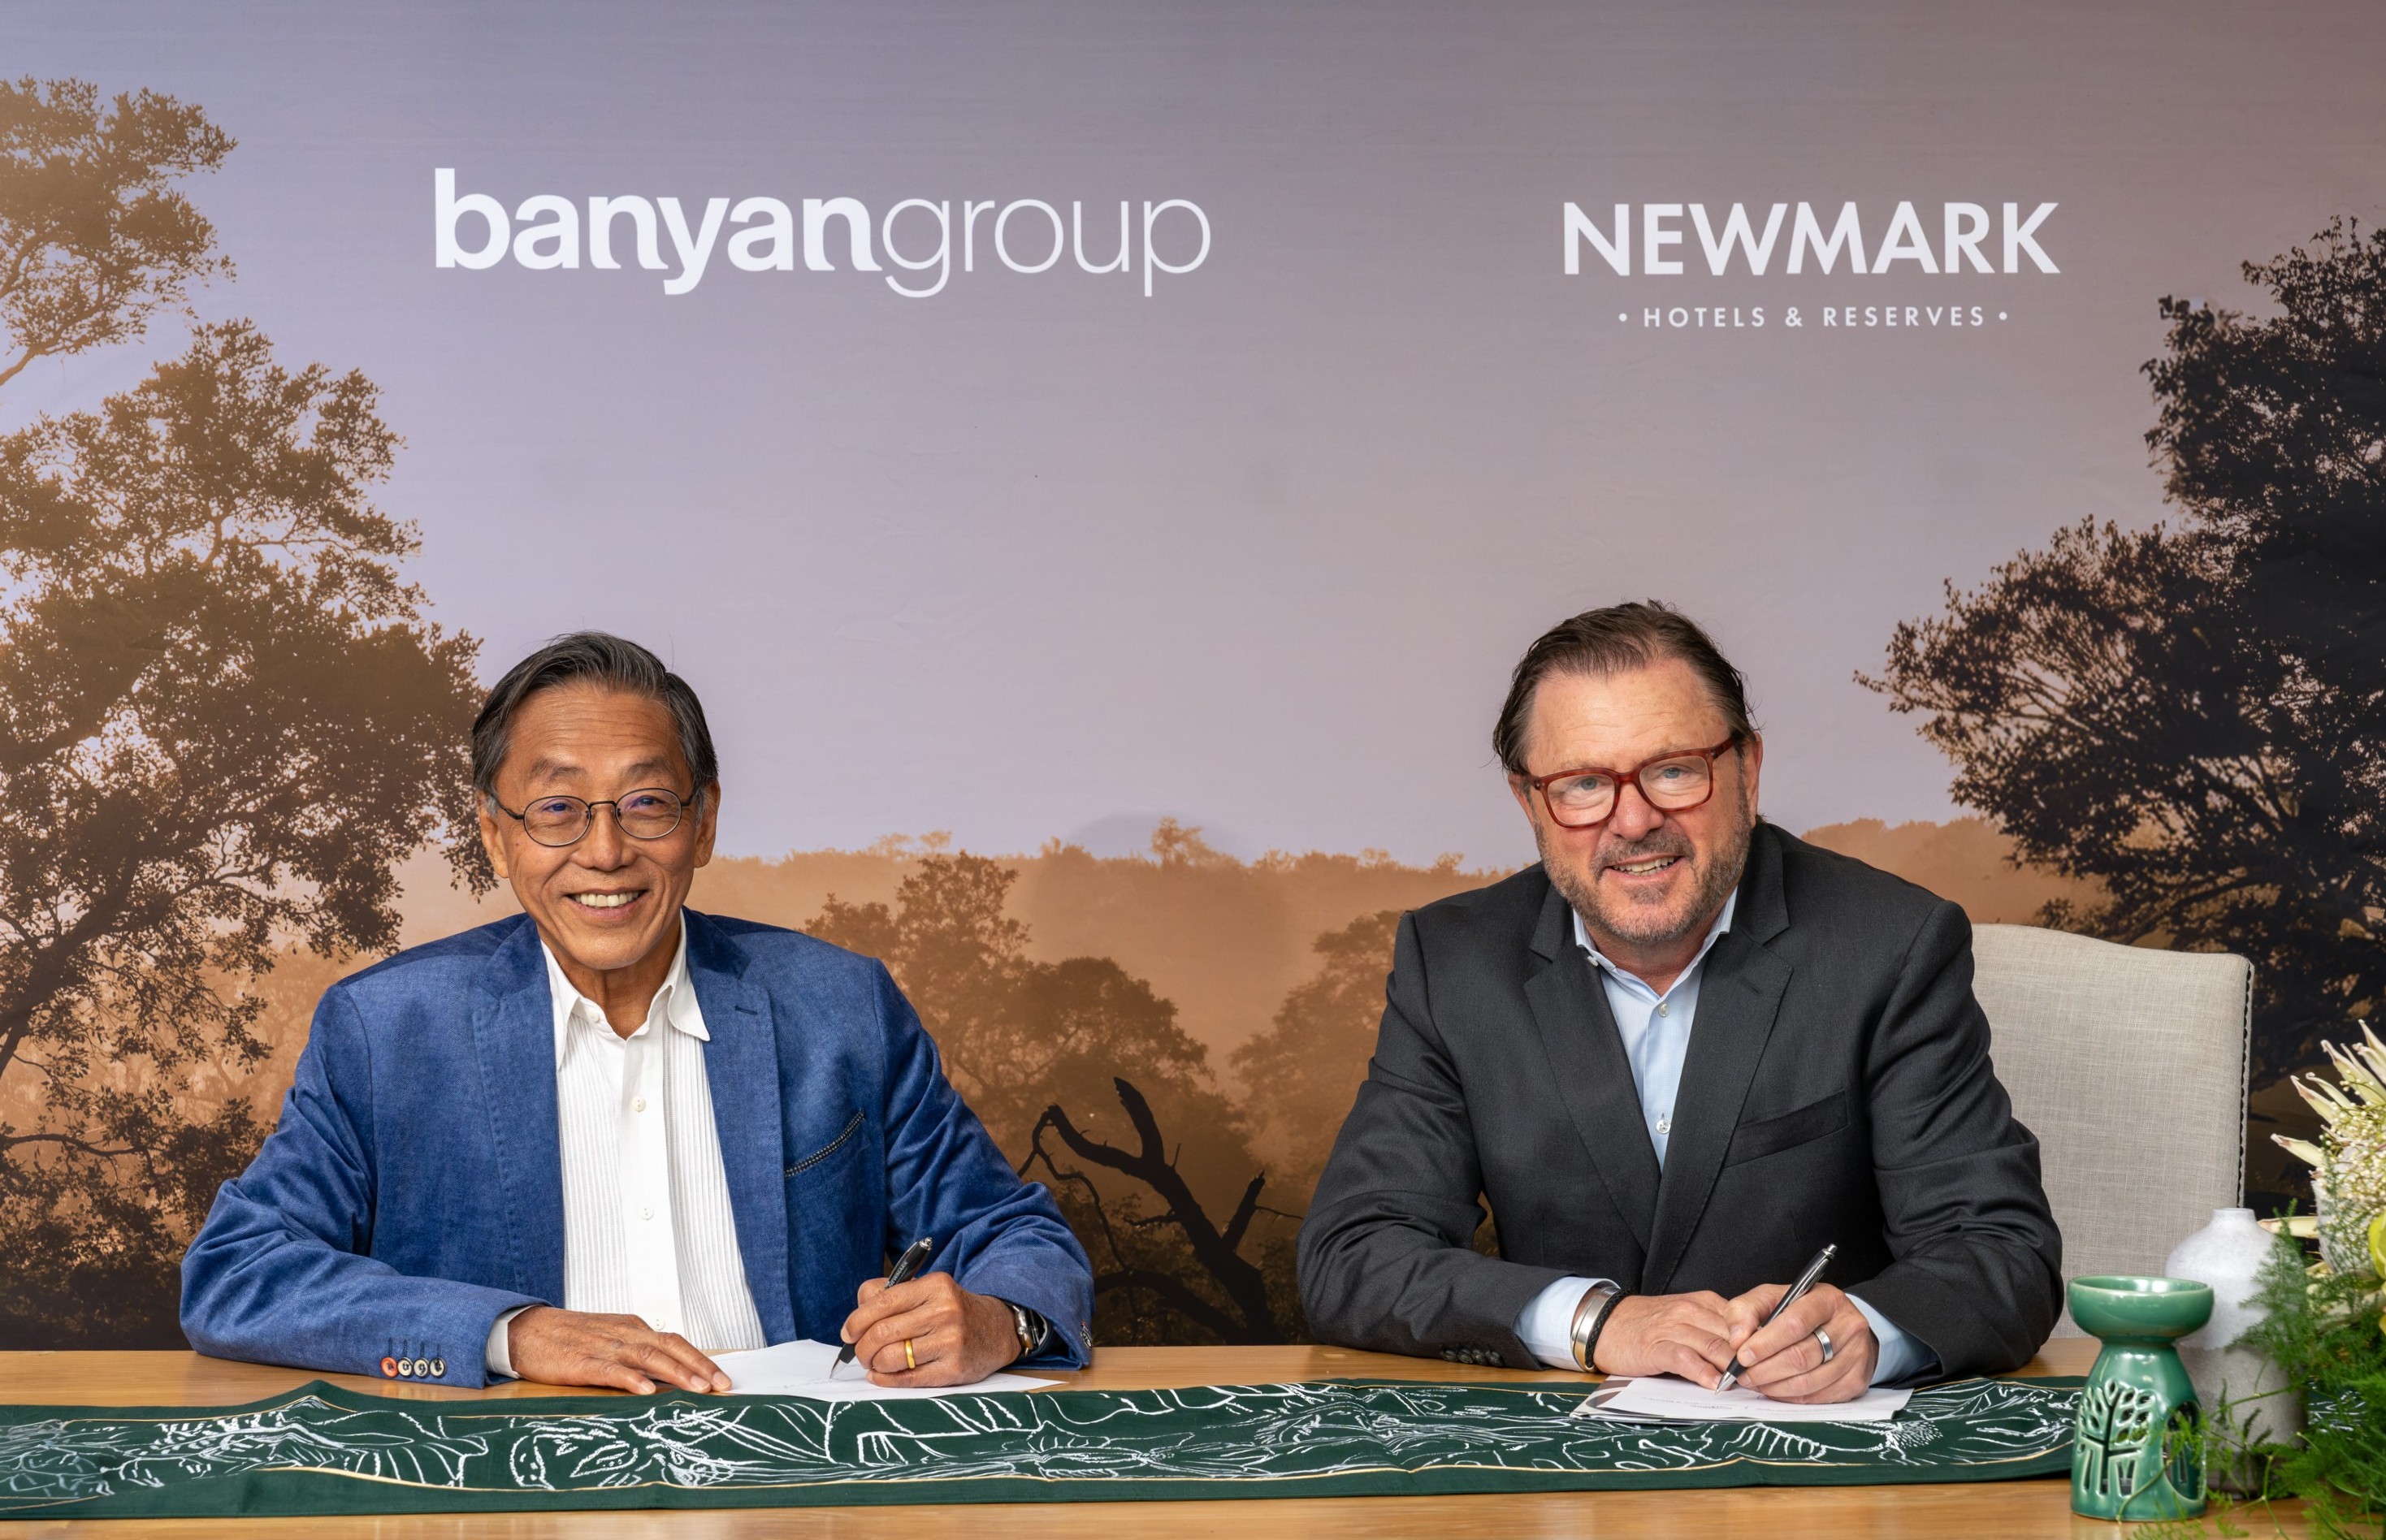
From Left: Banyan Group Founder and Executive Chairman Ho Kwon Ping, Newmark Hotels & Reserves Founder and Chief Executive Officer, Neil Markovitz
Singapore and Cape Town, 17 September 2026 – Banyan Group (“Banyan Tree Holdings Limited” or the “Group” – SGX: B58), an independent global hospitality company, today announced a strategic partnership with Newmark Hotels & Reserves (“Newmark”), a Cape Town-headquartered hospitality management company, and the acquisition of a majority stake in Newmark under a phased ownership structure leading to full ownership over time. As part of the partnership, Newmark joins Banyan Group as a collection brand, bringing its managed portfolio of 26 hotels, lodges and reserves across seven countries including Mauritius, Namibia, Nigeria, South Africa, Tanzania, Uganda and Zimbabwe, while retaining its existing brand, teams and local operating approach to preserve the deep market knowledge and long-standing relationships that have contributed to its success. With the addition of Newmark Collection, Banyan Group’s portfolio will comprise nearly 130 hotels, resorts and reserves, more than 30 branded residences, and over 140 spas and galleries across 14 hospitality and residential brands in 28 countries.
Banyan Tree Holdings Limited 211 Upper Bukit Timah Road, Singapore 588182 Tel: +65 68495888 | Email: [email protected] | groupbanyan.com | Reg No: 200003108H
The partnership brings together Newmark’s regional expertise and established hospitality management platform across urban, nature-based and wildlife hospitality with Banyan Group’s international distribution, development and commercial capabilities, supporting Newmark’s continued growth across Africa and greater international reach. “We welcome Newmark to Banyan Group with confidence in the strength of the business it has built in Africa and the entrepreneurial spirit that has shaped it,” said Ho Kwon Ping, Founder and Executive Chairman of Banyan Group. “We see in Newmark many of the qualities that shaped Banyan Group from the beginning: independence of thought, a longterm view and the conviction to build something distinctive. We look forward to what we can build together across Africa.” “Over nearly two decades, Newmark has built its business through strong teams, trusted owner and partner relationships and a portfolio where each property retains its own identity,” said Neil Markovitz, Founder and Chief Executive Officer of Newmark Hotels & Reserves. “Joining Banyan Group gives us greater international reach and access to a wider network of expertise while retaining what has made Newmark successful. It also gives us greater scope to introduce travellers around the world to the destinations and experiences across our portfolio.”
From Cape Town to Africa’s Wild Heart Newmark was founded in 2007 by Neil Markovitz, whose career in Cape Town hospitality dates to 1990 and includes serving as General Manager of the Victoria & Alfred Hotel. Housed in a converted 1904 warehouse overlooking Cape Town’s harbour and Table Mountain, the hotel was the first to open at the V&A Waterfront and later became one of the first properties in Newmark’s portfolio. Today, Newmark’s collection stretches from Cape Town, beneath iconic Table Mountain, and Victoria Falls, two of the world’s most celebrated natural wonders, to some of Africa’s most remarkable landscapes and destinations. Its curated portfolio spans heritage and city hotels, nature and country lodges, island retreats and private game reserves, offering a diverse mix of urban, nature-based, wellbeing and wildlife experiences. In South Africa’s Waterberg, QWABI Private Game Reserve spans 11,000 hectares within a UNESCO-designated biosphere, combining a Big Five safari experience with the regeneration of land previously used for agriculture. In the Greater Kruger ecosystem, Motswari Private Game Reserve celebrates its 50th anniversary in 2026, shaped by a long history of conservation. Motswari has been part of the Newmark portfolio since 2013. Further north, Gorilla Heights Lodge sits on the edge of Uganda’s UNESCO-listed Bwindi Impenetrable National Park, home to endangered mountain gorillas. Future Found Sanctuary, set on the slopes of Table Mountain, brings a regenerative wellness dimension through experiences rooted in nature and restoration, while Newmark’s presence in Zanzibar and Mauritius adds Indian Ocean island experiences to the portfolio.
Banyan Tree Holdings Limited 211 Upper Bukit Timah Road, Singapore 588182 Tel: +65 68495888 | Email: [email protected] | groupbanyan.com | Reg No: 200003108H
From One Vision to a Wider World of Discovery From its first flagship Banyan Tree resort in Phuket, developed following the rehabilitation of a former tin-mining site and recognised for pioneering naturally luxurious and ecologically sensitive hospitality, Banyan Group has expanded over more than three decades into a global, multi-brand hospitality business. Its pioneering spirit, design-led experiences and commitment to responsible stewardship continue to shape its growth. In 2025, the Group marked its 100th resort globally with the opening of Mandai Rainforest Resort by Banyan Tree, a symbolic homecoming to Singapore. Africa has been a growing part of that expansion. Banyan Group’s existing footprint in the region comprises four hotels and four spas across Morocco, Mauritius, South Africa and Tanzania, including Banyan Tree Tamouda Bay, Marrakech Riads, Angsana Heritage Collection and Ubuyu, a Banyan Tree Escape, its first safari lodge. The Group is also set to enter West Africa with the upcoming Dhawa Ouidah in Benin. Newmark broadens Banyan Group’s regional network, extending its presence into Namibia, Nigeria, Uganda and Zimbabwe, while adding specialist expertise in wildlife and nature-based hospitality. The partnership comes amid strong travel demand across Africa. The continent welcomed 81 million international tourist arrivals in 2025, up 8% year on year, the strongest growth among global regions, according to UN Tourism. WTTC expects the region’s Travel & Tourism economy to grow a further 5.4% in 2026, placing Africa among the world’s fastest-growing tourism regions. Eddy See, President and Chief Executive Officer of Banyan Group, said: “Africa is a long-term growth market for Banyan Group. Newmark brings an established management business, long-standing owner relationships and strong operating capabilities that deepen our presence in the region and strengthen our asset-right model. Its local market knowledge and development pipeline, combined with Banyan Group’s international sales, distribution and development network, give us a stronger platform to pursue the right opportunities across Africa.”
Continuity and the Next Stage of Growth Newmark will continue to operate under its existing brand and leadership, led by Neil Markovitz and the current management team. Day-to-day operations, property branding, owner relationships and existing commercial arrangements will remain unchanged, with Newmark’s local teams continuing to lead relationships with owners, guests, partners and communities. “Newmark’s hotels, lodges and reserves are closely connected to the places in which they operate,” said Ho Ren Yung, Deputy Chief Executive Officer of Banyan Group. “We want to preserve that local approach, particularly in nature-based and wildlife hospitality, where culture, communities and the natural environment are integral to the guest experience. As we grow together, we want each property to retain the character and sense of place that have shaped its success.”
Banyan Tree Holdings Limited 211 Upper Bukit Timah Road, Singapore 588182 Tel: +65 68495888 | Email: [email protected] | groupbanyan.com | Reg No: 200003108H
Newmark will retain its own brand presence and direct channels, including the Newmark website. Guests can continue to book through existing channels, with all confirmed reservations honoured under their existing terms. Over time, Newmark properties will also become available through Banyan Group’s booking platforms and participate in withBanyan, its guest recognition programme, giving members access to rates and benefits at participating properties while extending Newmark’s reach to Banyan Group’s global audience. As integration progresses, guests will have a more connected way to discover, book and be recognised across both portfolios, united by a shared commitment to sustainability, conservation and meaningful travel. Discover more at www.groupbanyan.com and www.newmarkhotels.com.
For high-resolution images, please download here.
Media Relations (International) Charmaine Lin Senior Director, Group Communications Banyan Group [email protected]
Dawn Teo Manager, Group Communications Banyan Group [email protected]
ABOUT BANYAN GROUP Banyan Group (“Banyan Tree Holdings Limited” or the “Group” - SGX: B58) is an independent, global hospitality company with purpose. The Group prides itself on its pioneering spirit, design-led experiences and commitment to responsible stewardship. Its extensive portfolio spans nearly 130 hotels, resorts and reserves, over 30 branded residences and more than 140 spas and galleries in 28 countries. Comprising 14 hospitality and residential brands, including the flagship brand Banyan Tree, each distinct yet united under the experiential membership programme withBanyan. The founding ethos of “Embracing the Environment, Empowering People” is embodied through the Banyan Global Foundation and Banyan Academy. Banyan Group is committed to remaining the leading advocate of sustainable travel, with a focus on regenerative tourism and innovative programmes that elevate the guest experience. ABOUT NEWMARK HOTELS & RESERVES Founded in 2007 and headquartered in Cape Town, Newmark Hotels & Reserves is an African hospitality management company and part of Banyan Group where it operates a collection brand of nearly 30 properties across Mauritius, Namibia, Nigeria, South Africa, Tanzania, Uganda and Zimbabwe. Newmark lives by the promise of “Experience Authentic”, creating distinctive experiences rooted in the location, culture, natural setting and people of each property. Its portfolio ranges from heritage and city hotels, nature and country lodges, island retreats and private game reserves, offering a diverse mix of urban, nature-based, wellbeing and wildlife experiences. Across South Africa, Newmark’s presence extends from Cape Town’s V&A Waterfront and the Karoo to the UNESCO Waterberg Biosphere, Greater Kruger and the Greater Makalali Private Game Reserve. Further afield, guests can Banyan Tree Holdings Limited 211 Upper Bukit Timah Road, Singapore 588182 Tel: +65 68495888 | Email: [email protected] | groupbanyan.com | Reg No: 200003108H
experience gorilla trekking in Uganda, island retreats in Mauritius and Zanzibar, golf in West Africa, and nature and wildlife destinations in Zimbabwe and Namibia.
ABOUT ADVISORS Moelis & Company UK LLP serves as exclusive financial advisor and White & Case LLP serves legal counsel to Newmark Hotels. WongPartnership LLP serves as legal counsel to Banyan.
Banyan Tree Holdings Limited 211 Upper Bukit Timah Road, Singapore 588182 Tel: +65 68495888 | Email: [email protected] | groupbanyan.com | Reg No: 200003108H




Prompts
Click prompts to add them under the company line, click again to take one out, then copy the result into your AI chat. Shared by Asian Century Stocks and Uncovered Thai Stocks. Thank you.
ETFs Holding Banyan Tree Holdings Limited
Exchange-traded funds whose newest published daily portfolio holds one of the company's listings, largest weight first.
| ETF | Weight in ETF | Shares | Market value | As of |
|---|---|---|---|---|
| AVDS | 0.01% | 83,400 | $ 23.889K | Nov 16, 2026 |
| DFAX | 0.00% | 205,300 | $ 56.629K | Nov 12, 2026 |
| DISV | 0.00% | 44,300 | $ 12.22K | Nov 12, 2026 |
| DXIV | 0.00% | 2,100 | $ 579.25 | Nov 12, 2026 |
| DFIS | 0.00% | 22,200 | $ 6,123.54 | Nov 12, 2026 |
| DFIC | 0.00% | 600 | $ 165.50 | Nov 12, 2026 |
| DFAI | 0.00% | 300 | $ 82.75 | Nov 12, 2026 |
| AVDV | 0.00% | 39,500 | $ 11.315K | Nov 16, 2026 |