Report for Q3 2026 Highlights • Order intake was SEK 23.2 (17.1) billion, an increase of 36 p ercent. The organic increase was 33 percent. • Cash flow from operating activities amounted to SEK 3.4 (2.2) billion. • Net sales increased by 8 percent…
Report for
Q3 2026
Highlights
• Order intake was SEK 23.2 (17.1) billion, an increase
of 36 p
ercent. The organic increase was 33 percent.
• Cash flow from operating activities amounted to
SEK 3.4 (2.2) billion.
• Net sales increased by 8 percent to SEK 18.6 (17.2)
billion, with an organic increase of 6 percent.
• Earnings per share was SEK 5.40 (5.53).
• Adjusted EBITA increased by 6 percent to SEK 3.4
(3.2) billion, c
orresponding to a margin of 18.1 (18.4)
percent.
Summary
SEK millions
Order intake***
Net sales
Adjusted EBITA*
- adjusted EBITA margin*
Result after financial items
Net income for the period
Earnings per share (SEK)
Cash flow from operating activities
Return on capital employed*
Net debt**/ EBITDA* ratio
Q3
2026
2025
Total
change
Organic
change
Jan-Sep
2026
2025
Total
change
Organic
change
23,233
17,068
36%
18,596
17,244
8%
33%
63,080
51,297
23%
22%
6%
52,632
50,528
4%
3,364
3,180
5%
6%
9,322
9,097
2%
18.1%
3,050
18.4%
-2%
17.7%
18.0%
-2%
2,967
3%
8,329
8,333
2,262
0%
2,303
-2%
6,218
6,331
-2%
5.40
5.53
-2%
14.91
15.22
-2%
3,373
2,206
53%
7,023
5,770
22%
20.9%
24.2%
0.94
1.11
- Alternative performance measures.
** Net debt including lease liabilities.
*** Restated, refer to Note 1.
Alfa Laval Q3 2026
1
Comment from Tom Erixon
President and CEO
Outlook for the fourth quarter
“We expect demand in the fourth quarter to be somewhat lower
compared to the third quarter.”
Earlier published outlook (July 21, 2026):
“We expect demand in the third quarter to be somewhat lower
compared to the second quarter.”
”Demand was strong in the third quarter 2026 across most of Alfa
Laval´s end-markets. Following a strong second quarter, order
intake amounted to SEK 23.2 billion in the third quarter, again a
new record level. The order book increased significantly with a good
mix and now amounts to almost SEK 60 billion.
Both the data center and shipbuilding markets were exceptionally
strong. The data center order intake is now approaching SEK 7-8
billion in yearly pace. The US continues to account for the main
volumes, but growth is increasingly visible in China. The long-term
demand forecast for data centers is somewhat uncertain, but the
current demand level appears stable for the next two years. With
high freight rates and longer shipping routes, the contracting of new
vessels is on historic high levels and will in 2026 end significantly
above 3,000 ships. A part of the contracting converted into order
intake in the quarter, especially in the cargo pumping application.
Order intake for other product groups will be well supported during
the next few quarters. The demand trends in the Food & Pharma
Division also remained positive with biofuel orders amounting to
SEK 750 million in the quarter. Together with strong growth in the
transactional business, order intake grew by 16 percent compared
to last year.
The current growth rate for the group, 23 percent for the first 9
months of 2026, clearly supports the SEK 100 billion target for
2030. Further capacity additions are needed and the capex guidance for 2027 and 2028 is increased to approximately SEK 4 billion
per year. The main capex projects will be in the Energy Division. All
capacity additions will be located within the existing footprint.
The EBITA-margin was stable at just above 18 percent, with the three
divisions at the expected levels. The mix in the order book may well
support a stable margin development short-term, despite a decreasing share of Service as part of the mix. In the quarter, Service grew as
expected in the Energy and Food & Pharma Divisions. The Service
business in the Ocean Division was flat, to a degree impacted by an
increasing share of sanctioned ships that are out of our scope, and
high utilization rates of the remaining fleet.
The operating cash flow was solid in the quarter at SEK 3.4 billion,
53 percent above last year. Apart from funding, the dividend and
capex program, the group´s capacity for acquisitions remains
important. During 2026 two acquisitions in China have been completed, the second one in October. As many of the flagship projects
related to the decarbonization of energy systems are executed in
China, our market position and capabilities in the Chinese market is
a priority.
Market conditions globally are likely to remain favorable in the shortterm. After two record quarters, the demand in the fourth quarter is
still expected to be somewhat lower than the third quarter.”
Tom Erixon,
President and CEO
Alfa Laval Q3 2026
2
Financial overview
Order bridge
Order intake
BnSEK quarter
BnSEK 12 months
25
100
20
80
15
60
10
40
5
20
0
Q4
Q1
Q2
2023
Q3
Q4
Q1
Q2
2024
Order intake per quarter
Q3
Q4
2025
Q1
Q2
Q3
SEK million/%
2025
Organic
Structural
Currency
Total
2026
Q3
Jan-Sep
17,068
51,297
32.9%
22.4%
1.2%
4.0%
2.0%
-3.5%
36.1%
23.0%
23,233
63,080
0
2026
Order intake rolling 12 months
Order intake was SEK 23,233 (17,068) million in the third quarter and
SEK 63,080 (51,297) million in the first nine months 2026.
Order intake from Service constituted 23.7 (30.8) percent of the Group’s
total order intake during the third quarter and 26.0 (31.8) percent during the
first nine months 2026.
Order bridge Service
SEK million/%
2025
Organic
Structural
Currency
Total
2026
Q3
Jan-Sep
5,249
16,294
6.0%
3.7%
0.1%
0.7%
-1.3%
-3.7%
4.8%
0.8%
5,502
16,423
Order book
BnSEK
Sep 30
70
60
59.5
52.1
50.9
50
40
37.1
34.5
41.7
30
20
10
0
15.0
16.3
17.8
2024
2025
2026
For delivery next year or later
Sales bridge
SEK million/%
2025
Organic
Structural
Currency
Total
2026
Q3
Jan-Sep
17,244
50,528
5.8%
4.5%
0.9%
2.8%
1.1%
-3.1%
7.8%
4.2%
18,596
52,632
For delivery during rest of current year
The order book was SEK 59.5 billion at September 30, 2026, compared to
SEK 48.3 billion, at year-end 2025. SEK 17.8 billion of this is scheduled for
invoicing this year. The current order book supports a continued good invoicing
level and the order book is assessed to be in line with current input cost levels.
Net sales
Net sales was SEK 18,596 (17,244) million for the third quarter and SEK
52,632 (50,528) million for the first nine months 2026.
Net sales relating to Service constituted 29.2 (30.1) percent of the Group’s
total net sales in the third quarter and 29.5 (30.9) percent in the first nine
months 2026.
Sales bridge Service
SEK million/%
2025
Organic
Structural
Currency
Total
2026
Q3
Jan-Sep
5,189
15,636
6.0%
2.0%
0.1%
0.7%
-1.3%
-3.5%
4.7%
-0.8%
5,433
15,513
Organic: Change excluding structural changes and currency impacts.
Structural: Acquisition/divestment of businesses. Further details are available on page 15.
Alfa Laval Q3 2026
3
Income analysis
SEK million
Net sales
Cost of goods sold
Gross profit
Add back amortization step-up values
Adjusted gross
profit*
Income bridge
Q3
2026
2025
Jan-Sep
2026
2025
18,596
17,244
52,632
-11,794
-10,887
6,802
6,357
Jan-Dec
2025
Last 12
months
50,528
69,674
71,778
-33,076
-31,794
-44,476
-45,758
19,556
18,734
25,198
26,020
194
169
544
405
585
723
6,995
6,526
20,099
19,140
25,783
26,743
37.6%
37.8%
38.2%
37.9%
37.0%
37.3%
Expenses
- in % of net sales
Adjusted EBITDA*
- adjusted EBITDA
margin*
-3,079
-2,835
-9,171
-8,630
-11,531
-12,073
16.6%
16.4%
17.4%
17.1%
16.5%
16.8%
3,917
3,691
10,928
10,510
14,252
14,670
21.1%
21.4%
20.8%
20.8%
20.5%
20.4%
Depreciation
Adjusted EBITA*
-553
-511
-1,606
-1,413
-1,918
-2,110
3,364
3,180
9,322
9,097
12,334
12,560
18.1%
18.4%
17.7%
18.0%
17.7%
17.5%
-194
-169
-544
-405
-585
-723
3,170
3,011
8,778
8,692
11,749
11,837
Amortization step-up
values
Operating income
SEK million
Adjusted EBITA 2025
Volume
Mix
Costs
Currency
Adjusted EBITA 2026
Q3
Jan-Sep
3,180
9,097
431
1,383
-74
-31
-257
-939
84
-188
3,364
9,322
Net sales
BnSEK
%
25
50
20
40
15
30
10
20
5
10
- Alternative performance measures.
Net sales for the third quarter reached SEK 18,596 (17,244) million, representing a 7.8 percent year-over-year increase. Sequentially, net sales grew by 2.6
percent, both comparatives showing an increase of delivery capacity from
manufacturing units. Brazed & Fusion Bonded Heat Exchangers, Gasketed
Plate Heat Exchangers and the transactional business in Food & Pharma
Division account for a substantial part of the growth in the quarter. The proportion of Service sales in the third quarter at 29.2 (30.1) percent represents
a decrease of -0.9 percentage points compared to the same period last year
as the proportion of capital sales increases. For the first nine months, the net
sales amounted to SEK 52,632 (50,528) million, a growth of 4.2 percent.
The third quarter yielded an adjusted EBITA of SEK 3,364 (3,180) million,
marking a 5.8 percent increase over the prior year. The adjusted EBITA margin
stood at 18.1 (18.4) percent. Additionally, the adjusted gross margin was 37.6
(37.8) percent; supported by favorable factory and engineering results, positive purchase price variances, and a good mix of transactional sales including
service. For the first nine months, the adjusted EBITA was SEK 9,322 (9,097)
million with an adjusted EBITA margin of 17.7 (18.0) percent.
For the third quarter, the Energy division reported an adjusted EBITA margin
of 18.1 (16.6) percent. Adjusted EBITA grew compared to last year, driven by
sales growth across all business units. The result was also positively impacted
by a high utilization of factory capacity and good execution of the order book.
Costs increased following investments in further capacity expansion and R&D,
while the mix had a slightly positive effect and currency was neutral. The
adjusted EBITA margin in the Food & Pharma Division decreased year-overyear to 15.5 (16.1) percent. Positive mix, driven by an increase in the transactional business, and currency effects could not fully compensate a lower
invoicing. In the Ocean Division, the adjusted EBITA margin decreased to 21.3
(23.5) percent. Good factory load and a positive currency effect could not fully
offset lower invoicing and an unfavorable mix. Overall costs were stable,
reflecting a continued high level of activity.
0
Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3
2023
2024
Net sales
2025
0
2026
Adjusted gross margin in %
Adjusted EBITA
BnSEK
%
4
24
3
18
2
12
1
6
0
Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3
2023
2024
Adjusted EBITA
2025
0
2026
Adjusted EBITA margin in %
Alfa Laval Q3 2026
4
Operating income increased by 5.3 percent, rising to SEK 3,170
(3,011) million compared to the same quarter last year. For the first
nine months it showed a slight increase and ended at SEK 8,778
(8,692) million.
Sales and administration expenses were SEK -2,941 (-2,657)
million during the third quarter, corresponding to 15.8 (15.4) percent of
net sales. For the first nine months, sales and administration expenses
were SEK -8,519 (-7,958) million, corresponding to 16.2 (15.7) percent of net sales. Sales and administration expenses increased by
10.7 percent during the third quarter and by 7.0 percent during the first
nine months compared to the corresponding periods last year.
Research and development expenses were SEK -460 (-427)
million during the third quarter, corresponding to 2.5 (2.5) percent
of net sales. For the first nine months research and development
expenses were SEK -1,380 (-1,255) million, corresponding to 2.6
(2.5) percent of net sales. The costs for research and development
increased with 7.7 percent during the third quarter and increased
by 10.0 percent during the first nine months compared to the corresponding periods last year.
Earnings per share in the quarter amounted to SEK 5.40 (5.53) and
SEK 14.91 (15.22) for the first nine months. The corresponding figure
excluding amortization of step-up values and corresponding tax,
was SEK 15.91 (15.97) for the first nine months.
Taxes
The tax on the result after financial items was SEK -788 (-664)
million in the third quarter and SEK –2,111 (-2,002) million in the first
nine months 2026. The tax rate for the Group was 26 (22) percent
in the quarter and 25 (24) percent year to date which is within the
guidance range of 24-26 percent.
Cash flow
Cash flow from operating activities was SEK 3,373 (2,206) million
in the quarter and SEK 7,023 (5,770) million in the first nine months.
The operational cash surplus was slightly stronger compared to the
same periods last year both for the quarter and for the first nine
months. Working capital remained stable in the quarter and has
increased compared to last year for the first nine months, mainly
due to higher invoicing levels and high project business activity.
Depreciation and amortization was SEK -747 (-679) million in the
quarter and SEK -2,150 (-1,818) million in the first nine months
2026. Depreciation, excluding allocated step-up values, was SEK
-553 (-511) million in the quarter and SEK -1,606 (-1,413) million in
the first nine months 2026.
A minor acquisition was made in the third quarter and the total cash
flow due to acquisitions amounted to SEK -34 (-8,785) million in
the quarter and SEK -599 (-9,314) million for the first nine months.
Last year’s third quarter was impacted by the Fives acquisition.
Please refer to note 9 for details about the acquisitions.
Cash flow from financing activities amounted to SEK -473 (3,979)
million in the quarter and SEK -4,698 (4,530) million for the first
nine months. Dividends to shareholders of SEK -3,720 (-3,513) million was paid out in the second quarter. The net reduction in the loan
portfolio was SEK -328 (4,472) million in the third quarter and SEK
-324 (8,736) million for the first nine months. Last year’s third quarter was impacted by an increase in loans for the funding of the Fives
acquisition. Please refer to note 8 for details about borrowings and
net debt.
Total cash flow in the quarter was SEK 2,061 (-3,115) million and
SEK -587 (-833) million for the first nine months, arriving at a cash
balance at the end of the period of SEK 6,855 (6,192) million.
Key figures
Return on capital employed1)
Return on equity2)
Equity/assets ratio3)
Net debt/EBITDA ratio1) 5)
Debt/equity ratio1)
Number of employees4)
Sep 30
2026
2025
Dec 31
2025
20.9%
24.2%
23.9%
17.9%
20.2%
19.6%
44.9%
42.6%
44.6%
0.94
1.11
0.92
0.28
0.36
0.30
25,010
23,568
23,671
-
Alternative performance measure.
-
Net income in relation to average equity, calculated on 12 months’ revolving basis, expressed in
percent.
-
Equity in relation to total assets at the end of the period, expressed in percent.
-
FTE’s at the end of the period.
-
Net debt including lease liabilities.
Alfa Laval Q3 2026
5
Energy
Division
Highlights
• Order intake increased by 41 percent to SEK 7.7 (5.5) billion, with an organic
increase of 30 percent.
• Net sales increased by 33 percent to SEK 6.7 (5.0) billion, with an organic
increase of 24 percent.
Order intake by business unit, Jan–Sep 2026
• Adjusted EBITA of SEK 1,216 (832) million, corresponding to a margin of
18.1 (16.6) percent.
SEK million
Order intake
Order book¹)
Net sales
Operating income
Adjusted EBITA²) ³)
Adj. EBITA margin⁴)
Depreciation
Amortization
Investments⁵)
Assets¹)
Liabilities¹)
Employees¹)
Q3
2026
2025
Jan-Sep
2026
2025
7,697
5,479
21,719
16,855
12,205
6,708
5,026
1,131
8%
Jan-Dec
2025
Last 12
months
14,957
21,101
27,863
16,855
12,205
12,299
16,855
17,859
14,413
20,250
23,696
774
2,857
2,414
3,288
3,731
1,216
832
3,082
2,489
3,435
4,028
18.1%
16.6%
17.3%
17.3%
17.0%
17.0%
-185
-149
-531
-384
-524
-671
-85
-58
-224
-75
-147
-296
370
101
806
728
992
1,070
38,878
30,079
38,878
30,079
29,731
38,878
13,074
7,606
13,074
7,606
7,163
13,074
7,860
6,825
7,860
6,825
6,826
7,860
16 %
29 %
21 %
26 %
Gasketed Plate Heat Exchangers
Brazed & Fusion Bonded Heat Exchangers
Welded & Circular Technologies
Energy Division Multibrands
Cryogenic Technologies
-
At end of period.
-
Excluding items affecting comparability.
-
Alternative performance measure.
-
Adjusted EBITA/net sales.
-
Excluding new leases.
Order intake split, Jan–Sep 2026
23% 77%
Quarterly development
Service
BnSEK
%
8
24
7
21
6
18
5
15
4
12
3
9
2
6
1
0
3
Q4
Q1
Q2
2024
Order intake
Q3
Q4
2025
Net sales
Q1
Q2
2026
Adjusted EBITA margin
Q3
0
Capital Sales
Order intake by end-market, Jan–Sep 2026
Light Industry & Tech
HVAC & Ref
Fossil Base Fuels & Power
Process Industry
Clean Fuels, Power
& Chemicals
Other
% of Total
YTD 26/25
34%
125%
21%
10%
20%
25%
15%
6%
6%
37%
4%
–
Alfa Laval Q3 2026
6
Q3 comments
The Energy Division reported an increase in order intake compared to the
same quarter last year. The growth in data centers and semi-conductors
continued, led by North America and Asia. The heat pump market continued
to recover and the demand in Air Conditioning remained at a high level. The
project business performed well in the quarter, with larger projects secured in
clean energy and gas production. The Service business grew compared to the
same quarter last year, with high demand for both spare parts and value-
added services. The investment programs are progressing according to plan
and will secure additional capacity to meet the growing demand from
customers.
Order bridge
SEK million/%
2025
Organic
Structural
Currency
Total
2026
Q3
Jan-Sep
5,479
14,957
30.3%
30.2%
8.2%
19.0%
2.0%
-3.9%
40.5%
45.2%
7,697
21,719
Net sales in the Energy Division increased compared to the same quarter last
year. Due to the strong order intake, the order book increased in the quarter
and is well above the same quarter last year.
Adjusted EBITA grew compared to last year, driven by sales growth across all
business units. The result was also positively impacted by a high utilization
of factory capacity and good execution of the order book. Costs increased
following investments in further capacity expansion and R&D. The mix was
slightly positive. Currency had a neutral effect on the result.
Sales bridge
SEK million/%
2025
Organic
Structural
Currency
Total
2026
Q3
Jan-Sep
5,026
14,413
23.9%
13.0%
17.8%
14.8%
-8.2%
-3.9%
33.4%
23.9%
6,708
17,859
Income bridge
SEK million
Adjusted EBITA 2025
Volume
Mix
Costs
Currency
Adjusted EBITA 2026
Q3
Jan-Sep
832
2,489
593
1,561
35
-302
-243
-561
-1
-105
1,216
3,082
Product case
Building on Alfa Laval’s proven semi-welded technology, trusted across industries for decades, the new T25-BW and TS25-BW are designed for demanding high-pressure applications requiring exceptional thermal efficiency, a
compact footprint and full serviceability. Ideal for energy transition, energy
efficiency, and heavy industry applications, they deliver efficient and reliable
performance in industrial heat pumps, energy storage, carbon capture, heat
recovery and demanding process industry duties. With industry-leading pressure capabilities and a highly efficient semi-welded design, the T25-BW and
TS25-BW help maximize performance while minimizing lifecycle costs.
Alfa Laval Q3 2026
7
Food &
Pharma
Division
Highlights
• Order intake increased by 16 percent to SEK 7.1 (6.1) billion, with an organic
increase of 19 percent.
Order intake by business unit, Jan–Sep 2026
13 %
• Net sales decreased by -4 percent to SEK 6.3 (6.5) billion, with a slight
organic decrease of -0.1 percent.
• Adjusted EBITA of SEK 968 (1,043) million, corresponding to a margin of
15.5 (16.1) percent.
SEK million
Order intake
Order book¹)
Net sales
Operating income
Adjusted EBITA²) ³)
Adj. EBITA margin⁴)
Depreciation
Amortization
Investments⁵)
Assets¹)
Liabilities¹)
Employees¹)
Q3
2026
2025
Jan-Sep
2026
2025
20 %
Jan-Dec
2025
Last 12
months
7,057
6,098
20,929
18,984
24,872
26,817
15,806
14,224
15,806
14,224
12,719
15,806
6,255
6,483
17,494
18,550
25,635
24,579
913
985
2,481
2,665
3,650
3,466
968
1,043
2,644
2,841
3,882
3,685
15.5%
16.1%
15.1%
15.3%
15.1%
15.0%
-109
-110
-302
-324
-435
-413
-55
-58
-163
-176
-232
-219
84
127
208
297
434
345
25,954
21,861
25,954
21,861
20,968
25,954
13,314
8,631
13,314
8,631
8,191
13,314
8,689
8,433
8,689
8,433
8,499
8,689
31 %
10 %
26 %
Hygenic Fluid Handling
Process Engineering Solutions
Food & Pharma Division Multibrands
Separation Technologies
Water, Industrial Flow & Heat Transfer
-
At end of period.
-
Excluding items affecting comparability.
Order intake split, Jan–Sep 2026
- Alternative performance measure.
- Adjusted EBITA/net sales.
25% 75%
- Excluding new leases.
Service
Quarterly development
BnSEK
%
8
24
7
21
6
18
5
15
4
12
3
9
2
6
1
3
0
Q4
Q1
Q2
2024
Order intake
Q3
Q4
2025
Net sales
Q1
Q2
2026
Adjusted EBITA margin
Q3
0
Capital Sales
Order intake by end-market, Jan–Sep 2026
Dairy
Prep. Food & Beverage
Oils & Fats
Biofuels
Waste & Water
Pharma & Biotech
Brewery
Protein
Starch, Sugar & Sweeteners
Other
% of Total
YTD 26/25
22%
15%
19%
12%
16%
-8%
15%
173%
8%
1%
6%
-1%
4%
8%
4%
-34%
2%
-30%
4%
-41%
Alfa Laval Q3 2026
8
Q3 comments
The Food & Pharma Division reported good order intake in the quarter, well
above same quarter last year. The growth was driven by a positive development in both the transactional business and the project business.
The activity level in the project business improved compared to last year. The
increased demand in the biofuel sector seen earlier in the year continued in the
quarter with some important large order wins in the European biofuel sector.
Brewery also developed positively, driven by higher activity in the Asian market.
The transactional business continued to develop well with good demand growth
across most industry sectors and where especially Dairy and Prep. Food &
Beverage continued to grow at a high pace. Geographically, the growth is well
spread across regions and the main markets in USA, China and India all continued to report double-digit growth.
Net sales decreased somewhat compared to the same quarter last year. The
growth in the transactional business and in Service did not fully offset the effect
from lower invoicing within the project business.
Adjusted EBITA decreased compared to the same period last year. Positive
mix, driven by an increase in the transactional business, and currency effects
could not fully compensate a lower invoicing.
Order bridge
SEK million/%
2025
Organic
Structural
Currency
Total
2026
Q3
Jan-Sep
6,098
18,984
19.0%
18.3%
-3.6%
-3.6%
0.4%
-4.5%
15.7%
10.2%
7,057
20,929
Q3
Jan-Sep
6,483
18,550
Sales bridge
SEK million/%
2025
Organic
Structural
Currency
Total
2026
-0.1%
1.9%
-7.9%
-3.9%
4.6%
-3.6%
-3.5%
-5.7%
6,255
17,494
Income bridge
SEK million
Adjusted EBITA 2025
Volume
Mix
Costs
Currency
Adjusted EBITA 2026
Q3
Jan-Sep
1,043
2,841
-93
-152
16
111
-4
-44
6
-112
968
2,644
Product case
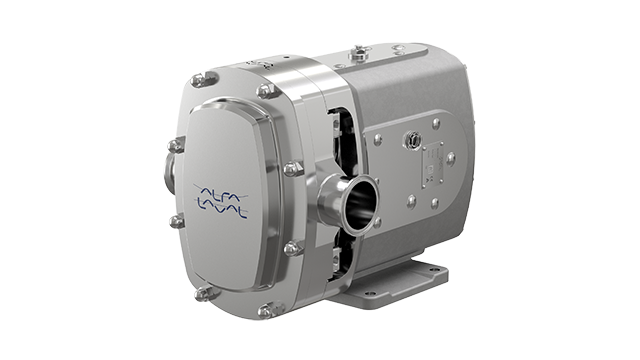
Building on its position as the market leader in rotary lobe pumps, Alfa Laval
has introduced the MaxiLobe® and MaxiLobe® UltraPure ranges to boost
efficiency, extend operating range and increase uptime in hygienic and
high-purity applications. High volumetric efficiency and a broad performance
envelope enable smaller, more energy-efficient pumps to deliver the same duty
at lower speeds, minimizing shear while supporting product quality and yield.
More precise sizing helps reduce capital costs.
Compatibility with all legacy SRU and most SX and SX UltraPure pumps
enables upgrades and higher flow without increasing footprint. Under defined
conditions, MaxiLobe delivers at least 5% higher flow than equivalent SRU
models. Robust gearboxes, excellent cleanability and front-loading seals
extend service intervals, reduce product losses, and minimize lifecycle costs.
Enhanced certifications and traceability support demanding food, beverage,
personal care, pharmaceutical and biotech applications.
Alfa Laval Q3 2026
9
Ocean
Division
Highlights
• Order intake increased by 53 percent to SEK 8.4 (5.5) billion, with an
organic increase of 53 percent.
• Net sales decreased by -4 percent to SEK 5.5 (5.7) billion, with an organic
decrease of -4 percent.
Order intake by business unit, Jan–Sep 2026
• Adjusted EBITA of SEK 1,169 (1,349) million, corresponding to a margin of
21.3 (23.5) percent.
SEK million
Order intake
Order book1)
Net sales
Operating income
Adjusted EBITA2),3)
Adj. EBITA margin4)
Depreciation
Amortization
Investments5)
Assets1)
Liabilities1)
Employees1)
Q3
2026
2025
Jan-Sep
2026
2025
Jan-Dec
2025
Last 12
months
8,398
5,491
20,101
17,355
22,614
25,360
26,613
24,435
26,613
24,435
23,241
26,613
5,481
5,735
16,824
17,565
23,790
23,049
1,116
1,297
3,678
3,904
5,232
5,006
1,169
1,349
3,831
4,055
5,433
5,209
21.3%
23.5%
22.8%
23,1%
22.8%
22.6%
-97
-81
-284
-247
-337
-374
-53
-52
-153
-151
-201
-203
223
184
437
351
548
634
35,077
30,170
35,077
30,170
28,398
35,077
14,201
10,209
14,201
10,209
9,587
14,201
6,226
6,619
6,226
6,619
6,658
6,226
5%
4% 1%
6%
45 %
39 %
Pumping Systems
Marine Solutions
Ocean Growth & Partnerships
Digital Solutions
Ballast Water Treatment
Ocean Multibrands
-
At end of period.
-
Excluding items affecting comparability.
-
Alternative performance measure.
-
Adjusted EBITA/net sales.
-
Excluding new leases.
Order intake split, Jan–Sep 2026
30% 70%
Quarterly development
BnSEK
%
9
27
8
24
7
21
6
18
5
15
4
12
3
9
2
6
1
3
0
0
Q4
Q1
Q2
2024
Order intake
Q3
Q4
2025
Net sales
Q1
Q2
Q3
Service
Capital Sales
Order intake by end-market, Jan–Sep 2026
% of Total
Ship Building & Shipping
Offshore
Engine Power
Other
YTD 26/25
75%
26%
11%
-22%
5%
25%
9%
4%
2026
Adjusted EBITA margin
Alfa Laval Q3 2026
10
Q3 comments
The Ocean Division reported higher order intake compared to same quarter
last year, driven by exceptionally strong activity in the shipping market.
Demand was positive across all business units, and strong in most
applications.
Within shipbuilding and shipping, orders were driven primarily by tankers, bulk
carriers and containerships. The gas carrier segment saw moderate activity.
Offshore order intake was also higher than in the corresponding quarter last
year, supported by growing energy needs and a continued focus on energy
security. Service demand remained stable compared with the same quarter
last year.
The execution of the substantial orderbook is progressing according to plan.
Net sales were somewhat lower compared to the same quarter last year,
mainly due to lower invoicing from project orders and the Service business.
Adjusted EBITA decreased compared with the same period last year. Good
factory load and a positive currency effect could not fully offset a lower invoicing and an unfavorable mix. Overall costs were stable, reflecting a continued
high level of activity.
Order bridge
SEK million/%
2025
Organic
Structural
Currency
Total
2026
Q3
Jan-Sep
5,491
17,355
53.4%
21.1%
-3.0%
-3.2%
2.6%
-2.1%
52.9%
15.8%
8,398
20,101
Sales bridge
SEK million/%
2025
Organic
Structural
Currency
Total
2026
Q3
Jan-Sep
5,735
17,565
-4.5%
-0.4%
-6.5%
-2.4%
6.6%
-1.5%
-4.4%
-4.2%
5,481
16,824
Income bridge
SEK million
Adjusted EBITA 2025
Volume
Mix
Costs
Currency
Adjusted EBITA 2026
Q3
Jan-Sep
1,349
4,055
-163
-195
-7
170
-69
-226
60
27
1,169
3,831
Product case
Alfa Laval has launched “Hukka-5”, the next-generation exhaust gas steam
boiler designed to enhance waste heat recovery on cruise vessels and passenger
ferries. Its revolutionary inverted, downward natural circulation design enables
efficient recovery of exhaust gas waste heat while minimizing equipment footprint. By capturing and reusing exhaust gas waste heat, the innovative boiler
helps operators significantly reduce fuel consumption and CO₂ emissions,
supporting both environmental targets and operational efficiency.
Alfa Laval Q3 2026
11
Other
Other covers corporate overhead and non-core businesses.
SEK million
Order intake
Order book1)
Net sales
Operating income
Adjusted EBITA2) 3)
Depreciation
Amortization
Investments4)
Assets1)
Liabilities1)
Employees1)
Q3
2026
2025
Jan-Sep
2026
2025
Jan-Dec
2025
Last 12
months
82
–
331
–
–
331
192
–
192
–
–
192
152
–
455
–
–
455
10
-44
-238
-291
-420
-367
11
-43
-235
-288
-416
-363
-175
-171
-503
-458
-623
-668
-1
-1
-3
-3
-4
-4
141
133
909
480
686
1,115
155
163
155
163
161
155
37
268
37
268
209
37
2,236
1,691
2,236
1,691
1,688
2,236
-
At end of period.
-
Excluding items affecting comparability.
-
Alternative performance measure.
-
Excluding new leases.
Alfa Laval Q3 2026
12
Sustainability
Case studies
Clear markings improve hand safety
At the core of improving Alfa Laval’s safety performance, it is the small steps
taken every day that make the biggest difference. This quarter new visual
markings have been added to the plate pack handling scissors at the Fontanil
factory.
The colour-coded markings clearly show where operators should and should
not place their hands. Green identifies safe hand positions, while red highlights
areas to avoid. This simple, practical improvement reduces the risk of hand
injuries and demonstrates how clear visual guidance can make everyday tasks
safer.
Energy efficiency in own operations
Operational emissions, Scope 1 and 2, are directly within Alfa Laval’s control
to achieve net zero emissions and the company places strong emphasis on
continuously reducing energy consumption across its sites.
Two examples are:
• At the San Bonifacio factory, energy performance improved by standardizing
the set-up of some furnaces cooling system, resulting in an annual energy
saving of 89,400 kWh.
• At the Fontanil factory, new drying equipment for Compablocs shortened
the furnace drying duration. A win-win situation where improved quality and
lower energy consumption resulted in an annual saving of 45,559 kWh.
Every single action count on the path to net zero.
Alfa Laval Q3 2026
13
Quarterly follow up
Energy
Energy efficiency in Q3 2026 improved by 5.8% compared to Q3 2025.
Energy efficiency is measured as energy intensity, defined as total energy
consumption relative to net sales (energy consumption/net sales).
In Q3 2026, the total energy consumption in MWh exceeded that of Q3 2025,
driven primarily by an increased electricity usage within one of Alfa Laval’s
high-intensity Business Units.
Carbon emissions
Scope 1 and Scope 2 emissions decreased in the third quarter of 2026 compared with the same period in 2025. The reduction was primarily driven by
increased use of renewable energy sources and improved electrification of
processes.
Health and safety
A total of 17 Lost Time Injuries (LTIs) were reported in Q3 2026. Following
corrections to reporting errors, the Q1 total decreased to 27, while the Q2 total
increased to 30. This brought the year-to-date total to 74 LTIs. The Group Lost
Time Injury Frequency Rate (LTIFR) for the last 12 months decreased to 2.03
and the LTIFR for Q3 was 1.38.
Incidents during the quarter continued to include a high proportion related to
both routine and non-routine work activities. Non-injury events with the potential to cause harm, particularly those related to lifting operations, were also
reported. Work continues on a roadmap to address these trends, including
stronger governance and accountability.
Energy: consumption in relation to net sales
MWh per million SEK in net sales
8
6
4
2
0
Q4
Q1
Q2
Q3
Q4
Q1
2025
2024
Q2
Q3
2026
Energy consumption per quarter
Energy consumption rolling 12 months
Carbon emissions
Tons CO₂e
quarter
Tons CO₂e
12 months
30
10
25
8
20
6
15
4
10
2
5
0
Q4
Q1
Q2
Q3
Q4
Q1
2025
2024
Q2
Q3
2026
Scope 1
FY
FY
0
2026 2027
Scope 2
Emissions 12 months
Target, full year 2026
Target
Target, full year 2027
Health and safety: Lost Time Injury Frequency Rate
LTIFR
3
2
1
0
Q4 Q1
2024
Q2 Q3
2025
Q4
Q1
Q2 Q3
2026
LTIFR per quarter
LTIFR rolling 12 months
Target
Target full year 2026
2026
LTIFR = Number of lost time injuries in time period * 1,000,000
/ Worked hours in the period
Alfa Laval Q3 2026
14
General information
Owners and shares
Parent company
Alfa Laval AB (publ) is the parent company of the Alfa Laval Group.
The company does not sell goods or services to external customers.
Owners and legal structure
Alfa Laval AB had 77,294 (61,638) shareholders on September 30,
2026. The largest owner is Winder Holding AG, Switzerland, who
owns 29.5 (29.5) percent. Next to the largest owner, there are nine
institutional investors with ownership in the range of 6.3 to 1.7 percent. These ten largest shareholders owned 57.7 (61.4) percent.
Nomination Committee for the Annual General Meeting 2027
The Nomination Committee for the Annual General Meeting 2027
has now been appointed by the largest shareholders of Alfa Laval
AB and consists of the following members:
Jörn Rausing – Winder Holding
Daniel Kristiansson – Alecta Tjänstepension Ömsesidigt
Lennart Francke – Swedbank Robur Fonder
Patricia Hedelius – AMF Tjänstepension och Fonder
Javiera Ragnartz – SEB Asset Management
In addition, Dennis Jönsson, Chairman of the Board of Alfa Laval
AB, will be part of the Nomination Committee.
The Annual General Meeting of Alfa Laval AB will be held in Lund,
Sweden, on April 21, 2027, at 4:00 p.m. (CEST).
Shareholders who wish to submit proposals for the Nomination
Committee in preparation of the Annual General Meeting can turn
to the Chairman of the Board of Alfa Laval AB, Dennis Jönsson or to
the other shareholder representatives. Contact can also be made
directly via e-mail to: [email protected]
Acquisitions of businesses
On January 14, 2026, Alfa Laval acquired 72 percent of a heat
exchanger manufacturing company in China. The company is
included in the Energy division and will operate under its own name
as an independent channel and has a minor impact on the group.
On July 31, 2026, acquired 100 percent of a Service company in
Canada. The company has a minor impact on the group and is
included in the Energy Division.
Please refer to note 9 for more information about the acquisitions.
the conflict in the Middle East, and other geo-political tensions, the
price development of metals, inflationary pressures, the interest rate
development and volatile fluctuations in major currencies. It is the
company’s opinion that the description of risks made in the Annual
Report for 2025 is still correct.
Russia’s war on Ukraine
The ongoing conflict has resulted in that Alfa Laval has ceased all
commercial activities in Russia. Alfa Laval’s assessment is that the
longer-term implications of the war are of such a magnitude that the
company in 2022 provided for the entire closure of operations.
Sanctions
The current geopolitical environment has resulted in several sanction packages imposed on several countries where conflicts are
ongoing. Alfa Laval follows and enforces all sanctions imposed by
the European Union as well as all US and other sanctions that are
applicable. The significantly increased amount of sanctioned entities together with the sophisticated circumvention attempts, make
the assurance work more demanding.
Asbestos-related lawsuits
The Alfa Laval Group was as of September 30, 2026 named as a
co-defendant in a total of 307 asbestos-related lawsuits with a total
of approximately 307 plaintiffs. Alfa Laval strongly believes the
claims against the Group are without merit and intends to vigorously
contest each lawsuit.
Based on current information and Alfa Laval’s understanding of
these lawsuits, Alfa Laval continues to believe that these lawsuits
will not have a material adverse effect on the Group’s financial condition or results of operation.
Implication of tariffs
The dynamics and development of global trade is uncertain with
background of the ongoing implementation of trade tariffs and
reciprocal escalations in response. Alfa Laval is monitoring the situation closely to ensure appropriate measures are taken to handle
commercial exposures, supply chain disruptions and guide further
actions.
Other
Changes in operating segments
During 2025, Alfa Laval made a strategic review of its abilities and
position as a global technology leader to better serve customers
worldwide and support further growth. As of 1 January 2026, two
of three divisions were renamed to better reflect strategic priorities:
• The former Marine Division was named Ocean Division.
Risks and uncertainties
• The former Food & Water Division was named Food & Pharma
Division.
Material factors of risk and uncertainty
The main factors of risk and uncertainty facing the Group concern
the business cycle, the consequences of Russia’s war on Ukraine,
• The Energy Division has retained its name.
Alfa Laval Q3 2026
15
As part of the new operating model implemented during the first
quarter of 2026, Multibrand companies are reported in their main
divisional belonging to reflect technological and industrial alignment.
Entities that are considered non-core and not related to respective
division’s core business are reported in the Other division. These
changes, where applicable, are reflected as structural changes in the
divisional bridges for order intake and net sales, when comparing
with 2025.
Significant events after the reporting period
In October, Alfa Laval acquired 74% of the Chinese heat exchanger
manufacturer Hangzhou Shenshi Energy Conservative Technology
Co. The initial purchase price excl. contingent consideration
amounted to SEK 1,717 million. The company has an annual net sales
of appr. SEK 700 million and 650 employees. The acquisition will be
consolidated from the fourth quarter and included in the Energy
division.
Alternative performance measures
Alfa Laval follows the Guidelines on Alternative Performance
Measures issued by ESMA, European Securities and Markets
Authority. For definitions of the alternative performance measures,
refer to the Annual Report 2025, page 152-153.
Signature of the President and CEO
Lund, October 27, 2026
Alfa Laval AB (publ)
Tom Erixon
President and CEO
The interim report has been reviewed by the company’s auditors.
Alfa Laval Q3 2026
16
Financial statements
Consolidated income statement, condensed
SEK million
Net sales
Cost of goods sold
Gross profit
Note
2-5
Sales costs
Administration costs
Research and development costs
Other operating income and costs
Share of result in joint ventures
Operating income
Financial net
Result after financial items
Taxes
Net income for the period
Net income for the period attributable to:
Owners of the parent
Non-controlling interests
Earnings per share attributable to the owners of the parent, SEK*
Average number of shares*
6
Q3
2026
2025
Jan-Sep
2026
2025
Jan-Dec
2025
Last
12 months
18,596
17,244
52,632
50,528
69,674
71,778
-11,794
-10,887
-33,076
-31,794
-44,476
-45,758
6,802
6,357
19,556
18,734
25,198
26,020
-1,451
-1,686
-4,981
-5,101
-6,877
-6,755
-1,490
-971
-3,538
-2,857
-3,873
-4,554
-460
-427
-1,380
-1,255
-1,738
-1,863
-215
-277
-820
-802
-960
-979
-16
16
-59
-28
-2
-32
3,170
3,011
8,778
8,692
11,749
11,837
-120
-44
-449
-359
-551
-642
3,050
2,967
8,329
8,333
11,198
11,195
-788
-664
-2,111
-2,002
-2,875
-2,985
2,262
2,303
6,218
6,331
8,322
8,210
2,233
2,288
6,161
6,292
8,272
8,141
28
15
57
39
50
68
5.40
5.53
14.91
15.22
20.01
19.70
413,326,315
413,326,315
413,326,315
413,326,315
413,326,315
413,326,315
- Before and after dilution.
Consolidated statement of comprehensive income, condensed
Q3
SEK million
Net income for the period
Other comprehensive income
Items that will not be reclassified to profit or loss:
Revaluations of defined benefit obligations
Market valuation of external shares
Deferred tax on other comprehensive income
Total
Jan-Sep
Jan-Dec
2025
Last
12 months
6,331
8,322
8,210
–
-90
-110
-21
-9
-133
-138
-14
–
12
13
2
-9
-211
-235
-33
2026
2025
2026
2025
2,262
2,303
6,218
–
-15
–
-43
–
4
–
-54
Items that may subsequently be reclassified to profit or loss:
Cash flow hedges
Translation difference
Deferred tax on other comprehensive income
Total
85
2
256
-363
-440
179
1,886
-289
3,755
-2,228
-3,075
2,908
Total other comprehensive income
1,886
-343
3,745
-2,439
-3,310
2,874
Total comprehensive income for the period
4,148
1,960
9,963
3,892
5,012
11,084
Total comprehensive income for the period attributable to:
Owners of the parent
Non-controlling interests
4,102
1,945
9,852
3,899
5,009
10,963
46
15
111
-7
3
121
67
38
-295
1,265
1,300
-261
1,734
-329
3,794
-3,129
-3,934
2,989
Alfa Laval Q3 2026
17
Consolidated balance sheet, condensed
SEK million
ASSETS
Non-current assets
Intangible assets and goodwill
Property, plant and equipment and right-of-use assets
Other non-current assets
Total non-current assets
Current assets
Inventories
Accounts receivable
Other receivables
Derivative assets
Current deposits
Cash and cash equivalents
Assets held for sale
Total current assets
Note
7
7
TOTAL ASSETS
EQUITY AND LIABILITIES
Equity
Owners of the parent
Non-controlling interests
Total equity
Non-current liabilities
Liabilities to credit institutions
Lease liabilities
Pension liability
Deferred tax liabilities
Other non-current liabilities
Total non-current liabilities
8
2025
Dec 31
2025
39,280
37,475
36,445
17,714
15,344
15,856
3,158
2,401
2,895
60,152
55,221
55,196
19,295
15,728
15,548
11,979
10,536
9,949
12,221
11,285
9,084
555
603
551
355
424
707
6,855
6,192
7,124
21
25
1
51,281
44,793
42,965
111,433
100,014
98,161
49,541
42,298
43,409
478
335
344
50,018
42,633
43,753
10,912
9,812
9,626
2,894
2,646
3,333
1,039
908
984
3,474
3,296
3,458
757
549
642
19,077
17,212
18,043
6,558
8,781
7,590
659
898
462
6,400
5,640
5,444
11,630
10,197
9,004
2,453
2,157
1,936
405
246
133
14,231
12,251
11,795
42,337
40,170
36,365
Total liabilities
61,414
57,381
54,408
TOTAL EQUITY AND LIABILITIES
111,433
100,014
98,161
Current liabilities
Liabilities to credit institutions
Lease liabilities
Accounts payable
Advances from customers
Provisions
Derivative liabilities
Other liabilities
Total current liabilities
7
Sep 30
2026
8
7
Alfa Laval Q3 2026
18
Consolidated statement of changes in equity, condensed
SEK million
Opening balance January 1, 2025
Net income for the period
Other comprehensive income
Total comprehensive income for the period
Dividends
Total transactions with owners
Closing balance September 30, 2025
Opening balance January 1, 2026
Net income for the period
Other comprehensive income
Total comprehensive income for the period
Change of non-controlling interests
Dividends
Total transactions with owners
Closing balance September 30, 2026
Equity attributable to
Non-controlling
Owners of the parent
interests
Total equity
41,912
369
6,292
39
42,282
6,331
-2,393
-46
-2,439
3,899
-7
3,892
-3,513
-28
-3,541
-3,513
-28
-3,541
42,298
335
42,633
43,409
344
43,753
6,161
57
6,218
3,691
54
3,745
9,852
111
9,963
–
58
58
-3,720
-36
-3,756
-3,720
22
-3,698
49,541
478
50,018
Alfa Laval Q3 2026
19
Consolidated statement of cash flows, condensed
SEK million
Operating activities
Operating income
Adjustment for depreciation and amortization
Adjustment for provisions
Adjustment for other non-cash items
Operational cash surplus
Taxes paid
Cash flow from operating activities before changes in
working capital
Note
Changes in working capital:
Increase(-)/decrease(+) of receivables
Increase(-)/decrease(+) of inventories
Increase(+)/decrease(-) of liabilities
Increase(-)/decrease(+) in working capital
Cash flow from operating activities
Investing activities
Investments in fixed assets (Capex)
Divestment of fixed assets
Acquisition of businesses
Divestment of businesses
Cash flow from investing activities
Financing activities
Paid and received interests
Dividends received
Dividends to owners of the parent
Dividends to non-controlling interests
Amortizations of lease liabilities
Increase of loans
Amortization of loans
Other financing cash flows
Cash flow from financing activities
Cash flow for the period
Cash at the beginning of the period
Translation difference in cash
Cash at the end of the period
Free cash flow per share (SEK) *
Capex in relation to net sales
Average number of shares
9
Q3
2026
2025
Jan-Sep
2026
2025
Jan-Dec
2025
Last
12 months
3,170
3,011
8,778
8,692
11,749
11,837
747
679
2,150
1,818
2,503
2,833
24
171
402
398
391
395
-3
3
5
52
-84
-131
3,938
3,864
11,335
10,960
14,559
14,934
-679
-551
-2,669
-1,990
-2,719
-3,398
3,259
3,313
8,666
8,970
11,840
11,536
111
-1,424
-2,640
-3,877
-2,203
-966
-701
-508
-2,340
-1,130
-1,226
-2,436
704
825
3,337
1,807
755
2,285
114
-1,107
-1,643
-3,200
-2,674
-1,117
3,373
2,206
7,023
5,770
9,166
10,419
-819
-545
-2,360
-1,855
-2,660
-3,165
14
26
47
32
155
170
-34
-8,785
-599
-9,314
-9,412
-697
–
4
–
4
4
–
-839
-9,300
-2,912
-11,133
-11,913
-3,692
-189
-79
-474
-238
-357
-593
–
–
–
3
9
6
–
–
-3,720
-3,513
-3,513
-3,720
–
–
-36
-28
-28
-36
-130
-87
-447
-383
-503
-567
2,094
4,503
5,898
8,796
8,796
5,898
-2,421
-31
-6,221
-60
-1,081
-7,242
175
-327
302
-47
-408
-59
-473
3,979
-4,698
4,530
2,915
-6,313
2,061
-3,115
-587
-833
168
414
4,628
9,342
7,124
7,369
7,369
6,192
165
-35
317
-344
-413
248
6,855
6,192
6,855
6,192
7,124
6,855
17.96
6.21
4.08
11.40
9.55
16.12
4.4%
3.2%
4.5%
3.7%
3.8%
4.4%
413,326,315
413,326,315
413,326,315
413,326,315
413,326,315
413,326,315
- Free cash flow is an alternative performance measure. It is the sum of cash flows from operating activities, investments and divestments of fixed assets.
Alfa Laval Q3 2026
20
Parent company income statement, condensed
SEK million
Administration costs
Other operating income and costs
Operating income
Financial net
Result after financial items
Q3
2026
2025
Jan-Sep
2026
2025
Jan-Dec
2025
-17
-4
-3
-16
-13
5
2
9
7
-1
1
0
-7
-7
-18
294
550
332
616
1,285
295
550
325
609
1,267
–
Change of tax allocation reserve
Group contributions
Result before tax
–
–
–
-10
–
–
–
–
1,835
295
550
325
609
3,093
Taxes
Net income for the period
-3
-4
-9
-16
-385
292
546
316
593
2,707
Sep 30
2026
2025
Dec 31
2025
4,669
4,669
4,669
2,795
3,914
6,509
308
472
4
The parent company income statement also constitutes its statement of comprehensive income.
Parent company balance sheet, condensed
SEK million
ASSETS
Non-current assets
Shares in group companies
Current assets
Receivables on group companies
Other receivables
Cash and cash equivalents
Total current assets
3
3
3
3,106
4,389
6,517
TOTAL ASSETS
7,775
9,058
11,186
EQUITY AND LIABILITIES
Equity
Restricted equity
Unrestricted equity
Total equity
2,387
2,387
2,387
3,363
4,654
6,768
5,750
7,040
9,154
Untaxed reserves
Tax allocation reserves
1,996
1,986
1,996
24
26
24
4
3
1
–
2
10
28
31
36
7,775
9,058
11,186
Current liabilities
Liabilities to group companies
Accounts payable
Other liabilities
Total current liabilities
TOTAL EQUITY AND LIABILITIES
Alfa Laval Q3 2026
21
Notes
Note 1. Accounting policies
The interim report is prepared in accordance with IAS 34 Interim
Financial Reporting and the Swedish Annual Accounts Act. The
accounting and valuation policies of the parent company comply
with the Swedish Annual Accounts Act and the recommendation
RFR 2 Accounting for legal entities, issued by the Council for Financial Reporting in Sweden.
Full descriptions of accounting policies are provided in the Annual
Report 2025. These policies have been consistently applied as in
the Annual Report; however, starting from Q1 2026, certain changes
have been implemented in the interim report. Structurally, the table
Reconciliation between Divisions and Group total has been
relocated to Note 2. In addition, the note Bridge cash flow restatement, which was included in all interim reports for the financial year
2025, has been removed, as the cash flow is now fully comparable
between periods presented.
From Q1 2026, there is a change in the presentation of Order intake.
Order intake now focuses solely on new orders for the period, with
cancellations and currency effects no longer included. Instead,
these items are described as part of the change in the Order book
between periods. Apart from this presentation change, the same
accounting policies and measurement methods as in the latest
annual financial statements continue to be applied.
Alfa Laval is currently evaluating how the, by IASB, issued IFRS 18
Presentation and Disclosures in Financial Statements standard will
impact the financial report. The standard will be applicable for
reporting periods starting from January 1, 2027, and onwards.
The totals in the tables and the calculated totals may not always
match due to rounding differences on individual lines. Each subtotal,
and line item, corresponds to its original source and rounding, which
can lead to discrepancies with reported totals that aggregate the
exact figures before rounding.
Alfa Laval Q3 2026
22
Note 2. Segment reporting
Order intake
Last 12 months
2026
2025
2024
SEK million
Q3
Q2
Q1
Q4
Q3
Q2
Q1
Q4
Energy
7,697
7,776
6,246
6,144
5,479
4,566
4,912
5,160
Food & Pharma
7,057
7,725
6,148
5,888
6,098
6,450
6,436
6,633
Ocean
8,398
6,607
5,096
5,259
5,491
5,427
6,437
6,317
Other
82
127
123
–
–
–
–
–
Total
23,233 22,235 17,612 17,290 17,068 16,444 17,785 18,111
32 %
33 %
Order book
Sep 30, 2026
2026
SEK million
Q3
Q2
Q1
Q4
Energy
16,855 15,531 13,692 12,299
Food & Pharma 15,806 14,822 12,873 12,719
Ocean
26,613 22,931 21,879 23,241
Other
192
263
298
–
Total
59,466 53,546 48,741 48,259
2025
Q3
Q2
Q1
2024
Q4
12,205
10,249
10,579
10,590
14,224
15,067
15,216
14,926
24,435
25,001
26,267
26,803
–
–
–
–
45 %
28 %
50,864 50,317 52,062 52,319
27 %
Net sales
Last 12 months
2026
2025
2024
SEK million
Q3
Q2
Q1
Q4
Q3
Q2
Q1
Q4
Energy
6,708
6,180
4,971
5,837
5,026
4,601
4,786
5,186
Food & Pharma
6,255
5,943
5,295
7,085
6,483
6,162
5,905
7,114
Ocean
5,481
5,845
5,497
6,224
5,735
6,056
5,775
6,010
Other
152
148
155
–
–
–
–
–
Total
18,596 18,117 15,919 19,146 17,244 16,819 16,465 18,311
32 %
33 %
35 %
Adjusted EBITA
SEK million
Energy
Food & Pharma
Ocean
Other
Total
35 %
Last 12 months
Q3
2026
Q2
Q1
Q4
2025
Q3
Q2
Q1
2024
Q4
1,216
995
871
946
832
796
861
923
968
871
805
1,041
1,043
904
894
1,008
1,169
1,455
1,207
1,378
1,349
1,448
1,259
1,104
11
-250
5
-128
-43
-146
-99
-111
3,364
3,071
2,887
3,237
3,180
3,001
2,916
2,922
40 %
31 %
29 %
Energy
Food & Pharma
Adjusted EBITA margin
%
Energy
Food & Pharma
Ocean
Total
Ocean
Q3
2026
Q2
2025
Q3
Q1
Q4
Q2
Q1
2024
Q4
18.1%
16.1%
17.5%
16.2%
16.6%
17.3%
18.0%
17.8%
15.5%
14.7%
15.2%
14.7%
16.1%
14.7%
15.1%
14.2%
21.3%
24.9%
22.0%
22.1%
23.5%
23.9%
21.8%
18.4%
18.1%
17.0%
18.1%
16.9%
18.4%
17.8%
17.7%
16.0%
Alfa Laval Q3 2026
23
Reconciliation between Divisions and Group total
Q3
2026
2025
Jan-Sep
2026
2025
Jan-Dec
2025
Last
12 months
3,364
3,180
9,322
9,097
12,334
12,560
-194
-169
-544
-405
-585
-723
3,170
3,011
8,778
8,692
11,749
11,837
SEK million
Divisions
Adjusted EBITA
Amortization
Operating income
Financial net
Result after financial items
-120
-44
-449
-359
-551
-642
3,050
2,967
8,329
8,333
11,198
11,195
100,063
82,273
100,063
82,273
79,258
100,063
11,369
17,741
11,369
17,741
18,903
11,369
111,433
100,014
111,433
100,014
98,161
111,433
40,626
26,714
40,626
26,714
25,150
40,626
20,788
30,667
20,788
30,667
29,258
20,788
61,414
57,381
61,414
57,381
54,408
61,414
Assets*
Total for divisions
Corporate**
Group total
Liabilities*
Total for divisions
Corporate**
Group total
- At the end of the period.
** Corporate refers to items in the consolidated balance sheet that are interest bearing or related to taxes.
Alfa Laval Q3 2026
24
Note 3. Order intake
Large orders by business unit (orders exceeding EUR 5 million)
SEK million
Cryogenic Technologies
Gasketed Plate Heat Exchangers
Welded & Circular Technologies
Energy
Hygienic Fluid Handling
Process Engineering Solutions
Separation Technologies
Water, Industrial Flow & Heat Transfer
Food & Pharma
Q3
2026
2025
–
232
283
141
538
279
821
652
404
–
1,199
94
94
127
–
62
1,697
282
Marine Solutions
Ocean Growth & Partnerships
Pumping Systems
Ocean
669
367
1,063
636
Total
3,580
1,571
191
57
203
211
Order intake for the 10 largest markets
China
United States
Nordic
South East Asia
Adriatic
India
Japan
Mid Europe
Korea, South
France
0
1
2
3
4
5
6
7
8
9
10
11
12
13
14
15
16
17
18
SEK billion
Last 12 months
Jan–Dec 2025
Alfa Laval Q3 2026
25
Order intake by region
13
8
5
22
42
10
30
10
24
7
50
6
-4
37
13
7
Share of total, YTD, %
YTD 2026 vs 2025, %*
Northern Europe
The order intake in the region increased double-digit compared to
the same quarter last year. Energy grew driven by HVAC & Ref and
Conventional Power. Food & Pharma grew in Oils & Fats and Dairy.
Ocean grew in Offshore and Shipbuilding & Shipping. Service grew
in Energy and Food & Pharma, while flat in Ocean.
Latin America
The order intake in the region increased double-digit compared to
the same quarter last year. Energy grew driven by Light industry &
Tech and Refinery. Food & Pharma grew in Dairy and Oils & Fats.
Ocean declined in Industrial boilers and Shipbuilding & Shipping.
Service reported growth in Energy.
Central and Eastern Europe
The order intake in the region increased double-digit compared
to the same quarter last year. Energy grew driven by Light industry
& Tech and HVAC & Ref. Food & Pharma declined in Dairy and
Protein. Ocean grew driven by Engine Power. Service reported
growth in Food & Pharma, while flat in Energy and Ocean.
Northeast Asia
The order intake in the region increased double-digit compared to
the same quarter last year. Energy grew in Light industry & Tech
and HVAC & Ref. Food & Pharma grew in Prep. Food & Beverages
and Dairy. Ocean grew in Shipbuilding & Shipping and Offshore.
Service grew in Energy and Food & Pharma, while flat in Ocean.
Southern Europe
The order intake in the region increased double-digit compared to
the same quarter last year. Energy declined in Clean Fuels, Power
& Chemicals and Process Industry. Food & Pharma grew, driven by
Biofuels. Ocean declined in Offshore. Service grew in Energy and
Food & Pharma.
Southeast Asia and Oceania
The order intake in the region was flat compared to the same quarter last year. Energy grew driven by Light industry & Tech. Food &
Pharma declined in Dairy and Prep. Food & Beverage. Ocean
declined in Offshore and Ship Building & Shipping. Service grew
in Food & Pharma.
North America
The order intake in the region increased double-digit compared to
the same quarter last year. Energy grew, driven by Light industry &
Tech and Refinery. Food & Pharma grew, driven by Prep. Food &
Beverage and Pharma & Biotech. Ocean declined in Offshore.
Service grew in all three divisions.
India, Middle East and Africa
The order intake in the region declined compared to the same quarter last year. Energy declined in Process Industry. Food & Pharma
grew in Brewery and Pharma & Biotech. Ocean declined in Offshore. Service grew in Food & Pharma, while flat in Energy.
Alfa Laval Q3 2026
26
Note 4. Net sales by geographical area
SEK million
To customers in:
Sweden
Other EU
Other Europe
United states
Other North America
Latin America
Africa
China
South Korea
Other Asia
Oceania
Total
Q3
2026
2025
Jan-Sep
2026
2025
Jan-Dec
2025
Last
12 months
326
352
1,024
970
1,447
1,500
3,645
4,015
10,621
11,144
15,387
14,864
1,222
1,168
3,529
3,397
4,812
4,944
3,557
2,808
9,080
8,374
11,321
12,026
329
325
1,006
1,186
1,548
1,368
1,006
959
2,985
2,920
3,971
4,036
355
305
1,101
911
1,306
1,497
4,030
3,436
11,551
9,498
13,231
15,284
794
1,060
2,514
3,656
4,702
3,559
3,116
2,612
8,593
7,887
11,185
11,891
216
204
628
585
765
808
18,596
17,244
52,632
50,528
69,674
71,778
2025
Jan-Dec
2025
Last
12 months
Net sales are reported by country on the basis of invoicing address, which is normally the same as the delivery address.
Note 5. Net sales by product*
SEK million
Separation
Heat transfer
Fluid handling
Other
Total
Q3
2026
2025
Jan-Sep
2026
2,959
2,916
8,470
8,497
12,028
12,001
8,613
7,161
23,126
20,759
28,767
31,134
4,878
4,627
14,786
13,637
18,529
19,678
2,147
2,539
6,250
7,635
10,350
8,965
18,596
17,244
52,632
50,528
69,674
71,778
- The split of own products and services within separation, heat transfer and fluid handling is a reflection of Alfa Laval’s three main technologies. Other consists of own products and services outside of these
three areas. This category also includes purchased products that complement Alfa Laval’s product range. Services are split to all categories and cover all sorts of service and service agreements excluding
spare parts.
Information about major customers
Alfa Laval does not have any customer that accounts for 10 percent or more of net sales.
Note 6. Financial net
SEK million
Net of interests
- of which interest expense on financing loans
Dividends and other financial income and cost
Net of exchange rate differences
Financial net
Q3
2026
2025
Jan-Sep
2026
2025
Jan-Dec
2025
Last
12 months
-141
-134
-425
-274
-404
-555
-124
-118
-338
-229
-337
-446
-15
1
-13
12
22
-3
36
89
-12
-97
-169
-85
-120
-44
-449
-359
-551
-642
Sep 30
2026
2025
Dec 31
2025
Note 7. Financial instruments
Financial assets and liabilities at fair value
SEK million
Financial assets
Shares in other companies
Bonds and other securities
Derivative assets
Financial liabilities
Derivative liabilities
Valuation hierarchy level*
1 and 2
53
21
12
1
159
206
206
2
804
810
717
2
527
320
193
- Valuation hierarchy level 1 is according to quoted prices in active markets for identical assets and liabilities. Valuation hierarchy level 2 is out of directly or indirectly observable market data outside level 1.
Valuation hierarchy level 3 is out of unobservable market data.
Alfa Laval Q3 2026
27
Note 8. Net debt
Borrowings and net debt
Sep 30
2026
SEK million
Credit institutions
Swedish Export Credit
Term loans
Commercial papers
Corporate bonds
Total liabilities to credit institutions
Cash and current deposits
Net debt excluding lease liabilities*
Lease liabilities
Net debt including lease liabilities*
2025
Dec 31
2025
250
66
38
2,266
2,206
2,160
3,988
4,418
4,324
1,199
–
–
9,768
11,903
10,695
17,471
18,593
17,216
-7,211
-6,616
-7,832
10,260
11,977
9,384
3,553
3,544
3,795
13,813
15,521
13,179
Available
amount
Utilized
amount
Falls due
700
0
2028
100
100
2027
100
100
2028
4,000
1,200
2026
1,000
1,000
2028
500
500
2029
500
500
2029
300
300
2029
600
600
2030
400
400
2030
300
300
2031
176
176
2027
176
176
2027
- Alternative performance measure.
Borrowings specification
Million
Revolving credit facility*
Swedish Export Credit
Swedish Export Credit
Commercial papers
Corporate bond
Corporate bond
Corporate bond
Corporate bond
Corporate bond
Corporate bond
Corporate bond
Term loan
Term loan
Currency
EUR
EUR
EUR
SEK
SEK
SEK
SEK
EUR
SEK
SEK
EUR
EUR
EUR
*The revolving credit facility can be increased with EUR 200 million.
During the third quarter, the most significant event were Alfa Laval’s
repayment of SEK 2,150 million in c
ommercial papers and the issuance of SEK 2,000 million under the EMTN program, with SEK
1,000 million maturing in 2028, and SEK 1,000 million maturing in
2029.
Alfa Laval Q3 2026
28
Note 9. Acquisitions
Jan–Sep
SEK million
Intangible assets
Property, plant and equipment and right-of-use assets
Other non-current assets
Inventories
Accounts receivable
Other receivables
Cash and cash equivalents
Provisions
Deferred tax
Liabilities to credit institutions
Lease liability
Advance payments
Accounts payable
Other liabilities
Acquired net assets
Equity attributable to non-controlling interests*
2026
2025
265
3,415
96
364
2
29
60
357
185
262
3
369
12
343
-11
-16
-39
-863
-7
-3
–
-47
–
-317
-33
-275
-59
-284
474
3,334
70
–
Goodwill
250
6,456
Purchase price
Retained part of purchase price
Cash in acquired businesses
Total effect on cash flow
-659
-9,791
98
133
12
343
-549
-9,314
The acquisition analyses for acquisitions made during the last 12 months are preliminary and will be concluded within one year of the acquisition date.
- Equity attributable to non-controlling interests is valued according to the proportion of the acquired net assets.
On January 14, 2026, Alfa Laval acquired 72 percent of a heat
exchanger manufacturing company in China. The purchase price
amounted to SEK 619 million, out of which SEK 527 million was paid
in cash and SEK 92 million retained until further conditions related
to investments in non-current assets are met. Transaction costs
amounted to SEK 17 million and are included in administration costs.
The company employs 313 people and has an annual net sales of
appr. SEK 400 million. The company will operate under its own
name as an independent channel and has a minor impact on the
group. The acquisition is included in the Energy Division.
On July 31, 2026, acquired 100 percent of a Service company in
Canada. The purchase price amounted to SEK 40 million, out of
which SEK 34 million was paid in cash and SEK 6 million retained.
Transaction costs amounted to SEK 2 million and are included in
administration costs. The company employs 15 people and has an
annual net sales of appr. SEK 33 million. The company has a minor
impact on the group and is included in the Energy Division.
The step-up values for intangible assets are amortized over 10-15
years. Goodwill is primarily relating to synergy effects expected after
the acquisition. Fair values are preliminary and may be subject to
change.
In Q1 2026, Alfa Laval made an additional investment of SEK 50
million in Industrikraft i Sverige AB. As Alfa Laval’s ownership remains
minor, and without significant influence, the company is not consolidated. The investment is reported under Other non-current assets.
In October, Alfa Laval acquired 74% of the Chinese heat exchanger
manufacturer Hangzhou Shenshi Energy Conservative Technology
Co. The initial purchase price excl. contingent consideration
amounted to SEK 1,717 million. The company has an annual net
sales of appr. SEK 700 million and 650 employees. The acquisition
will be consolidated from the fourth quarter and included in the
Energy division.
Alfa Laval Q3 2026
29
Review report
Alfa Laval AB, corporate identity number 556587-8054
Introduction
We have reviewed the condensed interim report for Alfa Laval AB
(publ) as at September 30, 2026 and for the nine months period
then ended. The Board of Directors and the Managing Director are
responsible for the preparation and presentation of this interim
report in accordance with IAS 34 and the Swedish Annual
Accounts Act. Our responsibility is to express a conclusion on this
interim report based on our review.
Scope of review
We conducted our review in accordance with the International
Standard on Review Engagements, ISRE 2410 Review of Interim
Financial Statements Performed by the Independent Auditor of the
Entity. A review consists of making inquiries, primarily of persons
responsible for financial and accounting matters, and applying
analytical and other review procedures. A review is substantially
less in scope than an audit conducted in accordance with International Standards on Auditing and other generally accepted auditing
standards in Sweden. The procedures performed in a review do not
enable us to obtain assurance that we would become aware of all
significant matters that might be identified in an audit. Accordingly,
we do not express an audit opinion.
Alfa Laval AB (publ)
Box 73
SE-221 00 Lund
Sweden
Corporate registration number:
556587-8054
Conclusion
Based on our review, nothing has come to our attention that causes
us to believe that the interim report is not prepared, in all material
respects, in accordance with IAS 34 and the Swedish Annual
Accounts Act regarding the Group, and in accordance with the
Swedish Annual Accounts Act regarding the Parent Company.
Lund, October 27, 2026
Ernst & Young AB
Andreas Troberg
Authorized Public Accountant
Hanna Fehland
Authorized Public Accountant
Visiting address:
Rudeboksvägen 1
Tel: + 46 46 36 65 00
Website: www.alfalaval.com