Results Presentation Fiscal 2026 Third Quarter Delivering Life-changing value to Patients Commitment to Life Luis Miguel Berlanas, Father of Candela, affected by XLH Commitment to Life We remain dedicated to our mission of delivering life-changing…
Results Presentation
Fiscal 2026 Third Quarter
Delivering Life-changing value to Patients
Commitment to Life
Luis Miguel Berlanas,
Father of Candela, affected by XLH
Commitment to Life
We remain dedicated to our mission of
delivering life-changing value
to everyone battling illness,
as we continue to push the boundaries
of innovative drug discovery.
David Riley, MLD father
© Kyowa Kirin Co., Ltd.
1
Agenda
01
Q3 2026 Highlights
Chairman
Masashi Miyamoto
02
Financial Review
03
Commercial update
04
Business update
President and
Chief Executive Officer (CEO)
Abdul Mullick
Chief Medical Officer (CMO)
Yoshifumi Torii
Chief Financial Officer (CFO)
Koji Igarashi
05
R&D update
© Kyowa Kirin Co., Ltd.
2
Executive Summary: Q3 2026 Highlights
◼ Dialogue with Stakeholders
◼ Q3 Financial Results
⚫ Revenue increased by 10% and Core operating profit by 47% year on year
⚫ Core operating profit progressing steadily against the revised full-year plan (75% progress)
⚫ Potential to exceed the full-year plan, supported by favorable FX; no further revision to the earnings forecast
◼ Business Update
⚫ Agreement with U.S. Administration to Reduce Treatment Costs for Americans Through Generous Program
⚫ Orchard Updates, including current progress in MLD and pipeline
◼ R&D Update
⚫ Announced Phase 2 topline results for KHK4951 in nAMD* in September
*Neovascular age-related macular degeneration
© Kyowa Kirin Co., Ltd.
3
Dialogue with Patients
Patient and family voices are at the heart of how we create and deliver value.
XLH Day 2026
October 2-4, 2026 | Indianapolis, USA | Organizer: XLH Network
1
Listening directly to patients' voices
2
Through dialogue, we reaffirmed our mission
3
Creating life-changing value from patient voices
CEO Abdul Mullick heard directly from patients about their XLH
journeys and the difference our work is making in their lives
Through dialogue with patients and their families, we are once again
reminded of the changes our work brings to people's lives.
We continue listening, learning, and working with the patient
community to deliver life-changing value to people living with XLH.
XLH patients and their families, at XLH Day 2026 (Indianapolis, USA)
© Kyowa Kirin Co., Ltd.
4
Dialogue with Investors / Shareholders
Tokyo Research Park Tour: Dialogue with Investors and Shareholders
Event Overview
Date and Time September 10, 2026
Composition
Part 1: Presentation & Q&A / Part 2: Facility tour
Venue
Tokyo Research Park (TRP)
Theme
History of our technologies (POTELLIGENT®/REGULGENTTM)
and our research philosophy
Speakers
Takeyoshi Yamashita (CSciO), Takashi Shimada (Head of
Research), Rinpei Niwa (Head of TRP), Hikaru Miyagi (Director,
Antibody & Biologics Group, Core Research Laboratories)
Presentation Highlights
01 Research Division organization and management
Tokyo Research Park (TRP)
POTELLIGENT® Technology: Overview from a
02 Science Perspective
03 The development story of REGULGENT
04 Q&A with Kyowa Kirin Researchers
*Materials from the briefing session on the day are
posted on our company's IR website.
© Kyowa Kirin Co., Ltd.
5
Incorporating Stakeholder Voices into Management Discussions
Continuing dialogue with key stakeholders and leveraging it in management discussions to shape our business strategy
Patients
⚫ Hearing directly from patients at patient advocacy
group events and at internal management meetings
to which patients were invited
⚫ Listening to learn from people living with illness, and
committing to addressing unmet medical needs
Investors /
Shareholders
C-suite
Executive
⚫ Intensifying
discussions under the
C-Suite Executive
⚫ Shaping future
business strategy
“Key Priorities Under
the New C-Suite Executive Team”
announced Q1
⚫ Stepping up engagement with capital markets and
incorporating investor expectations and concerns
into management discussions in a timely manner
4 times*
✓ Roadshows:
✓ Global healthcare conferences:
2 times*
✓ Tour of research site (Tokyo Research Park)
✓ Roundtable with Independent Outside Directors and
Investors/Analysts: January 2027 (planned) **
*Including events scheduled within 2026
**See page 44 for details.
1
2
Employees
3
⚫ Monthly Global and Regional
Town Hall meetings
⚫ As the company undergoes
transformation, communicating
management information directly
and clearly to employees
4
Maximize the value of our
key products
Actively pursue strategic investments
with financial discipline
Establish the next-generation growth
platform focusing on priority disease areas
Drive Operational Excellence to Support Growth
6
Financial Review
© Kyowa Kirin Co., Ltd.
7
Summary of FY26 Q3 (YTD) Results
Q3 delivered revenue and profit growth, with greater confidence in achieving the full-year plan supported by favorable FX
(Billion JPY / Rounded)
FY2025
Jan-Sep
FY2026
Jan-Sep
Change
FY2026
Rev. Plans*3
Progress
Revenue
349.5
384.9
+35.5
[77%]
(+10%)
520.0
74%
Gross Profit
259.4
288.4
+29.0
[75%]
(+11%)
388.0
74%
SG&A*1
116.5
123.7
+7.2
163.0
76%
R&D Exp.
76.8
67.7
-9.1
95.0
71%
Core Operating Profit*2
66.1
97.0
+30.9
[25%]
(+47%)
130.0
75%
Profit
32.6
51.7
+19.1
[9%]
[13%]
(+59%)
75.0
69%
[Overseas Ratio]
[Gross Profit Margin]
[SG&A Ratio]
[R&D Ratio]
[Core OP Margin]
[Profit to Revenue Ratio]
[73%]
[74%]
[33%]
[22%]
[19%]
[32%]
[18%]
*1 Excludes amortization of intangible assets (sales rights amortization)
*2 Core operating profit: GP - SG&A (excl. intangible amortization) - R&D - Company-defined non-recurring items
*3 Unchanged from the revised plans announced on May 7, 2026.
© Kyowa Kirin Co., Ltd.
[77%]
[75%]
(+6%)
[31%]
(-12%)
[18%]
[25%]
[14%]
Foreign Exchange Assumptions
◼ FY2025Q3 Actual: ¥149 / USD
◼ FY2026Q3 Actual: ¥159 / USD
◼ FY2026 Rev. Plan: ¥150 / USD
•
There has been no change in the foreign exchange
assumptions from those used in the FY2026 plans announced
on February 9, 2026.
8
YoY Analysis Revenue by Region
Revenue Up on North America, Tech Income and FX, Despite Lapse of EMEA Prior-Year Brand Transfer Income
・Rocatinlimab upfront deferred revenue
FY25 6.1 bn FY26 9.7 bn(+3.6 bn)
Temporary
factors
・EMEA established products brand transfer
FY25 6.1 bn FY26 ー bn(- 6.1 bn)
(Billion JPY)
349.5
FY25 Jan-Sep
-6.0
Japan
North America
EMEA
Japan
Excl.FX
+15.7
Incl.FX
+35.5
Others
North America
+8.9
EMEA
-5.8
(excl. FX Impact +6.2)
+18.6
FX Impact
© Kyowa Kirin Co., Ltd.
Crysvita (+9%) and Poteligeo (+6%) grew, leading to a 7% revenue
increase in North America.
-5.8bn
-9%
Although EMEA revenue declined 9% due to the absence of prior-year
one-time income from the brand license transfer (6.1 bn) and lower
royalties following the JV divestment, Crysvita (+7%) and Poteligeo
(+11%) continued to grow steadily.
Others
+18.6bn
+28%
+19.8
384.9
+8.9bn
+7%
(excl. FX Impact +9.7)
(excl. FX Impact +3.9)
FY26 Jan-Sep
-6.0bn
-7%
Although Phozevel (+19%), Duvroq (+17%) and Crysvita (+14%)
grew, sales in the Japan region decreased by 7% due to the
impact of drug price revisions.
FX impact
+19.8bn
Other revenue increased by 28%, mainly due to higher techlicensing income from the one-time recognition of deferred
upfront revenue for rocatinlimab following the termination of the
Amgen development collaboration, as well as increased royalty
income from Fasenra sales.
Regional changes exclude FX impact
9
YoY Analysis Revenue by Product
Revenue up on double-digit Crysvita/Poteligeo growth and tech-licensing
・Rocatinlimab upfront deferred revenue
Temporary
FY25 6.1 bn FY26 9.7 bn (+3.6 bn)
factors
・EMEA established products brand transfer
FY25 6.1 bn FY26 - bn (-6.1 bn)
(Billion JPY)
FY25 Jan-Sep
349.5
Crysvita
Crysvita
+24.8
Poteligeo
+5.1
Libmeldy/
Lenmeldy
Tech-licensing
+24.8bn
Strong demand growth in North America (+17%) drove
growth, while EMEA (+17%) and Japan (+14%) also grew,
resulting in global revenue growth of 17%.
+5.1bn
Poteligeo total revenue grew 15%, led by North America
(+13%) and EMEA (+22%).
+17%
Poteligeo
+15%
+2.9
Incl.FX
+35.5
+16.3
Other Products
FY26 Jan-Sep
-13.5
384.9
Libmeldy/
Lenmeldy
+2.9bn
+66%
41% revenue growth driven by the one-time recognition of
Tech-licensing
deferred upfront revenue for rocatinlimab following the termination
+16.3bn of the development collaboration with Amgen and higher royalty
+41% income from Fasenra sales.
Other Products
-13.5bn
© Kyowa Kirin Co., Ltd.
The identification of eligible patients progressed steadily
and remained broadly on track with the plan.
Despite growth in Phozevel (+19%) and Duvroq (+17%), revenue
declined due to drug price revisions and product discontinuations
(Depakene, Allelock Granules) in Japan, and the absence of prioryear one-time income (6.1 bn) from the brand license transfer in
EMEA.
※Changes in revenue include the impact of foreign exchange (+19.8 billion JPY)
10
YoY Analysis Core Operating Profit*1
Core operating profit up on global products, Tech-licensing income, and reduced rocatinlimab development costs
(Billion JPY)
66.1
FY25 Jan-Sep
+12.5
Gross Profit
(excl. FX Impact +16.4)
SG&A
Excl.
FX impact
+22.4
R&D Expenses
FX Impact
Gross Profit
Incl.
FX impact
+30.9
FY26 Jan-Sep
Gross profit increased due to higher revenue.
The gross profit margin increased by 1 point from 74% to
+12.5bn 75%.
-1.6
(excl. FX Impact -5.7)
+11.4
(excl. FX Impact -2.3)
R&D Expenses
R&D expenses decreased due to the absence of rocatinlimab
development expenses, which peaked in the previous year.
+11.4bn R&D expense ratio fell by 4 points from 22% to 18%.
+8.5
97.0
*1 Core operating profit: Gross profit - selling, general and administrative expenses (excluding amortization of intangible assets) - R&D expenses - non-recurring profit and
loss as determined by the Company
© Kyowa Kirin Co., Ltd.
11
YoY Analysis Profit
Profit growth driven by higher core operating profit despite impairment losses and clinical trial closing costs related to rocatinlimab
(Billion JPY)
32.6
FY25 Jan-Sep
Core
operating profit*1
+30.9
Amortization of
intangible assets
-3.8
Equity Method
Profit
+19.1
+2.3
51.7
Increased amortization of sales rights due to the launch of KOMZIFTI
in the U.S. (November 2025)
FY2025
・JP Special Voluntary Early Retirement Program (-9.4 bn)
FY2026
・Rocatinlimab clinical trial closing costs (-20.2 bn)
and relevant impairment losses (-5.0 bn)
-10.0 bn
・Gains from the established medicines JV divestment (+4.3 bn)
Finance & Others
-10.0
Tax Expenses
© Kyowa Kirin Co., Ltd.
-3.8 bn
-0.3
Finance &
Others
FY26 Jan-Sep
Amortization of
intangible assets
Tax Expenses
+2.3 bn
The effective tax rate declined, as the gain/loss on the share transfer of
the established medicines Joint Venture is a non-taxable transaction.
Effective tax rate: FY25 Q3 32.0% → FY26 Q3 20.2%
*1 Core operating profit: Gross profit - selling, general and administrative expenses (excluding amortization of intangible assets) - R&D expenses - nonrecurring profit and loss as determined by the Company
12
Commercial Update
Coordinated Actions to Maximize Patient Access to Global Strategic Products
© Kyowa Kirin Co., Ltd.
13
Crysvita 2026 Key Actions & Q3 Topics
2026 KEY ACTIONS
2026 Q3 TOPICS
◼ NA:
Continue investments in people and operations to support patient identification, customer
education, and the evolution of patient support services.
◼ Global: YTD Sales rev. YoY, in Yen +17%, annual plan progress rate 73%
◼ NA: YTD Sales rev. YoY, in Yen +17%, in local currency +9%
Demand growth remained strong, driven by enhanced patient-finding and support programs.
Leading indicators, incl. new patient additions, stayed favorable. Q3 growth temporarily
moderated due to the reversal of Q2 pre-price-increase shipments.
◼ EMEA:
Drive growth through improved patient identification, including AI-enabled initiatives,
reinforcement of guideline-based use in pediatrics, expansion into adult patients.
◼ EMEA: YTD Sales rev. YoY, in Yen +17%, in local currency +7%
Underlying demand remained strong, driven mainly by continued patient growth, particularly
among adults.
◼ JAPAN:
Drive adult patient penetration through enhanced promotion and disease awareness
activities led by the dedicated bone metabolism unit established in October 2025.
◼ JP: YTD Sales rev. YoY, in Yen +14%
Dedicated-rep promotion and disease awareness efforts drove steady new patient additions,
led by adults, and faster uptake of the pre-filled syringe.
Sales Revenue (Billion yen)
Japan
EMEA
NA
Others
North America Sales Revenue ($M)
216.4
13.6
196.6
11.7
127.1
8.9
85.1
6.4
87.0
57.4
21.2
31.0
103.1
7.4
152.4
10.5 134.9
8.2
105.2
146.7
9.7
130.0
+17%
171.5
11.1
141.8
107.5 220.7
92.0
87.2
235.4
14.7
70.2
24.5
35.1
37.1
51.5
42.4
22Q3 FY22 23Q3 FY23 24Q3 FY24 25Q3
© Kyowa Kirin Co., Ltd.
57.5
456
22Q3
512
23Q3
575
24Q3
620
North America Demand Trend
676
Sales Revenue($M)
25Q3
26Q3
155
EMEA Sales Revenue (£M)
133
144
22Q3
23Q3
233
193
219
24Q3
25Q3
285
187
Demand (mg) 12 month MA
325
273
157
191
325
151
200
233
24Q1 24Q2 24Q3 24Q4 25Q1 25Q2 25Q3 25Q4 26Q1 26Q2 26Q3
49.7
FY25 26Q3 FY2026
Plan
26Q3
14
Poteligeo 2026 Key Actions & Q3 Topics
2026 KEY ACTIONS
2026 Q3 TOPICS
◼ Global: Support the Poteligeo franchise in MF/SS through aligned global execution and
continued use of clinical and real-world evidence to reinforce long-term value.
◼ Global: YTD Sales rev. YoY, in Yen +15%, annual plan progress rate 71%
◼ NA: Focus on identifying appropriate MF/SS patients and supporting broader and earlier
use through evidence-based communication. Continue to leverage ML & AI based
technology.
◼ EMEA: Focus on identifying appropriate MF/SS patients and supporting broader and earlier
use through evidence-based communication. Support market expansion opportunities and
reimbursement efforts. Utilize peer exchange programs and AI data to help identify patients
earlier.
Revenue (Billion yen)
Japan
EMEA
NA
Others
30.3
12.6
3.5
22Q3
17.2
EMEA Revenue (£M)
54.6
45.7
39.9
17.5
◼ EMEA: YTD Sales rev. YoY, in Yen +22%, in local currency +11%
Underlying demand remained robust, supported by accelerating evidence-based
communication and sustained patient engagement initiatives. Continued to expand
geographic reach across the region.
North America Revenue ($M)
337
24.2
◼ NA: YTD Sales rev. YoY, in Yen +13%, in local currency +6%
YTD demand remained above the prior-year level. Continued active promotion to target
institutions leveraging accumulated evidence, with ongoing focus on patient-finding through
ML/AI and advanced analytics.
21.3
29.7
21.5
15.1
5.1
4.8
6.9
FY22
23Q3
FY23
© Kyowa Kirin Co., Ltd.
38.8
33.7
29.1
21.6
25.1
6.0
7.3
24Q3
FY24
25Q3
179
38
143
40.9
33.9
8.2
169
100
28
110
8.9
FY25
26Q3
31
22
28.4
10.0
42
12.0
FY2026
Plan
22Q3
23Q3
24Q3
25Q3
26Q3
22Q3
23Q3
24Q3
25Q3
26Q3
15
KOMZIFTI 2026 Key Actions & Q3 Topics
KEY ACTIONS IN 2026
2026 Q3 TOPICS
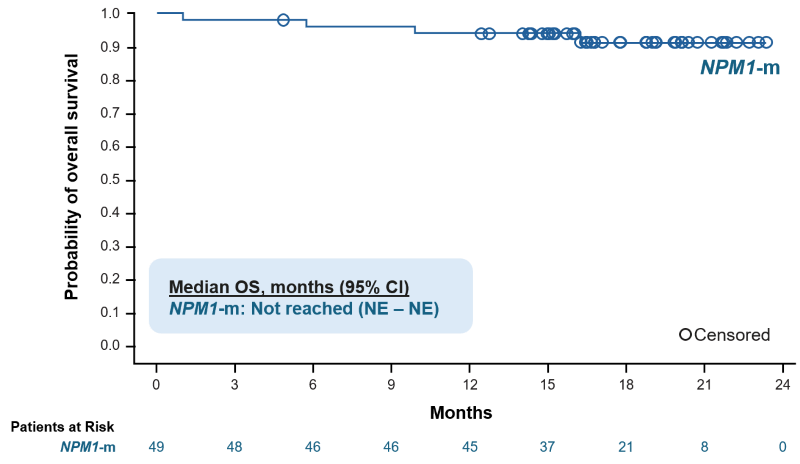
◼ KOMZIFTI’s efficacy, safety profile, and ease of use support its positioning
as a competitive option in R/R NPM1-mutated AML, with the potential for
increased market penetration over time.
◼ Commercial efforts continue to support the successful launch of KOMZIFTI
◼ KOMZIFTI is establishing a differentiated position within the menin inhibitor
class for relapsed or refractory NPM1-mutated AML
◼ We continue to engage healthcare professionals through a range of
educational and field-based activities
◼ We are strengthening the evidence base to support broader adoption in
clinical practice
◼ Multiple clinical updates are expected at ASH*, further deepening
understanding of ziftomenib's potential value
*The American Society of Hematology Annual Meeting
KOMZIFTI Product P/L Image
Kyowa Kirin P/L Image
*Net Product Revenue: refer to Kura Oncology's Q3 2026 earnings materials
(Expected by mid-November).
Unit: Billions of yen
Items
Items
FY
2025
2026
JanMar
2026
AprJun
2026
JulSep
Profit
2026
YTD
Loss
Net Product
Revenue
0.3
0.9
1.4
Net Profit / Net
Loss before Tax
(8.2)
(1.5)
(1.7)
(0.3)
(3.5)
© Kyowa Kirin Co., Ltd.
50%
50% of Net Profit / Net Loss
before Tax is recorded as
revenue (if Net Profit) or SG&A
(if Net Loss).
Unit: Billions of yen
FY2025
2026 JanMar
2026 AprJun
2026 JulSep
2026 YTD
ー
ー
ー
ー
ー
SG&A
(4.1)
(0.7)
(0.9)
(0.2)
(1.7)
Core Operating
Profit
(4.1)
(0.7)
(0.9)
(0.2)
(1.7)
Amortization of
Intangible
Assets
(0.7)
(1.1)
(1.1)
(1.2)
(3.4)
Profit before
Tax
(4.8)
(1.8)
(2.0)
(1.3)
(5.1)
Revenue
16
Business Update
© Kyowa Kirin Co., Ltd.
17
Agreement with the U.S. Government
Voluntary agreement with the U.S. government to improve access and lower the cost of medicines for Americans
Participation in the GENEROUS model
Certain medicines offered to state Medicaid patients at a
discount
Balanced pricing for new products
Applicable new products to be launched in other developed
countries with a more balanced pricing framework
Deferral of Section 232 tariffs
Agreement with the U.S. Department of Commerce to defer
Section 232 tariffs
- The detailed terms of the agreement remain confidential
News Releases (August 31, 2026, U.S. time)
Agreement with U.S. Administration to Reduce
Treatment Costs for Americans
© Kyowa Kirin Co., Ltd.
18
Orchard updates: Advancing Our Gene & Cell Therapy Platform
Gene and Cell Therapy
Portfolio Expansion
Libmeldy®/LenmeldyTM
MLD3
Newborn Screening
Europe
Libmeldy®/LenmeldyTM
Treatment Access
Europe / U.S.
⚫ Approved in 2020 and 2024,
respectively.
⚫ Qualified Treatment Centers:
9 in the U.S. and 7 in Europe
Japan
⚫
NDA1 submitted (Mar 2026)
Other regions
⚫ Saudi Arabia: MAA2 submitted
(Jan 2026)
⚫ Future filings planned in Brazil
and Canada
© Kyowa Kirin Co., Ltd.
⚫ Sweden, Norway: nationwide
screening in place
⚫ Austria: nationwide pilot ongoing
⚫ Other countries: regional or pilot
screening programs underway in
Italy, Germany, France
Revenue Growth
⚫ Revenue +66% YoY (Jan–Sep
2026)
⚫ Aim for +30 to 40% CAGR over
next three years driven by
newborn screening and
geographic expansion
10.0
U.S.
⚫ MLD added to RUSP4 (Dec 2025)
⚫ 21 states (>50% of U.S. births) with
RUSP alignment legislation
⚫ Actively screening: 3 states
⚫ Recommend add to state panel: 18
states
⚫ Outlook: expect active screening in
29 states, or 2.7 million newborns by
end of 2028
7.3
4.4
Bn yen
2025
Q3 YTD
Bn yen
2026
Q3 YTD
Bn yen
2026
Full-year
Plan
OTL-203 (MPS-IH)
⚫ Completed a meeting with the FDA in
September 2026 on clinical and
CMC plans and BLA5 submission
strategy
⚫ FDA indicated that accelerated
approval based on a surrogate
marker endpoint could be a potential
submission pathway
⚫ Currently planning for a BLA
submission in the U.S. in 2029
OTL-201 (MPS-IIIA)
⚫ PoC study is ongoing with longterm patient follow-up ongoing
⚫ Aligning with global regulatory
agencies on final design of
registrational study
- New Drug Application, 2. Market Authorization Application, 3. Metachromatic Leukodystrophy, 4. Recommended Uniform Screening Panel,
- Biologics License Application
19
R&D Update
© Kyowa Kirin Co., Ltd.
20
Development Pipeline: News Flow (1)
Product
Indication
AML (1L/Combination)
ziftomenib
Already marketed as
KOMZIFTITM
New information highlighted in orange
As of Nov 2, 2026
Event
Status
KOMET-017(P3)
Ongoing
KOMET-007(P1)Presentation at EHA
June 2026
Congress and Journal Publication
KOMET-J001 (P2, Japan)
Ongoing
AML (NPM1-m or KMT2A-r)
Orphan Drug Designation in Japan
August 2026
MPS-I (Hurler Syndrome)
Registrational Study(P3 Equivalent)
Ongoing
MLD
P3 (Japan)
NDA (Japan)
In preparation
March 2026
Achondroplasia
P3
Ongoing
infigratinib
Hypochondroplasia
P3
In preparation
KHK4951
nAMD
P2 Topline Data Announcement
September 2026
tivozanib eyedrop
DME
P2
Ongoing
OTL-201
MPS-IIIA (Sanfilippo Syndrome Type A) PoC Study (P1/2 Equivalent)
OTL-203
OTL-200
Already marketed as
Libmeldy®/Lenmeldy®
KK8398
© Kyowa Kirin Co., Ltd.
Ongoing
21
Development Pipeline: News Flow (2)
New information highlighted in orange
As of Nov 2, 2026
Product
Indication
Event
Status
KK4277
SLE, CLE
P1
Completed
KK2260
Advanced or metastatic solid tumors
P1
Ongoing
KK2269
Advanced or metastatic solid tumors
P1
Ongoing
KK2845
AML and other Hematologic Malignancies
P1
Ongoing
KK8123
XLH
P1/2
Ongoing
KK8005
XLH
P1/2 initiation
September 2026
KK3910
Essential Hypertension
P1
Ongoing
KK2223
CTCL, PTCL
P1 initiation
September 2026
KK4408
Autoimmune disease
P1/2 initiation
October 2026
© Kyowa Kirin Co., Ltd.
22
Source: Kyowa Kirin, “Topline Results of the KHK4951 Phase 2 study in
nAMD patients” disclosed on September 8, 2026.
KHK4951 Phase 2 Summary of Test Results
Achieved the company's pre-defined product profile targets
Results suggest the potential of an eye drop-centered maintenance treatment strategy
Effectiveness
Primary
Evaluation Items
Safety and
Tolerability
Secondary
Evaluation
Items
In all treatment groups,
including the low-dose
group, 65-69% of subjects
maintained their vision
within 15 letters decrease
in BCVA without any
rescue IVT1 injection at
Week 52
The “statistical
difference among
dose groups in the
proportion of patients
with a reduction of 15
or more BCVA2
between 8 and 52
weeks" was not
observed
No new safety
signals were
observed in this
study
In all groups, BCVA
and CST3 remained
stable throughout the
treatment period.
- IVT = Intravitreal; 2. Best-Corrected Visual Acuity; 3. Central Subfield Thickness
23
© Kyowa Kirin Co., Ltd.
Appendix
Financial Information
R&D
Other Updates
© Kyowa Kirin Co., Ltd.
24
Revenue of Major Items
FY2025
Jan-Sep
Product Name, etc.
(Units are billion JPY, rounded)
FY2026
Jan-Sep
YoY Change
Key Reason
FY2026
Rev. Plans*
Progress
146.7
171.5
+24.8 (+17%)
235.4
73%
Japan
9.7
11.1
+1.4 (+14%)
14.7
75%
North
America
92.0
107.5
+15.5 (+17%)
EMEA
42.4
49.7
+7.3 (+17%)
220.7
73%
Others
2.6
3.3
+0.6 (+25%)
33.7
38.8
+5.1 (+15%)
54.6
71%
Japan
1.2
1.3
+0.1 (+9%)
1.4
88%
North
America
25.1
28.4
+3.3 (+13%)
40.9
69%
EMEA
7.3
8.9
+1.6 (+22%)
12.0
74%
Others
0.1
0.2
+0.1 (+142%)
0.2
93%
4.4
7.3
+2.9 (+66%)
10.0
73%
United
States
1.6
4.9
+3.3 (+203%)
4.5
108%
EMEA/
Others
2.8
2.4
-0.4 (-13%)
5.5
44%
Phozevel
Japan
5.9
7.1
+1.1 (+19%)
(Launched in February 2024)
11.6
61%
Duvroq
Japan
10.9
12.8
+1.9 (+17%)
Market Penetration
16.2
79%
G-Lasta
Japan
13.7
10.5
-3.1 (-23%)
Drug price revisions and
BS Penetration
16.2
65%
Romiplate
Japan
11.5
9.0
-2.5 (-22%)
Drug price revisions
11.4
79%
Tech-licensing
39.4
55.6
+16.3 (+41%)
74.9
74%
Benralizumab Royalty*1
25.4
31.6
+6.2 (+25%)
Fasenra growth and onetime recognition of
deferred revenue for
rocatinlimab
Crysvita
Poteligeo
Libmeldy / Lenmeldy
Market Penetration
Market Penetration
Market Penetration
(US FDA approval in March
2024)
Market Penetration
*1 Sales royalties of Fasenra sold by AstraZeneca (including our own estimates)
Kyowa Kirin
Co.,
*2©Overseas
items
areLtd.
shown after deducting discounts, etc., including foreign exchange effects. Items in the Japan region display the amount before deductions.
*The forecasts for Revenue of Major Items were not changed in the revision of the earnings forecasts announced on May 7, 2026.
25
Source: Kyowa Kirin, “Discontinuation of Clinical Trials
for Rocatinlimab,” disclosed on March 4, 2026.
Impact on Business Performance
• Short-term profit increase due to elimination of SG&A and R&D expenses related to rocatinlimab
• Certain negative profit impact expected in the medium to long term
◼ Estimated Impact on Core Operating Profit
⚫ 2026
: Approx. +¥20~30 billion
⚫ 2027
: Approx. +¥30 billion
⚫ 2028
: Approx. +¥10 billion
⚫ 2029 onwards
: Certain negative impact expected
◼ Estimated Impact on Net Income for the Current Fiscal Year
⚫ In addition to the impact on core operating profit, closing costs arising from the termination
of the clinical trials will be recorded as “other expenses”
◼ Revision of FY2026 Earnings Forecast
⚫ Currently under review; revision to the earnings forecast will be disclosed at the time of the
Q1 FY2026 earnings announcement
© Kyowa Kirin Co., Ltd.
26
Source: Kyowa Kirin, “FY2025 Financial Results
Briefing,” disclosed on Feb 9, 2026.
(Updated 2026 Plans)
Change in Core Performance Metrics from FY2026
Background
Reviewing performance management post 2021-2025 Mid-term Business Plan, we change core performance metrics
anticipating the impact of IFRS 18 "Presentation and Disclosure in Financial Statements" effective FY2027.
◼ Consolidated P/L display change (intro of 3 categories: operating, investing, financing)
→Equity method investment P&L excluded from operating profit
◼ Intro of "Management-defined Performance Metrics" footnote (audited) for investor comms
→Revisions to metrics for better comparability with global pharma, reflecting group's sustainable profitability
Details
Calculated by deducting SG&A (excl. amortization of intangible assets) and R&D from gross profit, and further excluding non-recurring
items as determined by the Company
→Compared to previous core operating profit, amortization of intangible assets (amortization of selling rights) and equity in earnings of
affiliates are excluded
2023 Actual
(Billion JPY)
2025 Actual
2026 Rev. Plans
96.8
[22%]
95.4
[19%]
103.1
119.0
Amortization of intangible assets
(sales rights)
5.6
7.6
7.6
11.0
Equity method investment P&L
0.9
3.5
0.8
0.0
Non-recurring items
-
-
-
-
101.4
[23%]
99.4
[20%]
109.8
130.0
[22%]
[25%]
Core Operating Profit [Core
Operating Profit Margin]
Excluded
2024 Actual
Core Operating Profit
©[Core
Kyowa Operating
Kirin Co., Ltd.Profit Margin]
(Current Metric)
(Revised Metric)
[21%]
[23%]
27
[Ref.] Impacts arising from the adoption of IFRS 18
“Presentation and Disclosure in Financial Statements
From the fiscal year ending December 2027, the presentation of our consolidated statement of profit or loss will be revised as
outlined below. Ahead of this change, we have updated our performance indicators starting from the fiscal year ending Dec. 2026.
Core Operating Profit: Gross profit less selling, general and administrative expenses, R&D expenses, and related non-recurring items.
Core Profit for the Year: Core operating profit less related income tax expense.
Core EPS: Core profit for the year divided by the weighted average number of shares outstanding.
Current Presentation
(through FY2025)
Current Core Metrics
(through FY2025)
Revenue
Cost of Sales
Gross Profit
SG&A
R&D Expenses
(Amortization of Intangible Assets) ※
Equity-method profit/loss
Core Operating Profit
Other Operating Income / Expenses
Finance income / costs
Finance income / costs
Profit Before Tax
Income Tax Expense
Profit for the Year
© Kyowa Kirin Co., Ltd.
New Core Metrics
(from FY2026)
(excluding non-recurring items)
Core Operating Profit
Income Tax Expenses
(Excl. other income/expenses)
Income tax expense
(Core operating profit items)
Core Profit for the Year
Core Profit for the Year
Core EPS
Core EPS
*Amortization of intangible assets (amortization of selling rights) was included in SG&A until 2025. Beginning in 2026,
it has been separately disclosed as amortization of intangible assets due to increased materiality.
IFRS 18 (from FY2027)
Revenue
Cost of Sales
Gross Profit
SG&A
R&D Expenses
Operating
Amortization of Intangible Assets
Other Operating Income / Expenses
Operating Profit
Equity-method profit/loss
Other Investment Income / Expenses
Investment
Profit Before Finance and Income Taxes
Finance
Finance income / costs
Profit Before Tax
Income Tax Expense
Profit for the Year
28
Source: Kyowa Kirin, “Kyowa Kirin Equity Story”
disclosed in June 2026.
Capital Allocation Policy (2026–2028)
While properly allocating the generated cash flow to investments for organic growth and to dividends, we will also allocate cash for future inorganic
growth with discipline.
Source
Allocation
Stable
Shareholders
Return
Operating CF Investment CF
before R&D
¥ 40 B
expenses
EMBU business
restructuring
Cash to be generated
in 2026-2028
¥ 660 B
⚫Operating CF 280
⚫ R&D expenses 380
Organic Growth
Dividend
¥ 110 B
⚫ DOE 4%+
⚫ Progressive
dividend
Strategic cash allocation for
Inorganic growth
R&D
¥ 380 B
Share
buyback will
be
considered
flexibly
⚫ Share buyback will be considered flexibly,
taking into account the status of strategic
investments, business performance, and
share price trends, with a focus on ROE
© Kyowa Kirin Co., Ltd.
Consistent Investment for
Cash on hand
CAPEX
¥ 130 B
⚫ Investment in a US biopharmaceutical
manufacturing facility and IT, DX and AI
investments
¥ 220 B
(End of FY2025)
Strategic
investment
Consider
leveraging
debt when
appropriate
⚫ Strategic investments will, in principle, be considered within the
scope of available cash on hand; however, the use of external
debt will also be considered as necessary. (Even when making
use of debt financing, we will, as a rule, maintain discipline by
keeping the net D/E ratio within 0.5x or lower.)
29
P/L Impact on EMEA established medicines portfolio
Before
Aug 2023
After
Aug 2023
2024
2025
2026
unrealized 49% of the transfer value
£ 66.4M(JPY13.1B)
Tostran until Oct
Product sales
Established portfolio
13 brands
Revenue
Tostran IP transfer
(ADVANZ PHARMA)
COGs
Cost of product sales
SG&A
SG&A costs
Equity
method
Other income
3 brands
1 brand
IP transfer
IP transfer
Sales Royalties & license fees
Disposal
proceeds
£ 62.5M (JPY 11.4B)
Royalties decrease
due to early IP transfer
Contingency
income
£8.5M (JPY 1.6B)
49% of profit for Joint Venture Collaboration, Grünenthal Meds
Share
transfer *
£38.5M (JPY7.7B)
*Incl. price adj. diff. for 3
brands transferred last year
51% of Grünenthal Meds share has transferred (Aug 1)
Gain on sales of 51% share+ gain on valuation of remaining
49% share at £80.9M (JPY 14.8B) in total
9 brands
3+1 brands
JPY 4.3 B Disposal of shares
- derivative valuation gains
Transfer of residual assets
+
Realization of unrealized
profits
- Kyowa Kirin International plc (“KKI”) transferred the remaining assets related to its established pharmaceutical business, including the IP for
9 brands (down from 13), to Grünenthal in the Q1 of FY2026. In prior periods, options held under a collaboration agreement were measured
at fair value and recognized as liabilities. Following the termination of the option agreements, the derivative liabilities were reversed and a
© Kyowa Kirin Co., Ltd.
gain on derivative remeasurement was recognized.
30
FX Info
Period Avg. FX Rate (yen)
2025
Jan-Sep
2026
Jan-Sep
YoY
2026
Rev. Plans*
USD
149
159
+10
¥150
GBP
195
213
+18
¥205
EUR
165
185
+20
¥180
FY2026 YTD Q3 FX Impact (vs FY25, billion yen)
Revenue
Core OP
USD
+12.3
+6.3
GBP
+0.5
-1.4
EUR
+5.6
+3.1
FY2026 FX Sensitivity (vs FY26 Rev. Plans, billion yen)
© Kyowa Kirin Co., Ltd.
Sensitivity
Revenue
Core OP
USD
1 yen Weaker
+1.8B
+0.6B
GBP
1 yen Weaker
+0.1B
-0.1B
EUR
1 yen Weaker
+0.4B
+0.2B
*There has been no change in the foreign exchange assumptions from those used in the FY2026 plans announced on February 9, 2026.
31
Ziftomenib Kura Oncology Collaboration
US
Dev.
◼ Kura leads Dev.
◼ Dev. costs 50/50
◼ Kura funds Dev. (~2028)
Commercial.
Ex-US
◼ Kyowa Kirin leads Dev.
◼ Kyowa Kirin sells & books sales
◼ Kura books sales
◼ 50/50 Profit Share
Sales Royalties
Supply
◼ Kyowa Kirin pays double-digit % sales royalties
◼ Kura supplies
Kyowa Kirin to pay $330M upfront, up to $1,161M milestones. Includes:
$420M near-term milestones, $228M solid tumor option, future global sales royalties.
© Kyowa Kirin Co., Ltd.
◼ Kura supplies
32
Crysvita Ultragenyx Collaboration
Economic Terms
US・Canada
Europe
Latin America
Turkey
Asia & Other
◼ Kyowa Kirin books sales
◼ 50/50 profit share for 5 years post-launch
◼ From Yr 6 (Apr 27, 2023), tiered sales royalties to Ultragenyx (mid-to-high 20s%)
◼ Kyowa Kirin books sales
◼ Sales royalties to Ultragenyx (<10%)
◼ Ultragenyx books sales
◼ Kyowa Kirin receives sales royalties (low single-digits%).
◼ Ultragenyx books sales
◼ Kyowa Kirin receives sales royalties (≤20%).
◼ Kyowa Kirin books sales
*Kyowa Kirin supplies product in all regions.
© Kyowa Kirin Co., Ltd.
33
Key Development Pipeline (1)
As of Nov 2, 2026
Planned
approval year*2
Development
status
AML
(NPM1-m or KMT2A-r, Newly Diagnosed)
TBD
P3 (Global)
★★★★
20K
Achondroplasia
TBD
P3 (Japan)
★
1 in 20K live births
Hypochondroplasia
TBD
P3 (Japan) In preparation
★
1 in 33K live births
Metachromatic Leukodystrophy
2026/2027
P3 (Japan) In preparation
★
1 in 100K live births*6
nAMD
TBD
P2 (JP/US)
★★★★★
2672K
DME
TBD
P2 (JP/US)
★★★★
2219K
OTL-203
MPS-IH (Hurler Syndrome)
2029/2030
Registrational study*5
(US, EU)
★
1 in 100K live births*6
OTL-201
MPS-IIIA (Sanfilippo syndrome type A)
TBD
Proof-of-concept study*7
★
~1 in 100K live births
Disease in development*1
ziftomenib
KK8398
infigratinib
OTL-200
KHK4951
tivozanib eyedrop
Market size*3
Number of
patients*4
*1 This refers to diseases under development at the time of this presentation and may differ from the final indications approved by regulatory authorities. *2 Represents the anticipated year of regulatory approval for the indication
currently under development. *3 Market size is our own independent estimate based on the total of all products for the “disease under development.” The colored section is global, the rest are values for Japan only. ★: Under 50 billion
yen, ★★: 50 billion yen or more– Under 100 billion yen, ★★★: 100 billion yen or more– Under 500 billion yen, ★★★★: 500 billion yen or more– Under 1 trillion yen, ★★★★★: 1trillion yen or more *4 This is an independent
estimate by our company. Colored sections are values for global, the rest for Japan only. *5 Equivalent to phase 3 trial. *6 “1 in 100,000” is for all MPS-I cases,Hurler syndrome accounts for 60% of this value. *7 P1/2 Equivalent to trial.
© Kyowa Kirin Co., Ltd.
34
Key Development Pipeline (2)
Disease in Development*1
KK4277
Systemic Lupus Erythematosus
Cutaneous Lupus Erythematosus
As of Nov 2, 2026
Development Status
Modality, Technology Used
P1 (Japan/Asia) completed
Antibody, POTELLIGENT®
KK2260
Advanced/Metastatic Solid Tumors
P1
(JP: Ongoing, US: Prep)
Antibody, REGULGENTTM
KK2269
Advanced/Metastatic Solid Tumors
P1 (JP/US)
Antibody, REGULGENTTM
KK2845
Acute Myeloid Leukemia (AML)
P1 (Japan)
Antibody-Drug Conjugate (ADC)
KK8123
XLH (Adults)
P1/2 (US/EU)
Antibody
KK8005
XLH (Adults)
P1/2 (Japan)
Antibody
KK3910
Essential Hypertension
P1 (Japan)
Antibody
KK2223
CTCL, PTCL
P1 (US: Ongoing, EU: Prep)
Antibody-Drug Conjugate (ADC)
KK4408
Autoimmune disease
P1/2 (Japan)
Antibody, REGULGENTTM
*1 Diseases in development as of this presentation; final approved indications may differ from regulatory authorities.
© Kyowa Kirin Co., Ltd.
35
Key Development Pipeline: Future Plans
Product Name
Target Disease
ALL
KOMET0012
Development
Phase
2026
Orange: Ongoing
Gray: Pre-initiation or Completed
2027
As of Nov 2, 2026
2028
+
P1a1 (KMT2A-r)
P1a1 (non NPM1-m /
non-KMT2A-r AML)
ziftomenib
AML
KOMET0073
P1
KOMET0084
P11
KOMET0175
P3
KOMETJ0016
P2
OTL-203
MPS-I
(Hurler Syndrome)
OTL-200
MLD
P3
KK8398
Achondroplasia
P3
Registrational7
In preparation
- Dose escalation ongoing, 2. 2L+ Mono, 3. 1L, 2L+, Combinations with cytarabine + daunorubicin (7+3), venetoclax + azacitidine, and 7+3 and quizartinib, 4. 2L+, Combination with gilteritinib, FLAGIDA, LDAC, 5. 1L, Combinations with cytarabine + daunorubicin (7+3), and venetoclax + azacitidine, 6. Japan P2 monotherapy study in R/R NPM1-m AML, 7. Equivalent to P3.
Studies of ziftomenib on this slide sponsored by Kura Oncology. Bar graphs correspond to clinicaltrials.gov timelines
© Kyowa Kirin Co., Ltd.
36
Key Development Pipeline: Future Plans
Target Disease
Product Name
KHK4951
tivozanib eyedrop
KK4277
Development
Phase
nAMD
P2
DME
P2
SLE
P1
CLE
KK2260
Advanced/Metastatic Solid
Tumors
P1
KK2269
Advanced/Metastatic Solid
Tumors
P1
KK2845
R/R AML and Other
Hematologic Malignancies
P1
KK8123
XLH (Adults)
P1/2
KK8005
XLH (Adults)
P1/2
KK3910
Essential HTN
P1
KK2223
CTCL, PTCL
P1
KK4408
Autoimmune disease
P1/2
Bar graphs correspond to clinicaltrials.gov timelines
© Kyowa Kirin Co., Ltd.
2026
Orange: Ongoing
Gray: Pre-initiation or Completed
2027
2028
As of Nov 2, 2026
+
September 2026 Topline Data Announcement
P1 study has been completed. Reviewing results to determine next steps.
37
Creating Innovative
Life-changing value
Assets in focus disease areas
Ziftomenib
In development for relapsed/refractory and front-line AML with NPM1 mutation, KMT2A rearrangement, and FLT3 mutation
Differentiated by deep and durable efficacy, combinability with other agents, safety, and a simple dosing schedule
Manageable safety and
tolerability profile
Simplicity
No interaction-driven dose modifications
or additional toxicity beyond standard
therapy expectations
Once-daily oral dosing without weightbased adjustments or complex tablet
combinations
Modalities
Hematology/
Hemato-oncology
Small Molecule
(Once daily, oral)
New Patient
22k/year
US
Compatibility
Disease areas
New Patient
US
Deep and durable clinical responses
Acute Myeloid Leukemia
Japan
Safety
Efficacy
Market potential
7k/year
Total Accessible Market1
~7B USD (US)
Up to ~50% of
overall AML
patients are
eligible
Commercialization
Leveraging Hematology/
Hemato-oncology Franchise
1Kura Oncology estimate.
© Kyowa Kirin Co., Ltd.
38
Creating Innovative
Assets in focus disease
areas
Strategic
Partnering Assets
Life-changing value
KHK4951
In development for neovascular Age-related Macular Degeneration (nAMD) and Diabetic Macular Edema (DME)
Non-invasive eye drop option for maintenance therapy after induction treatment in diseases where intravitreal injection is the SOC1, aiming to
reduce injection frequency and clinic visit burden for patients continuing treatment
Efficient
posterior eye
delivery
KHK4951
Lancet 2012; 379: 1728–38
Nano-crystallized
tivozanib
Market Potential
Global
Market Potential
Disease areas
Ophthalmology
© Kyowa Kirin Co., Ltd.
Modalities
Small Molecule
(Eyedrop)
Commercialization
Exploring
Strategic Partner
Global
nAMD
Patients
2670k
Existing Market Size2
1Trillion Yen~
DME
Patients
2220k
Existing Market Size2
500B~1Tyen
1 Standard of Care, 2 Market size is our own independent estimate based on the total of all products for the disease under development.
39
Creating Innovative
Life-changing value
Assets in focus disease areas
KK2845
Kyowa Kirin’s first ADC in development for relapsed/refractory acute myeloid leukemia (AML)
Targeting TIM-3 with the ADC to reach leukemic stem cells and blasts — aiming for a fundamental cure of the disease
Galectin-9
(TIM-3 Ligand)
TIM-3 signaling
Targeting
TIM-3
Proliferation of AML cells
Leukemic stem
cells (LSC)
KK2845
Leveraging Hematology/
Hemato-oncology Franchise
22k/year
Japan
© Kyowa Kirin Co., Ltd.
Commercialization
Acute Myeloid Leukemia
New Patients
US
Hematology/
Hemato-oncology
Modalities
Antibody Drug
Conjugate
Market Potential
US
Disease areas
Modified from: Kikushige Y et. al., Cell Stem Cell, 2015
New Patients
7k/year
Existing Market Size
500B~1 Trillion Yen
40
Est. Patients
Disease
Country/
Region
Incidence
PTCL
Japan, US, EU4+UK
9,000 / year
CTCL
Japan, US, EU4+UK
Prevalence1
Source
Clarivate - Decision Resources NK/T-Cell Lymphoma/ Global Data - Epidemiology Intelligence
80,000
Clarivate - Decision Resources NK/T-Cell Lymphoma - Epidemiology Intelligence
Japan
1:20,000
Adults: 5,000
Peds: 1,000
Est. based on incidence; Nationwide survey of fibroblast growth factor 23 (FGF23)-related hypophosphatemic diseases in
Japan: prevalence, biochemical data and treatment. (Endo I et al., Endocr J., 2015)
Europe
1:20,000
Adults: 12,000
Peds: 3,000
Est. based on incidence
US
1:20,000
Adults: 12,000
Peds: 3,000
Est. based on incidence; New perspectives on the biology and treatment of X-linked hypophosphatemic rickets. (Carpenter
TO, Pediatr Clin North Am., 1997)
Japan
30
MHLW 2010 Epi Survey on Hormone Receptor Abnormalities
US
500-1,000
Ultragenyx survey
nAMD
Japan, US, EU
2,700,000
Decision Resources survey
MLD
Global
1:100,000
MPS-IH
Global
1:100,0002
MPS-IIIA
Global
~1:100,000
Shapiro EG, et al. J Pediatr. 2016 Mar;170:278-87.e1-4.
AML
Japan
US
7,000 / year
22,000 / year
MHLW 2020 Patient Survey, by Disease
XLH
TIO
Mahmood et al. Metachromatic Leukodystrophy: A Case of Triplets with the Late Infantile Variant and
a Systematic Review of the Literature. Journal of Child Neurology 2010,
Puckett et al. 2021 Orphanet J Rare Dis 16:241: US NBS data (MPS-I incidence derived from NBS
data in Table 3)
National Cancer Institute. Cancer Stat Facts: Leukemia
- Prevalence is est. # per total population of country/region; 2. Value for total MPS-I per 100k live births; Hurler is approx. 60% of this.
© Kyowa Kirin Co., Ltd.
41
Abbreviations
AG
Authorized Generic
ALL
Acute Lymphoblastic Leukemia
AML
Acute Myeloid Leukemia
BS
Biosimilar
CTCL
Cutaneous T-cell Lymphoma
DME
Diabetic Macular Edema
EMEA
Europe, Middle East, & Africa
JP
Japan
LCM
Lifecycle Management
MLD
Metachromatic Leukodystrophy
MPS-IH
Mucopolysaccharidosis type I, Hurler syndrome
MPS-IIIA
Mucopolysaccharidosis type IIIA
NA
North America
nAMD
Neovascular Age-related Macular Degeneration
PTCL
Peripheral T-cell Lymphoma
TIO
Tumor-Induced Osteomalacia
XLH
X-linked Hypophosphatemia
© Kyowa Kirin Co., Ltd.
42
Reference Information URL
(February 2026)
Kyowa Kirin Equity Story
(June 2026)
Integrated Report 2025
(May 2026)
Click here for the material→ LINK
Click here for the material→ LINK
Click here for the material→ LINK
Vision 2030 and Beyond: Our Growth Story
© Kyowa Kirin Co., Ltd.
43
Upcoming IR Event: Roundtable with Independent Outside Directors
Our independent outside directors will engage directly with investors and analysts on Board discussions and
the oversight of management
Takashi Oyamada, MBA
Independent Outside Director
Nomination and Remuneration Advisory
Committee (Committee chair)
Yukiko Ito, Ph.D.
Independent Outside Director
Nomination and Remuneration Advisory
Committee
Kohei Kan
Independent Outside Director
Audit and Supervisory Committee
(Committee chair)
Date & Time: Wednesday, January 20, 2027, 13:30–14:30 JST (planned)
Format: In person at Kyowa Kirin head office and via Zoom (planned)
Program: Opening remarks from the speakers, followed by Q&A (questions will also be accepted in advance)
- Details and registration information will be provided separately. The content is subject to change.
© Kyowa Kirin Co., Ltd.
44
This document contains forward-looking statements regarding the outlook, targets, plans, and other
future-related matters of the Company (including its consolidated subsidiaries in Japan and overseas). These
statements are based on our reasonable judgments using current information and forecasts but involve uncertainties
that could cause actual results to differ materially.
These uncertainties include, but are not limited to, risks inherent in the domestic and international pharmaceutical
industry, intellectual property rights, side effects, legal regulations, product defects, fluctuations in raw material/fuel
prices, market prices, and exchange/financial markets.
This document is for investor information purposes only and contains information on pharmaceuticals (including
products under development), but it is not intended for promotional advertising or medical advice.
© Kyowa Kirin Co., Ltd.
45
~Contact for Inquiries Regarding This Material~
Kyowa Kirin Co., Ltd.
Finance Dep., IR Group
+81-3-5205-7206 / [email protected]