1 CLICK TO REQUEST A COMPANY CALL/MEETING Ceres Inc. (3696) Exit closed, buyback under way 9 October 2026 bitbank sale and buyback Share price: ¥2,295 Market cap: ¥26.5bn • Sale closed, buyback launched – Ceres completed the sale of its bitbank stake…
1
CLICK TO REQUEST A
COMPANY CALL/MEETING
Ceres Inc. (3696)
Exit closed, buyback under way
9 October 2026
bitbank sale and buyback
Share price: ¥2,295 Market cap: ¥26.5bn
• Sale closed, buyback launched – Ceres completed the sale of its
bitbank stake on 1 October for ¥8.6bn and, the same day, announced
a buyback of up to ¥2.5bn, as planned in June when the transaction
was announced. We think the buyback is incrementally positive for
ROE, and if Ceres completes the buyback at the current share price by
the end of FY12/26, we estimate that FY12/27E ROE would increase
to ~18%. The shares trade at 0.63x our SOTP value, so each share that
Ceres buys back is also accretive to SOTP value per share. The
completion of the transaction also simplifies the Company’s earnings
as bitbank’s equity-method results (e.g., the ¥347mn share of losses
in H1 FY12/26) are no longer impacting Ceres’ earnings.
A cleaner P&L and a ¥2.5bn buyback
Source: Bloomberg
• Sale of bitbank completed – Ceres sold its entire stake in bitbank
(22.39% before the capital increase), a crypto asset exchange
operator, for ¥8,612mn as part of bitbank’s acquisition by the SBI
Group. The company expects ~¥5.7bn of consolidated extraordinary
income, slightly above its June estimate of ~¥5.5bn: ~¥2.5bn in Q3
FY12/26 and ~¥3.2bn in Q4.
• Buyback of up to ¥2.5bn – After the sale closed, Ceres announced a
buyback of up to ¥2.5bn or 1.25 million shares (10.83% of shares
outstanding excluding treasury shares), whichever limit is reached
first, funded by the bitbank proceeds, through market purchases until
30 September 2027. This follows the ~¥0.5bn program completed in
June (273,600 shares). Ceres has not yet disclosed any purchases
under the new program.
• A ~4.7x return on the bitbank investment – In our June report, we
estimated a ~4.7x MOIC and a ~+20% gross IRR on the ~¥1.8bn that
Ceres invested in bitbank since 2017. Of the company’s estimated
~¥7.4bn of after-tax proceeds, we calculate ~¥2.85bn for the buyback
and the dividend increase and ~¥4.55bn for growth investment,
including M&A, toward the MTP 2030 targets. For more details, see
our report (“A +20% gross IRR exit and a simpler growth story”).
• Valuations – On our earnings estimates, the shares are trading on
FY12/27E PER of 9.0x and a SOTP multiple of 0.63x.
Price Performance
YTD 1M 3M 12M
Abs (%) +18.1 +11.1
+7.5 -9.4
Rel (%) -2.4 +9.7 +5.4 -35.5
Company sector
Business Services | Specialty Finance and Services
Other Marketing and Advertising Services (GICS)
Stock data
Price (¥) 2,295
Mkt cap (¥bn) 26.5
Mkt cap ($mn) 167.2
52-week range (¥) 1,393 – 2,560
Shares O/S (m) 11.5
Average daily value ($mn) 2.6
Free float (%) 65.9
Foreign shareholding (%) 4.5
Ticker 3696
Exchange Tokyo Prime
Net Debt/Equity (x) Net Cash
BBG BUY│HOLD│SELL 0│0│0
Source: Bloomberg
Year-end 12/24 12/25 12/26E 12/27E 12/28E
Sales (¥bn) 27.71 29.66 37.23 42.04 47.56
OP (¥bn) 2.23 2.33 3.84 4.87 5.64
NI (¥bn) 1.48 2.50 6.18 2.94 3.43
EPS (¥) 128.96 216.61 535.85 254.90 297.11
DPS (¥) 60.00 80.00 90.00 66.00 66.00
Sales growth YoY (%) +15.1 +7.1 +25.5 +12.9 +13.1
OP growth YoY (%) +99.2 +4.8 +64.5 +26.9 +15.8
NI growth YoY (%) +228.2 +68.6 +147.4 -52.4 +16.6
EPS growth YoY (%) +225.9 +68.0 +147.4 -52.4 +16.6
PER (x) 17.8 10.6 4.3 9.0 7.7
EV/EBITDA (x) 8.7 8.2 5.2 4.2 3.7
EV/Sales (x) 0.8 0.8 0.6 0.6 0.5
PBR (x) 2.4 2.0 1.5 1.3 1.2
ROE (%) 14.6 20.4 40.6 15.9 16.0
ROCE (%) 13.8 13.7 18.2 20.4 20.8
FCF yield (%) 0.1 4.5 3.0 15.6 14.5
Dividend yield (%) 2.6 3.5 3.9 2.9 2.9
Source: Company, Astris Advisory (estimates)
Business Overview
Ceres Inc. is a Tokyo-based digital platform operator founded in
2005, with Moppy, Japan's leading point rewards site, as the core of
its business.
Astris-Sustainability ESG rating
Reference Ratings
MSCI -
Sustainalytics -
S&P Global -
Bloomberg -
CDP B
Next events
Q3 FY12/26 results November 2026
Tel: +81 3 6868 8797
Email: [email protected]
This report has been commissioned and paid for
by the company
Japan Corporate Research
Ceres Inc. (3696) – Completion of bitbank sale and share buyback
2
www.corporateresearch.astrisadvisory.com
Completion of the sale of bitbank
Ceres sold all 21,480 of its bitbank shares (22.39% before the capital increase) in a two-
part transaction, as part of bitbank’s acquisition by the SBI Group. On 30 September,
bitbank issued new shares by third-party allotment to SBICAH GK, a wholly owned
subsidiary of SBI Holdings, after which bitbank ceased to be an equity-method affiliate of
Ceres. Ceres expects a ~¥2.5bn gain on change in equity from this step in Q3 FY12/26. On 1
October, bitbank repurchased all of the bitbank shares held by Ceres for ¥8,612mn, for an
expected further ~¥3.2bn gain on sale of investment securities in Q4. The combined
~¥5.7bn compares with the company’s June estimate of ~¥5.5bn and is already reflected in
the Company’s FY12/26 guidance.
The sale completed on the June terms, with a slightly larger gain
expected across Q3 and Q4 FY12/26
Completed transaction terms
Key terms Details
Structure Third-party allotment to SBICAH GK (30 Sep), then repurchase by
bitbank of the bitbank shares held by Ceres (1 Oct)
Shares sold 21,480 (22.39% before the allotment); holding now 0%
Consideration ¥8,612mn in cash
Extraordinary gain (company
estimate)
~¥5.7bn: ~¥2.5bn gain on change in equity (Q3 FY12/26) and ~¥3.2bn
gain on sale of investment securities (Q4 FY12/26)
Source: Company
In our June report, A +20% gross IRR exit and a simpler growth story (Japanese version),
we estimated that Ceres generated a ~4.7x multiple on invested capital (MOIC) and
~+20% gross IRR on the ~¥1.8bn invested since 2017.
Ceres plans to split the ~¥7.4bn of after-tax proceeds between
shareholder returns and growth investment
Use of bitbank sale proceeds
Source: Company, Astris Advisory.
Note: taxes are the difference between the ¥8.6bn transfer price and the company’s ~¥7.4bn after-tax estimate (June); growth
investment is our estimate as the company has not disclosed an amount
Japan Corporate Research
Ceres Inc. (3696) – Completion of bitbank sale and share buyback
3
www.corporateresearch.astrisadvisory.com
Share buyback
The new share buyback program allows Ceres to acquire up to ¥2.5bn or 1.25 million
shares (10.83% of shares outstanding excluding treasury shares), whichever limit is
reached first, through market purchases from 2 October 2026 to 30 September 2027. The
Company noted that the buyback is intended to help achieve the 15% ROE target outlined
in the Company’s medium-term managemen plan (MTP).
With the ~¥0.5bn acquired in May-June and dividends, the company’s planned FY12/26
shareholder returns reach up to ~¥4.0bn. As an illustration only, full execution of the plan
at ¥2,295/share by the end of FY12/26 would lift FY12/27E EPS by ~10%, FY12/27E ROE to
~18% from our 15.9%, and SOTP value per share by ~4%.
The new program is five times the size of the June program by value
Share buyback programs
Prior program (announced Apr 2026) New program (announced Oct 2026)
Maximum shares 350,000 (2.98%) 1,250,000 (10.83%)
Maximum cost ¥500mn ¥2.5bn
Period 1 May-30 Dec 2026 2 Oct 2026-30 Sep 2027
Shares acquired (cost) 273,600 (¥499.95mn) None disclosed as of 9 Oct 2026
Average price (¥) ~1,827 -
Status Completed 17 Jun 2026 Active
Source: Company (including TDnet notices of 1 and 18 June 2026), Astris Advisory.
Note: percentages are of shares outstanding excluding treasury shares at each reference date; average price is our calculation
Japan Corporate Research
Ceres Inc. (3696) – Completion of bitbank sale and share buyback
4
www.corporateresearch.astrisadvisory.com
Sum-of-the-parts valuation
To better assess the value of Ceres, we believe it would be helpful to value the Company on
a sum-of-the-parts (SOTP) basis, reflecting the underlying value of its portfolio of
businesses, and to assign value to its growth-stage businesses that are not yet contributing
to earnings.
Shares trade at a meaningful discount to SOTP valuation, likely reflecting minimal
value being assigned to the Company’s D2C or Financial Service business
Sum-of-the-parts build for Ceres
Value(¥bn)
Notes
Cash 10.27 As of Q2 FY12/26
Net proceeds from sale of bitbank
shares
7.40
Net of estimated taxes (company estimate, June); sal
e completed 1 Oct 2026
Investment Securities
1.10 As of Q4 FY12/25
Investment in Affiliates
0.10
As of Q2 FY12/26, adjusted for the sale of bitbank sh
ares
Debt
-10.86 As of Q2 FY12/26
Hard Assets 8.01
Point 28.11
Derived from applying a 1.0x EV/Sales multiple to the
segment's FY12/26E revenue forecast of ¥28.1bn.
The multiple is in line with the listed domestic peers
D2C 2.30
Derived from applying a 0.4x EV/Sales multiple to the
segment's FY12/26E revenue forecast of ¥5.74bn.
The multiple is at a discount to the listed domestic
peer, reflecting operating challenges at the
segment’s flagship brand
Financial Service 3.38
Derived from applying a 1.0x EV/Sales multiple to the
segment's FY12/26E revenue forecast of ¥3.38bn.
This is at a discount to listed peers, reflecting lower
scale and profitability.
Sum-of-the-parts Value 41.80
SOTP Value/Share
3,620.77
Current Share Price 2,295.00
P/SOTP Value (x) 0.63x
Source: Company, Astris Advisory
Japan Corporate Research
Ceres Inc. (3696) – Completion of bitbank sale and share buyback
5
www.corporateresearch.astrisadvisory.com
Ceres trades at a discount relative to domestic peers despite an established track record of strong ROE and revenue growth, which
we think is partly driven by the complexity of the Company’s diverse business operations.
Peer analysis of key profitability and valuation metrics
Profitability Valuation
Ticker Company Mkt Cap OPM OPM 10-yr ROE ROIC 10-yr EV/EBITDA EV/Sales Div yield PER PBR
US$ (mm)
LTM (%) average
(%)
LTM (%) average
(%)
12M Fwd
(x)
12M Fwd
(x)
12M Fwd
(%)
12M Fwd
(x)
(x)
3696 JP CERES INC. 167 9.7 9.4 15.5 6.7 4.4 0.6 3.1 7.2 2.0
Domestic peers
Online marketing platforms and infrastructure
2491 JP ValueCommerce Co., Ltd. 61 -4.1 16.3 -14.7 22.3 - - - - 0.9
6562 JP Geniee, Inc. 84 9.2 6.2 3.9 -4.4 - - - - 2.0
4819 JP Digital Garage, Inc. 694 -5.8 -1.4 1.8 3.4 - 1.8 2.0 47.4 1.5
4751 JP CyberAgent Incorporated 3,914 9.5 8.3 22.2 13.2 5.0 0.5 1.9 13.4 3.0
D2C Operators
4933 JP I-ne CO., LTD. 250 7.9 7.2 12.5 14.6 - - - - 2.2
Cryptocurrency Platforms
CNCK US Coincheck Group N.V. 253 -0.2 0.5 -9.2 -1.2 94.9 0.0 - - 0.9
Median 3.9 6.7 2.9 8.3 50.0 0.5 2.0 30.4 1.8
Overseas peers
Online marketing platforms and infrastructure
CDLX US Cardlytics, Inc. 11 -16.1 -25.0 - -40.2 22.5 1.1 - - -
D2C Operators
ELF US e.l.f. Beauty, Inc. 6,252 12.0 9.9 5.2 9.7 16.3 3.3 - 28.2 5.3
HIMS US Hims & Hers Health, Inc. Class A 6,547 0.0 -9.9 -31.4 -6.3 19.4 1.9 - 298.4 20.2
Cryptocurrency Platforms
COIN US Coinbase Global, Inc. Class A 45,380
-37.6
8.1 -6.8 7.3 20.4 6.7 - 110.3 3.5
GEMI US Gemini Space Station, Inc. Class A 580
-293.3
-237.4 -92.2 - -2.9 2.3 - - 1.2
Online SME lending
ENVA US Enova International Inc 4,546 24.1 20.2 25.6 11.9 8.0 2.1 - 9.1 3.0
Median -8.1 -0.9 -6.8 7.3 17.9 2.2 - 69.3 3.5
Source: FactSet, Bloomberg, Astris Advisory
Note: LTM is the last 12 months
Japan Corporate Research
Ceres Inc. (3696) – Completion of bitbank sale and share buyback
6
www.corporateresearch.astrisadvisory.com
Astris earnings estimates and key
assumptions
Our earnings estimates are unchanged from our Q2 FY12/26 results note and exclude the
new share buyback; see the illustrative scenario above for its effect.
• Successful execution of the Company’s MTP, including steady growth of the Point
business, rebound of the D2C business, and acceleration in the Financial Service
business.
• We have not factored in shifts in the trajectory of the interest rate environment
and the subsequent impact on ad-spend, consumer demand and credit
performance.
• We have not factored in any additional M&A activity.
Astris Advisory earnings estimates
Year-end FY12/26E
FY12/27E FY12/28E
Point 28.11 30.92 34.02
D2C 5.74 6.89 8.27
Financial Service 3.38 4.22 5.28
Sales(¥bn) 37.23 42.04 47.56
Growth YoY (%) +25.5 +12.9 +13.1
Net income (¥bn) 6.43 3.22 3.74
Net income margin (%) 16.6 7.0 7.2
ROE (%) 40.6 15.9 16.0
ROA (%) 15.1 6.3 6.5
DPS (¥) 90.0 66.0 66.0
Dividend yield (%) 3.9 2.9 2.9
Source: Astris Advisory
The core assumptions of our estimates are as follows:
• Sales growth – We believe the Company's sales growth will be driven by continued
expansion of the Point segment, reflecting both organic advertising market growth
and the first full-year consolidation of Point Income. This is supplemented by
recovery in D2C revenue as Pitsole headwinds dissipate and recently acquired
brands begin to contribute, and progressive revenue growth in Financial Service as
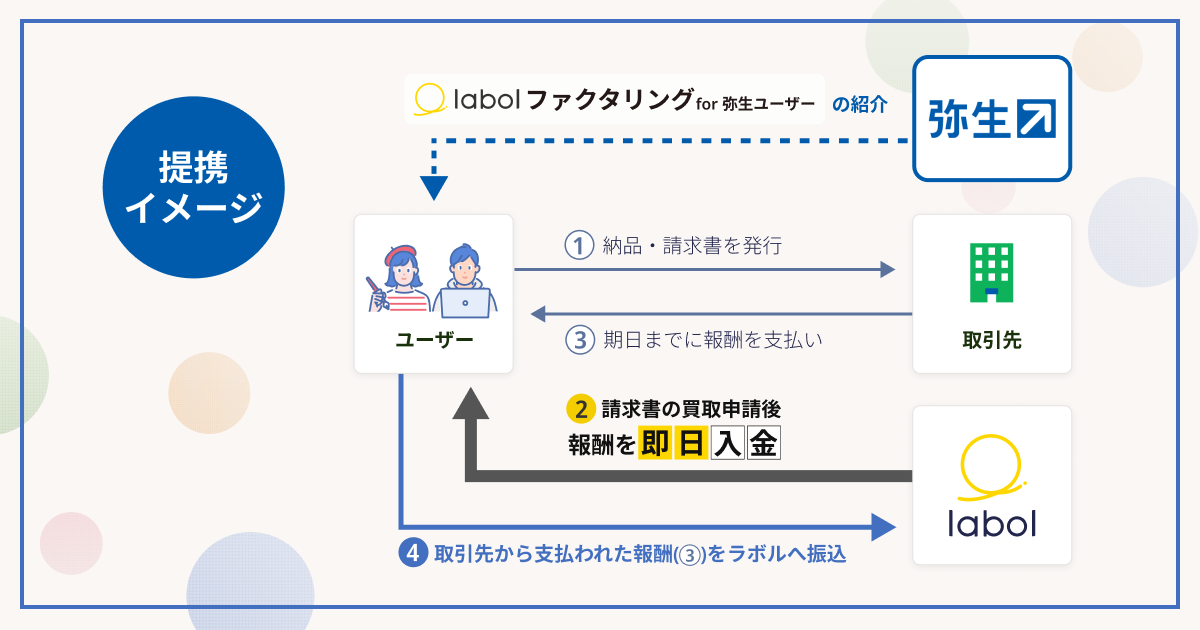
labol scales its GMV base.
• Profitability – We forecast gradual improvement in consolidated operating
margins over the forecast period, driven by D2C recovery toward normalized
margin levels, progressive narrowing of Financial Service losses as labol scales and
Mercury's cost base matures, and Point segment margin expansion as Point
Income PMI progresses and AD.TRACK internalization increases.
Japan Corporate Research
Ceres Inc. (3696) – Completion of bitbank sale and share buyback
7
www.corporateresearch.astrisadvisory.com
Summary
Ceres Inc. is a Tokyo-based digital platform operator founded in 2005, with Moppy, Japan's
leading online points rewards site, at its core. Over two decades, the Company has grown
revenue from ¥64mn to ¥29.7bn through a combination of organic growth and M&A, while
systematically redeploying cashflow from the core Point business to incubate and scale
adjacent ventures in D2C and Financial Service. Following the FY12/25 divestiture of
YUMEMI for ~¥3.7bn, Ceres has refocused its portfolio around three growth pillars: the
Point business, D2C brand roll-up, and Financial Service centered on labol and Mercury.
We believe Ceres offers an attractive and underappreciated way to gain exposure to
Japan's digital advertising and fintech ecosystems through a platform operator with a
demonstrated track record of value creation from internally incubated businesses.
The following findings from our report underpin the thesis:
• The market has not given Ceres credit for its track record of building businesses
from scratch. The Company incubated D2C from ¥10mn to ¥4.9bn in revenue, grew
labol's GMV approximately 70x in four years, and generated a post-tax MOIC of 6.6x
and ~31% IRR on the YUMEMI investment.
• labol is the most visible near-term catalyst and the critical driver for MTP delivery.
Incubated internally since December 2021, labol is now the primary revenue driver
within Financial Service and is on track to reach full-year profitability in FY12/26. A
stated management objective to pursue an independent IPO for labol would be the
most significant value crystallization event since the YUMEMI divestiture.
• The core Point business continues to scale, and Point Income integration is a direct,
low-risk margin uplift opportunity. Point segment revenue grew 39.4% YoY to
¥20.1bn in FY12/25, with membership and ARPU expanding simultaneously, signaling
that fundamentals remain strong.
Astris Advisory estimates Ceres will drive medium-term growth through:
• Continued expansion of the Point segment, reflecting both organic advertising
market growth and the first full-year consolidation of Point Income. This is
supplemented by recovery in D2C revenue as Pitsole headwinds dissipate and
recently acquired brands begin to contribute, and progressive revenue growth in
Financial Service as labol scales its GMV base.
• Gradual improvement in consolidated operating margins over the forecast period,
driven by D2C recovery toward normalized margin levels, and progressive
narrowing of Financial Service losses.
The shares are trading on an estimated PER FY12/27 of 9.0x, a PBR of 1.3x, and a Sum-of-
the-parts multiple of 0.63x. We believe investors should also value the shares on a SOTP
basis given the Company’s broad business portfolio.
Ceres has
refocused its
portfolio around
three growth
pillars: the Point
business, D2C
brand roll-up, and
Financial Services
centered on labol
and Mercury.
Ceres’ MTP
outlined aggressive
growth targets,
which if achieved,
would be
transformative for
the Company.
Japan Corporate Research
Ceres Inc. (3696)
8
www.corporateresearch.astrisadvisory.com
JGAAP Financial Summary
Income statement FY FY FY FY FY
(¥bn)
12/24 12/25 12/26E 12/27E 12/28E
Sales 27.71 29.66 37.23 42.04 47.56
COGS (14.37) (16.64) (21.22) (23.96) (27.11)
Gross profit 13.34 13.02 16.01 18.08 20.45
Gross profit margin (%) 48.1 43.9 43.0 43.0 43.0
Operating profit 2.23 2.33 3.84 4.87 5.64
OP margin (%) 8.0 7.9 10.3 11.6 11.9
Non-operating income 0.51 0.05 - 0.01 0.01
Non-operating
expenses
(0.06) (0.28) (0.40) (0.05) (0.05)
Ordinary profit 2.68 2.11 3.35 4.74 5.51
Extraordinary gains 0.02 2.76 5.40 - -
Extraordinary losses (0.31) (0.25) - - -
Pre-tax profit 2.38 4.62 8.75 4.74 5.51
Tax (0.86) (1.99) (2.32) (1.52) (1.76)
Effective tax rate (%) 35.9 43.1 26.5 32.0 32.0
Net income 1.53 2.63 6.43 3.22 3.74
Non-controlling NI 0.05 0.13 0.25 0.28 0.32
Parent attributable NI 1.48 2.50 6.18 2.94 3.43
Sales growth YoY (%) +15.1 +7.1 +25.5 +12.9 +13.1
OP growth YoY (%) +99.2 +4.8 +64.5 +26.9 +15.8
Pre-tax profit YoY (%) +187.3 +93.8 +89.3 -45.8 +16.3
NI growth YoY (%) +228.2 +68.6 +147.4 -52.4 +16.6
Cash flow statement FY FY FY FY FY
(¥bn) 12/24 12/25 12/26E 12/27E 12/28E
Profit before tax 2.38 4.62 8.75 4.74 5.51
Depreciation/amortization 0.46 0.49 0.65 0.65 0.66
Changes in working capital (1.36) 1.18 (0.50) 0.66 (0.17)
Other non-cash items (0.25) (3.49) (5.40) - -
Tax paid (0.52) (1.13) (2.32) (1.52) (1.76)
Cash from Operating Activities 0.72 1.67 1.18 4.53 4.23
Capex (0.71) (0.49) (0.40) (0.40) (0.40)
Acquisitions/increase stakes (0.13) 1.75 7.40 - -
Other investing cash flow 0.32 (0.52) - - -
Cash from Investing Activities (0.52) 0.74 7.00 (0.40) (0.40)
Total cash dividends paid (0.23) (0.69) (1.04) (0.76) (0.76)
Debt issuance/(retirement) 2.10 (0.37) - - -
Equity financing/(buybacks) 0.11 - - - -
Other 1.28 0.24 0.24 0.24 0.24
Cash from Financing Activities 3.27 (0.82) (0.80) (0.52) (0.52)
FX impact - - - - -
Net cash flow 3.47 1.59 7.38 3.61 3.30
Free cash flow 0.02 1.18 0.78 4.13 3.83
EBITDA 2.68 2.83 4.49 5.53 6.30
EBITDA margins (%) 9.7 9.5 12.1 13.1 13.2
Free cash flow margin (%) 0.1 4.0 2.1 9.8 8.0
Free cash flow conversion (%) 0.7 25.6 8.9 87.3 69.5
Capex/sales (%) 2.5 1.6 1.1 1.0 0.8
Capex/depreciation (%) 154.8 98.7 61.2 61.1 61.0
CFO margin (%) 2.6 5.6 3.2 10.8 8.9
Balance sheet FY FY FY FY FY
(¥bn) 12/24 12/25 12/26E 12/27E 12/28E
Cash & equivalents 11.57 13.08 20.46 24.07 27.37
Inventory 2.05 1.69 2.12 2.39 2.70
Accounts receivables 3.90 3.83 4.81 5.43 6.14
Other 6.32 7.18 9.02 10.18 11.52
Current assets 23.85 25.78 36.40 42.07 47.74
Tangible assets 0.78 0.76 0.51 0.26 0.00
Intangible assets 1.49 3.01 3.01 3.01 3.01
Investment in affiliates 3.60 3.92 0.29 0.36 0.43
Investment 1.14 1.10 1.10 1.10 1.10
Other 2.11 2.93 2.93 2.93 2.93
Fixed assets 9.13 11.73 7.84 7.66 7.47
Total assets 32.98 37.50 44.24 49.72 55.20
Short-term borrowing 6.42 6.67 6.67 6.67 6.67
Trade creditors 0.87 1.04 1.31 1.48 1.68
Other 9.56 12.71 15.16 17.71 19.70
Current liabilities 16.85 20.42 23.16 25.88 28.07
Long-term borrowing 3.09 2.75 2.75 2.75 2.75
Other LT liabilities 0.31 0.37 0.37 0.37 0.37
Long-term liabilities 3.40 3.12 3.12 3.12 3.12
Shareholder’s equity 11.15 13.30 17.13 19.78 22.95
Share acquisitions rights - - - - -
Non-controlling interests 1.57 0.66 0.83 0.94 1.07
Total net assets 12.72 13.96 17.96 20.73 24.01
Total liabilities & net
assets 32.98 37.50 44.24 49.72 55.20
Source: Company, Astris Advisory (estimates)
Key metrics FY FY FY FY FY
12/24 12/25 12/26E 12/27E 12/28E
Profitability
Gross margin (%) 48.1 43.9 43.0 43.0 43.0
Operating margin (%) 8.0 7.9 10.3 11.6 11.9
Net margin (%) 5.3 8.4 16.6 7.0 7.2
ROA (%) 5.0 7.1 15.1 6.3 6.5
ROE (%) 14.6 20.4 40.6 15.9 16.0
ROCE (%) 13.8 13.7 18.2 20.4 20.8
ROIC (%) 7.7 6.1 11.5 11.9 12.5
Liquidity
Current ratio (x) 1.4 1.3 1.6 1.6 1.7
Quick ratio (x) 1.3 1.2 1.5 1.5 1.6
Leverage
Debt/Equity ratio (x) 0.9 0.7 0.5 0.5 0.4
Net Debt/Equity ratio (x) net
cash
net
cash
net
cash
net
cash
net
cash
Equity ratio (x) 0.34 0.4 0.4 0.4 0.4
Interest cover (x) N/A N/A 40.8 51.7 59.9
Net Debt/EBITDA (x) N/A N/A N/A N/A N/A
Valuation
EPS reported (¥) 129.0 216.6 535.8 254.9 297.1
PER (x) 17.8 10.6 4.3 9.0 7.7
Diluted PER (x) 17.8 10.6 4.3 9.0 7.7
DPS (¥) 60.0 80.0 90.0 66.0 66.0
Dividend payout ratio (%) 46.5 36.9 16.8 25.9 22.2
Dividend yield (%) 2.6 3.5 3.9 2.9 2.9
Free cash flow yield (%) 0.1 4.5 3.0 15.6 14.5
Diluted free cash flow yield
(%)
0.1 4.5 3.0 15.6 14.5
PBR (x) 2.4 2.0 1.5 1.3 1.2
EV/sales (x) 0.8 0.8 0.6 0.6 0.5
EV/EBITDA (x) 8.7 8.2 5.2 4.2 3.7
EV/EBIT (x) 10.5 10.0 6.1 4.8 4.1
Japan Corporate Research
Ceres Inc. (3696)
9
www.corporateresearch.astrisadvisory.com
Disclaimers
This report has been prepared by Astris Advisory Japan K.K. This report is based on information obtained from public sources that Astris
Advisory Japan K.K. believes to be reliable but which Astris Advisory Japan K.K. has not independently verified, and Astris Advisory
Japan K.K. makes no guarantee, representation, or warranty as to its accuracy or completeness. This report does not and does not
attempt to, contain everything material which there is to be said about the Company. Any opinions expressed herein reflect Astris
Advisory Japan K.K.’s judgment at the time the report was prepared and are subject to change without notice. Forward-looking
information or statements in this report contain information that is based on assumptions, forecasts of future results, estimates of
amounts not yet determinable, and therefore involve known and unknown risks, uncertainties, and other factors that may cause the
actual results, performance, or achievements of their subject matter to be materially different from current expectations.
This report has been prepared as general information, is therefore not intended as a personal recommendation of particular financial
instruments or strategies, and does not constitute personal investment advice.
The analyst hereby certifies that (i) the views expressed in this report accurately reflect the research analyst’s personal views about the
company and the securities that are the subject of this report, and (ii) no part of the research analyst’s compensation was, is, or will be,
directly or indirectly, related to views expressed by that research analyst in this report.
The report has been prepared by Astris Advisory Japan K.K., a Japanese firm organized under the laws of Japan and supervised by the
Japanese Financial Services Agency. Details about the extent of our regulation by local authorities are available from us upon request.
Conflict of interest
This report has been commissioned and paid for by the company and is deemed to constitute an acceptable minor non-monetary benefit
as defined in MiFID II.
Readers should assume that Astris Advisory Japan K.K. may currently or may in the coming three months and beyond be providing or
seeking to provide IR/corporate advisory or other services to the company.
Investment in securities mentioned: Astris Advisory Japan K.K. has a restrictive policy over personal dealing for its directors, officers,
employees, and service providers. Astris Advisory Japan K.K. does not conduct any investment business and does not hold any
positions in the securities mentioned in this report.
Limitation of liability
Astris Advisory Japan K.K. assumes no liability as regards any investment, divestment, or retention decision taken by the investor based
on this report. In no event will Astris Advisory Japan K.K. be liable for direct, indirect, incidental, special, or consequential damages
(regardless of whether being considered foreseeable or not) resulting from the information in this report.
Copyright 2026 Astris Advisory Japan K.K. All rights reserved.