OUTCOME OF ASSESSMENT OF STRATEGIC OPTIONS FOR SMT SOLUTIONS SEGMENT
Bull 2
Bear 0
Other
522
|
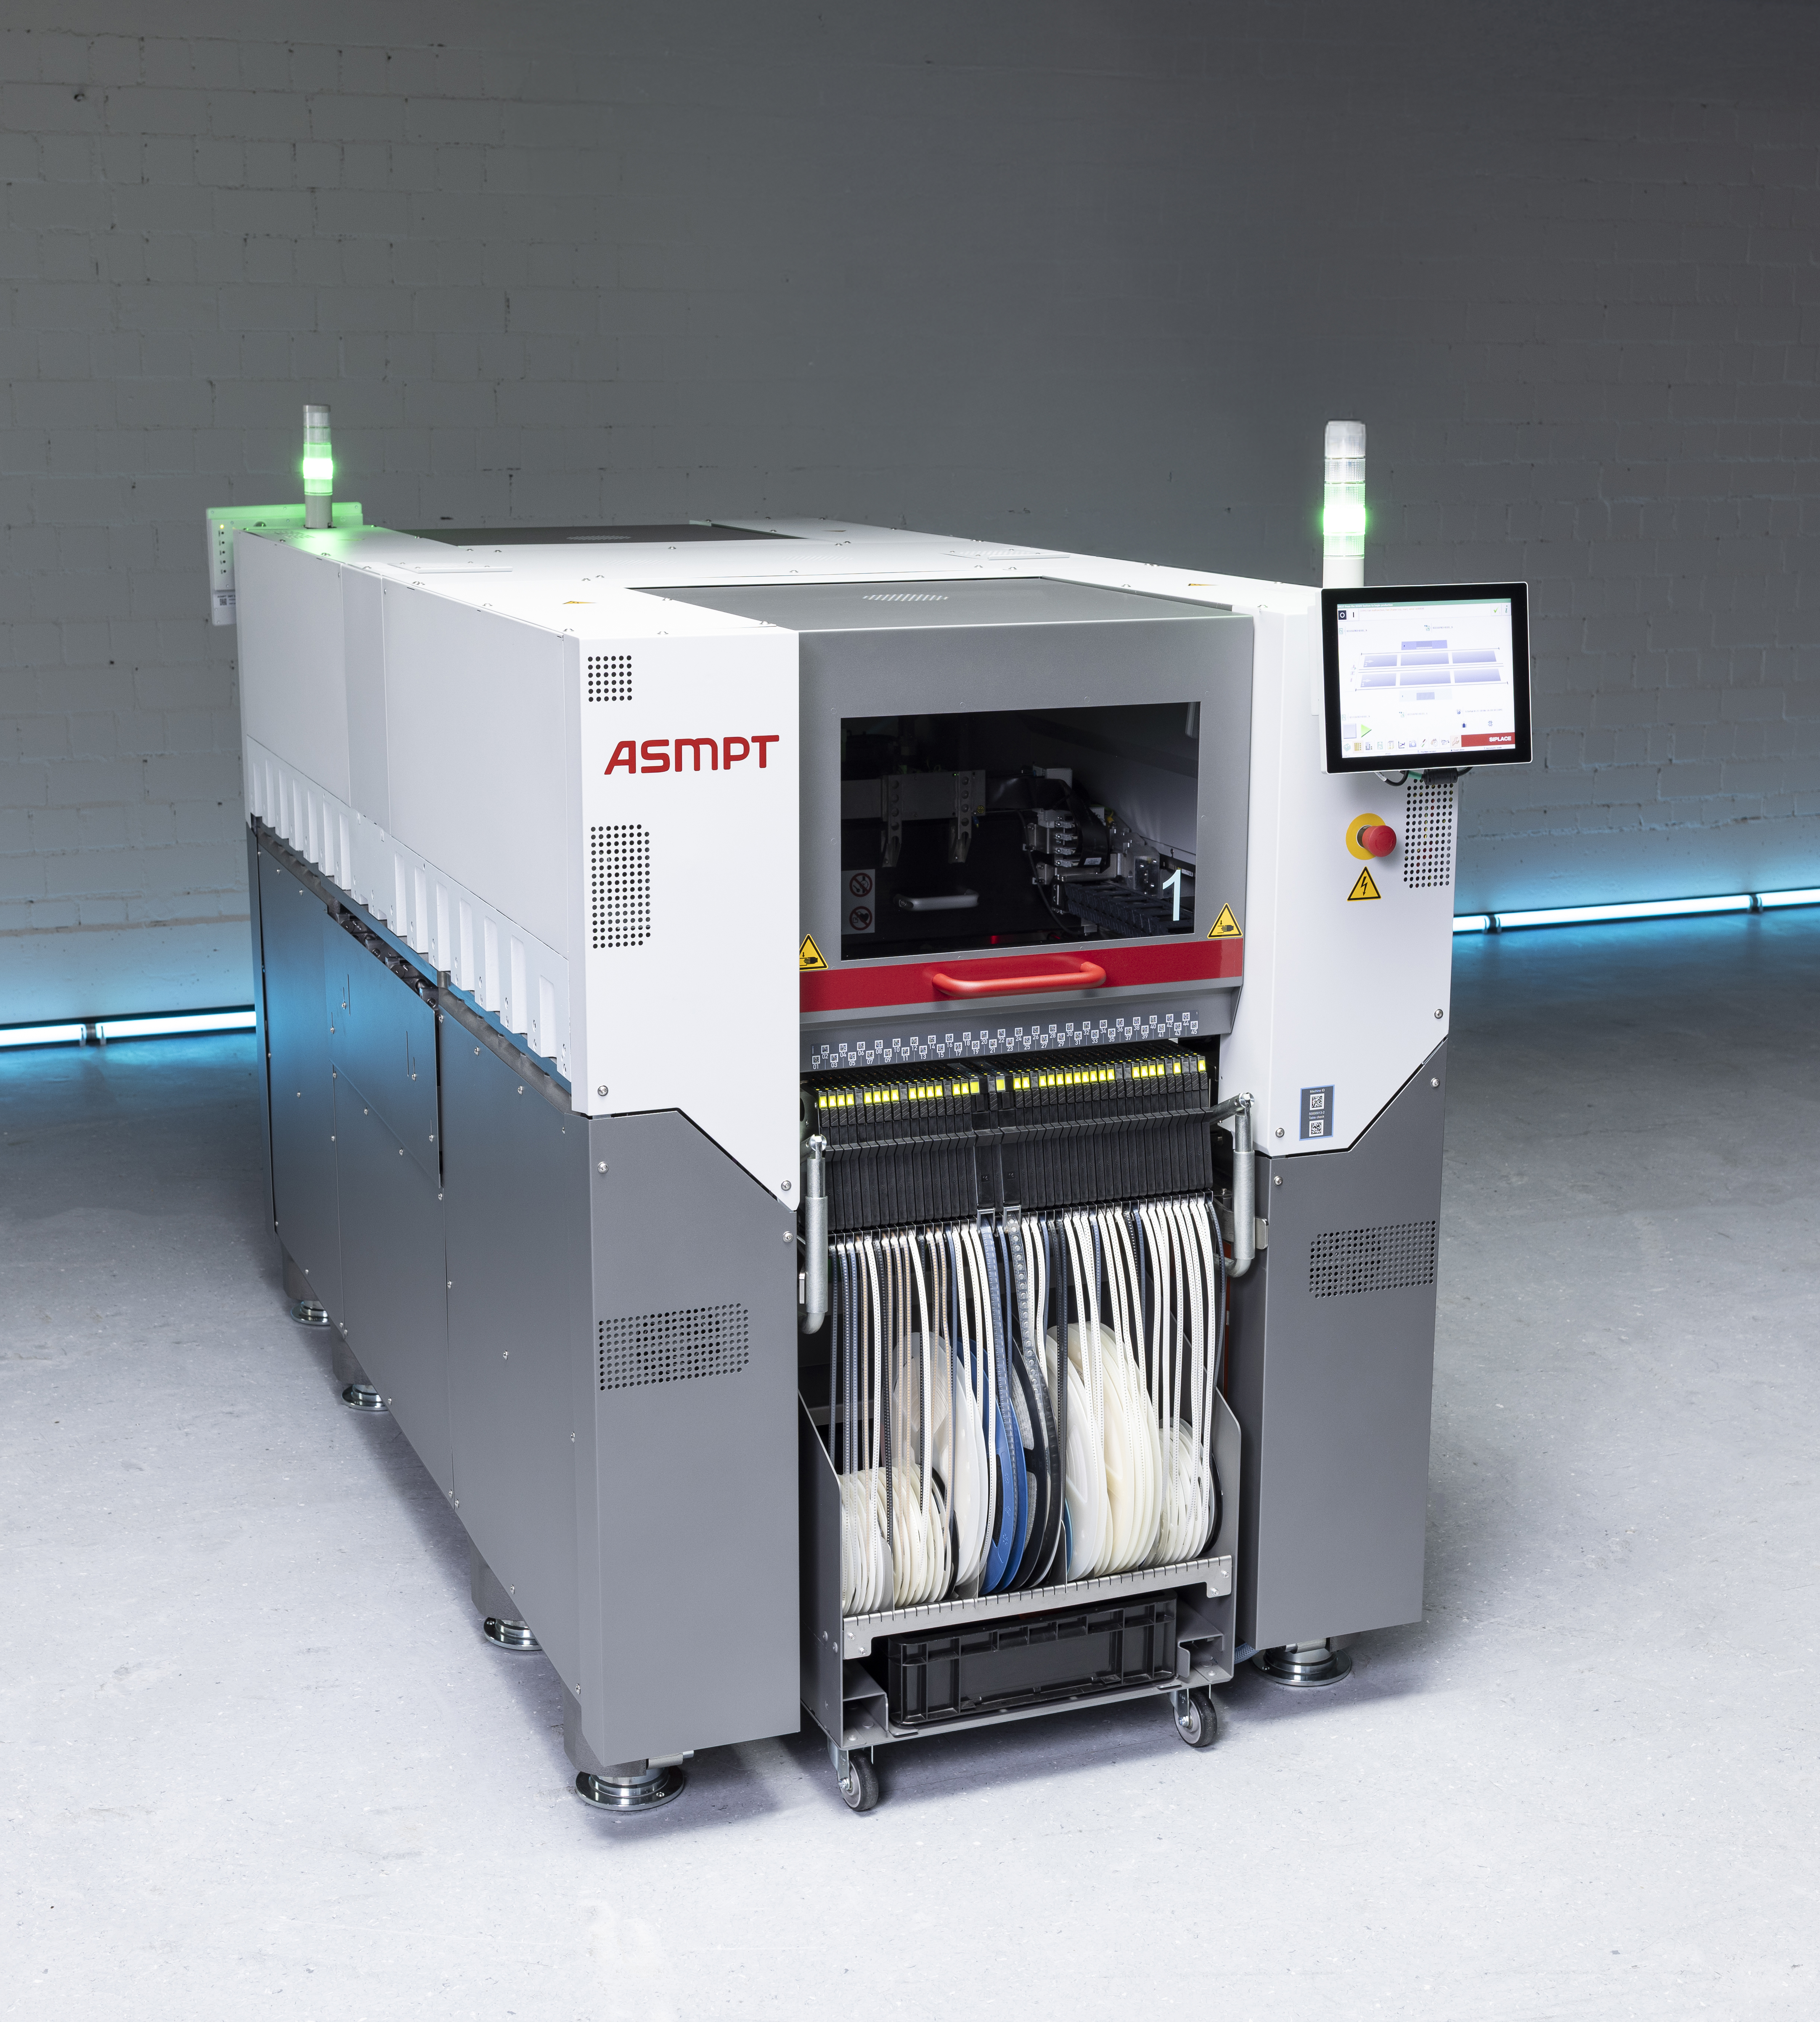
ASMPT Limited is an investment holding company whose principal subsidiaries design, manufacture, and market machines and tools for the semiconductor and electronic assembly industries. The group operates through two main segments: SEMI Solutions, which provides advanced packaging equipment such as thermo-compression bonding (TCB) tools, laser dicing and grooving systems, and wet processing equipment; and SMT Solutions, which offers surface mount technology (SMT) printing and placement systems. Key products include the ALSI LASER1206 for laser dicing, SIPLACE for SMT placement, and DEK for SMT printing. The company serves major semiconductor and electronics manufacturers globally, with a focus on applications in artificial intelligence, high-performance computing, and automotive sectors. Notable partnerships include collaborations with IBM for chiplet packaging bonding methods and KOKUSAI ELECTRIC for 2.5D and 3D heterogeneous integration. ASMPT was founded in 1975 as the Asian marketing arm of ASM International N.V. and has since grown through acquisitions, including Automation Engineering Inc (AEi), AMICRA, and the Siemens Electronics Assembly System (SEAS) business. Summarised from the company's own disclosures, fiscal year ended Apr 2026 |
Industry Semiconductor Equipment & Materials | Homepage asmpt.com |
| Sector Technology | IR page asmpt.com | |
|
Tags
advanced packaging, thermo-compression bonding, surface mount technology, laser dicing, semiconductor assembly, electronic assembly, chiplet packaging, heterogeneous integration, automotive electronics, high-performance computing, SEMI Solutions, SMT Solutions, ALSIS LASER1206, SIPLACE, DEK, Automation Engineering Inc, AEi, AMICRA, Siemens Electronics Assembly System, SEAS, AoXinMing, Borey Advanced, Semiconductor Wet Advanced Technology, SKT Max, Critical Manufacturing, Advanced Laser Separation International B.V., ALSI
|
Press page asmpt.com/en/news-center/press-releases |
Metrics
| Valuation | |
|---|---|
| Market cap | HK$ 37.32B |
| Market cap (USD) | $ 4.756B |
| P/E | 41.08 |
| PEG | — |
| P/BV | 2.14 |
| P/S | 2.32 |
| P/OCF | 34.46 |
| P/FCF | — |
| Dividend yield | 2.4% |
| Turnover / mcap | 1.1% |
| Returns | |
|---|---|
| ROE | 6.7% |
| ROI | 6.3% |
| ROIC | 6.3% |
| Profit margin | 7.9% |
| Growth | |
|---|---|
| Revenue growing | No |
| Profits growing | Yes |
| Revenue up 3y | No |
| Revenue up 5y | No |
| Earnings growth 3y (net profit CAGR) | -25.5% |
| Quality | |
|---|---|
| Profitable | Yes |
| Margin expanding | Yes |
| Buying back stock | No |
| Diluting (TTM) | No |
| Debt/Equity | 0.72% |
| Podcast bulls (TTM) | Sign up |
| Podcast bears (TTM) | Sign up |
| Podcast sentiment (TTM) | Sign up |
| Podcast sentiment % (TTM) | Sign up |
| News sentiment (TTM) | 0 |
| Quality score | 11.1% |
| Insiders | |
|---|---|
| Buys, 1w | Sign up |
| Buys, 1m | Sign up |
| Buys, 1y | Sign up |
| Sells, 1w | Sign up |
| Sells, 1m | Sign up |
| Sells, 1y | Sign up |
Sign up to see this company's insider trades
| Figure | FY 2025 | FY 2024 | FY 2023 | FY 2022 | FY 2021 | FY 2020 | FY 2019 | FY 2018 | FY 2017 | FY 2016 | FY 2015 | FY 2014 | FY 2013 | FY 2012 | FY 2011 | FY 2010 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue | 13.736B | 13.229B | 14.697B | 19.363B | 21.948B | 14.7B | 15.883B | 19.551B | 17.523B | 14.249B | 12.977B | 14.229B | 10.841B | 10.461B | 12.915B | 9.515B |
| Net profit | 1.085B | 345.262M | 715.353M | 2.62B | 3.169B | 636.612M | 619.249M | 2.216B | 2.815B | 1.464B | 956.191M | 1.6B | 558.589M | 688.994M | 2.932B | 2.842B |
Sign up to see institutional holdings
Sign UpPodcast Mentions
Sign up to see podcast mentions and sentiment
Sign UpAnnouncements and reports published on HKEXnews, newest first, monthly and next-day returns, proxy forms and board-meeting notices included. The link opens the announcement on HKEXnews. Press releases from the company's own website, newest first.
ASMPT Announces 2026 Third Quarter Results Record Group Bookings and Strong Earnings Across SEMI & SMT
Bull 5
Bear 0
Results
28.10.2026
Group Performance at a Glance
Key Highlights
- Record Group bookings, driven by TCB, SMT products, and Photonics
- Record TCB C2S orders fuelled by strong demand from AI data centres
- Continued momentum in Photonics resulting in record bookings and revenue
- Adjusted gross margin rose to 42.9%, driven by both SMT and SEMI
- Revenue and adjusted EPS exceeded consensus
Group Results Summary
| (in HK$ million) | Q3 2026 | QoQ | YoY |
|---|---|---|---|
| Continuing Operations1 | |||
| Bookings****2 | 8,845.1(US$1,128.0 million) | +24.7% | +137.9% |
| Revenue | 5,247.0(US$669.2 million) | +6.3% | +48.7% |
| Gross Margin | 42.1% | -29bps | +661bps |
| Operating Profit | 798.6 | +1.5% | +890.9% |
| Net Profit | 533.2 | +27.6% | NM |
| Basic Earnings Per Share | HK$1.28 | +26.7% | NM |
| Non-HKFRS Measures3 of Continuing Operations****1 | |||
| Adjusted Gross Margin | 42.9% | +35bps | +517bps |
| Adjusted Operating Profit | 922.4 | +8.9% | +379.2% |
| Adjusted Net Profit | 689.7 | +8.2% | +486.3% |
| Adjusted Basic Earnings Per Share | HK$1.65 | +7.8% | +489.3% |
NM: Not meaningful
Revenue Guidance for Q4 2026
- US$670 million to US$730 million, up 4.6% QoQ and 37.5% YoY at mid-point of US$700 million
Full Results Announcement and Investor Presentation available from
https://www.asmpt.com/en/investor-relations/financial-information/
1 The Closing of the Disposal of ASMPT NEXX, Inc. (“NEXX”) took place on 3 June 2026. Following Closing, NEXX has ceased to be a subsidiary of the Company
2 Bookings reflect new orders secured during the quarter
3 For more information about the Non-HKFRS Measures presented above, please refer to the section under “Reconciliation of HKFRS Measures to the non-HKFRS Measures” of the Group’s Q3 2026 results announcement
(Hong Kong, 28 October 2026) – ASMPT Limited (ASMPT / the Group / the Company) (Stock code: 0522), a leading global provider of hardware and software solutions for the manufacture of semiconductors and electronics, announced its unaudited results for the three months ended 30 September 2026 (Q3 2026).
The Group achieved record bookings in Q3 2026, supported by sustained AI infrastructure investment driving demand across Advanced Packaging (AP), SEMI Mainstream and SMT. SEMI demand was largely driven by Thermo Compression Bonding (TCB) and Photonics supporting advanced chip packaging and optical connectivity, while SMT continued to benefit from robust demand for AI server boards and optical transceivers.
-
Group Bookings at a record high of HK$8.85 billion (US$1.13 billion), up 24.7% QoQ and 137.9% YoY, with book-to-bill ratio of 1.69, highest since Q1 2021.
- SEMI bookings up 31.3% QoQ and 156.3% YoY, highest since Q1 2021. AI-driven demand supported a broad section of SEMI’s portfolio, notably TCB, Photonics and Flip Chip solutions.
- SMT bookings hit a new record high for the third consecutive quarter, up 18.9% QoQ and 122.1% YoY, driven largely by robust AI server demand, and more than US$100 million worth of bulk orders and pull-in.
-
Group Revenue increased 6.3% QoQ and 48.7% YoY to HK$5.25 billion, above mid-point of guidance, driven by both SEMI and SMT.
-
Group adjusted gross margin of 42.9% was up 35 bps QoQ and 517 bps YoY, reflecting improvements in both SMT and SEMI.
-
Adjusted operating expenditure (OPEX) up 6.0% QoQ and 16.6% YoY, mainly due to higher incentive provisions and increased volume.
-
Adjusted operating profit up 8.9% QoQ and 379.2% YoY to HK$922.4 million, due to higher revenue and gross margin.
-
Adjusted net profit up 8.2% QoQ and 486.3% YoY to HK$689.7 million, due to higher operating profit.
“ASMPT’s record bookings this quarter reflect sustained AI infrastructure investment driving demand across our broad portfolio, particularly in TCB, SMT and Photonics,” said Mr. Bassel Haddad, Group CEO. “A few months in as CEO, I have been very impressed by the depth of ASMPT’s technology and engineering talent. Our opportunity is to translate these strengths into sharper execution and greater speed, to generate attractive shareholder returns. ASMPT will be technology-led, customer-driven and financially disciplined.”
Broad AI-related demand across the portfolio
In logic, demand for AI computing continued to drive strong customer investment momentum across the Group’s TCB solutions. C2S orders reached a record high, led by strong demand for larger compound-die TCB tools from OSAT partners of a leading advanced logic customer, as well as orders for other AI-related AP applications. The Group also secured repeat Chip-to-Wafer orders from a leading global integrated device manufacturer for advanced CPUs supporting client computing and AI inference.
The Group’s Photonics business had record bookings and revenue, driven by production ramps of 800G, 1.6T and next-generation optical modules addressing AI-related requirements for faster and more efficient data transmission. Its Pluggable Optical Transceiver solutions secured significant orders, reinforcing its lead in the transceiver market. Of note, the Group’s AMICRA business achieved a breakthrough bulk order for its Near-Packaged Optics solutions, and maiden orders from a leading communication services provider for its ultra-high-precision bonding solutions for optical transceivers. The Group continued to deepen its engagement with multiple leading global CPO players, positioning it well to gain market share as CPO adoption accelerates. All these demonstrate the breadth of the Group’s Photonics portfolio and create a multi-year growth opportunity.
AI-related demand also continued to support the SEMI mainstream business, particularly in power management and AI server-board applications for data centres. Revenue and bookings remained elevated, with wire bonding and die bonding tools supported by AI infrastructure expansion and high utilisation in OSATs. For the SMT segment, it achieved its third consecutive quarter of record bookings, and highest bookings market share, with demand driven largely by AI server boards and optical transceivers. Of note, bookings growth in the Americas accelerated on the back of strong demand for AI servers.
Outlook
The Group expects Q4 2026 revenue to be between US$670 million and US$730 million, up 4.6% QoQ and 37.5% YoY at mid-point of US$700 million, which is above the market consensus. This will be driven by double-digit SMT revenue growth, while SEMI revenue is expected to be flat due to longer lead times of AP products.
Q4 2026 bookings will remain significantly elevated YoY, supported by sustained AI infrastructure investment across both segments. The Group expects Q4 bookings to be below Q3’s record level due to the one-offs and pull-in in SMT.
Looking ahead, AI demand is expected to drive sustained revenue growth in 2027.
About ASMPT
ASMPT is a leading global supplier of hardware and software solutions for the manufacture of semiconductors and electronics. Headquartered in Singapore, ASMPT’s offerings encompass the semiconductor assembly & packaging, and SMT (surface mount technology) industries, providing various solutions that organise, assemble and package delicate electronic components into a vast range of end-user devices. ASMPT partners with customers very closely, with continuous investment in R&D helping to provide cost-effective, industry-leading solutions that achieve higher productivity, greater reliability and enhanced quality.
ASMPT is listed on the Stock Exchange of Hong Kong (HKEX stock code: 0522) and is one of the constituent stocks of the HKEX Tech 100 Index, Hang Seng Composite MidCap Index under the Hang Seng Composite Size Indexes, the Hang Seng Composite Information Technology Industry Index under Hang Seng Composite Industry Indexes, the Hang Seng Corporate Sustainability Benchmark Index, and the Hang Seng HK 35 Index. To learn more about ASMPT, please visit https://www.asmpt.com .
Forward-Looking Statements
All statements included herein, other than statements of historical facts, are or may be forward-looking statements. These forward-looking statements reflect ASMPT’s current expectations, beliefs, hopes, intentions or strategies regarding the future and assumptions in light of currently available information. Such forward-looking statements are not guarantees of future performance or events and involve known or unknown risks and uncertainties. Accordingly, actual results may differ materially from information contained in the forward-looking statements as a result of a number of factors. Readers should not place undue reliance on such forward-looking statements, and ASMPT does not undertake any obligation to update publicly or revise any forward-looking statements. Save as otherwise referred to below, no statement herein is intended to be or may be construed as a profit forecast.
- End –
For media enquiries:
Lim Ee Guan
Director, Corporate Communications
Tel: +65 6450 1445
Email: [email protected]
On behalf of ASMPT:
Strategic Financial Relations Limited
Mandy Go / Vivienne Leung / Angela Shen
Tel: +852 2864 4812 / 2864 4862 / 2864 4870
Fax: +852 2527 1196
Email: [email protected]
/ [email protected]
/ [email protected]
ASMPT Limited
Other news
-
Bassel Haddad Assumes Leadership of ASMPT as Group Chief Executive Officer
-
ASMPT Announces 2026 Interim Results Multiple Advanced Packaging Solutions Drive Strong Performance
-
ASMPT Secures Significant Wins for More than 50 Chip-to-Substrate Thermo-Compression Bonding Tools
-
ASMPT Announces 2026 First Quarter Results Strong Demand Driven by AI
-
ASMPT Announces 2025 Annual Results AI-Driven Structural Growth Underpins Group Performance
-
ASMPT Extends Technology Leadership With Key TCB AOR Chip-To-Wafer Milestone
-
ASMPT Announces Assessment of Strategic Options for SMT Solutions Segment
Corporate Information
ASMPT Group





Prompts
Click prompts to add them under the company line, click again to take one out, then copy the result into your AI chat. Shared by Asian Century Stocks and Uncovered Thai Stocks. Thank you.
Asmpt Limited (ticker 522), listed in Hong Kong.
Copied
ETFs Holding Asmpt Limited
Exchange-traded funds whose newest published daily portfolio holds one of the company's listings, largest weight first.
| ETF | Weight in ETF | Shares | Market value | As of |
|---|---|---|---|---|
| MCHS | 4.03% | 33,000 | $ 1.005M | Jun 30, 2026 |
| MEMS | 2.01% | 14,900 | $ 453.723K | Jun 30, 2026 |
| DARP | 0.46% | 10,626 | $ 125.278K | Nov 17, 2026 |
| REMG | 0.34% | 12,000 | $ 365.377K | Jun 30, 2026 |
| CGIC | 0.24% | 518,300 | $ 6.11M | Nov 16, 2026 |
| DFIC | 0.03% | 370,100 | $ 4.774M | Nov 12, 2026 |
| JSTC | 0.03% | 6,948 | $ 81.915K | Nov 17, 2026 |
| AVDE | 0.02% | 321,800 | $ 3.699M | Nov 16, 2026 |
| AVSD | 0.02% | 7,200 | $ 82.764K | Nov 16, 2026 |
| DFSI | 0.02% | 17,600 | $ 227.049K | Nov 12, 2026 |
| DFAX | 0.02% | 155,400 | $ 2.005M | Nov 12, 2026 |
| DFAI | 0.02% | 214,100 | $ 2.762M | Nov 12, 2026 |
| DFIV | 0.00% | 11,400 | $ 147.066K | Nov 12, 2026 |