Analyst and Investor Presentation Interim Results For the 6 Months Ended 31 August 2026 Vertu Advantages: Our Investment Case Scale Benefits • • • • Resilient Aftersales Stable, experienced management with capacity to manage further growth •…
Analyst and Investor Presentation
Interim Results
For the 6 Months Ended 31 August 2026
Vertu Advantages: Our Investment Case
Scale Benefits
•
•
•
•
Resilient Aftersales
Stable, experienced
management with capacity
to manage further growth
•
Dedicated franchise based
divisions with strong and
growing Manufacturer
partner relationships
•
Scale delivering synergies
including marketing and IT
Full sales and aftersales
offering to increase capture
of lifecycle vehicle spend
Retention focus with two
million customers on the
Group database and over
160,000 customers with high
retention service contracts
•
Delivery of above-sector
average customer experience
levels backed up by
extensive training and
technology
•
Driving higher ROI and
margin accretive revenue
streams
Growth opportunities
increasingly visible to allow
selective investment
5%
44%
Market share
New Cars & Vans
of gross profit from
aftersales
Cost Optimisation
•
Disciplined cost control;
controlling the controllables
•
In-house systems developed
to improve process
efficiency, aid decision
making and reduce costs
•
Single Vertu brand gives
efficiency
•
Effective marketing
investment delivers key
brand growth with optimised
ROI
•
Tech investment includes
growing, well controlled use
of AI to drive conversion and
efficiency in increasing
number of areas
Maximise Returns
•
Disciplined capital allocation
•
Active portfolio management
•
Sale of underperforming
businesses and surplus
assets
•
Property portfolio (£327m)
supported by valuation, half
of portfolio unencumbered
•
Transitioning to broader
Manufacturer partnerships
with new entrants from
China
•
19 years of trading profitably
since inception
9.9%
21.9%
Opex. as % of revenue
(H1 FY26: 10.0%)
shares bought back since
2018
2
At a Glance
Key themes:
Record Revenues: £2.60bn (H1 FY26: £2.51bn)
1
Adjusted Profit Before Tax : £23.8m (H1 FY26: £20.0m) - 19% up
Further upgrade announced making three upgrades to FY27 profit
delivered year-to-date
Free Cash Flow: £17.5m (H1 FY26: £0.4m)
2
Net Debt : £54.2m (28 February 2026: £61.3m)
ZEV mandate (car and van) pressure on
sector
Growth of Chinese OEM’s in market:
Portfolio reshaping rapidly: tariff threat
Consolidation – Evolution of Super
Groups
Tech developments including AI:
Helping cost and efficiency including
sales conversion
Better than expectations
Net Tangible Assets per share: 80.8p (28 February 2026: 75.9p)
1 Excludes non-underlying items
2 Excludes lease liabilities
3
Current Trading - September
•
Strong start to the second half across all areas of the business: Profit
above prior year levels (adjusted for prior year impact of JLR cyber attack)
with trading aided by a robust new car market
Like-for-like vehicle volume – September FY2027
Group Like-forlike % Change
UK % Change
1
(SMMT)
0.0%
+13.9%
•
Core Group profit rose in all channels
•
New car market showing strong growth driven by improved retail mix,
increased pre-registrations and impact of Chinese brands
New retail car and bikes2
Motability
+26.7%
+28.7%
Chinese brands (excluding Volvo) accounted for 24.5% of September UK
new retail market
Fleet car2
+2.8%
+5.1%
New commercial vans
(8.4%)
+4.8%
Like-for-like new retail volumes were level compared to prior year, UK
registrations grew by 13.9%
Total new vehicles
+3.0%
•
Reduced new van volumes as market shifted to more flexible, rental
contracts from longer term contract hire
Used vehicles - retail
+1.9%
Total vehicles sold
+2.6%
•
Motability market showing excellent growth as predicted
•
Operating expenses well controlled
•
•
Year-on-year movement in revenue
Core Group (exc. impact of JLR cyber attack)
gross profit movement: +£1.7m
+/- %
Total Revenue (Total Group)
0.0%
Total Revenue (Core Group)
+0.1%
Service Revenue (Total Group) 3
+1.7%
Service Revenue (Core Group) 3
+3.4%
59.1
Sep FY26
0.4
New
vehicles
0.5
Fleet and
Commercial
vehicles
0.6
0.2
Used
vehicles
Aftersales
2.3
63.1
JLR Cyber
Attack
Sep FY27
1 Source SMMT
2 includes agency volume
3 Includes internal and external revenue
4
Outlook
•
Full year results for the year ending 28 February 2027 are anticipated to be ahead of current expectations1
•
A number of self help measures being deployed:
• Expansion into new markets, such as ‘Value Cars’ by Vertu, growing sales volumes in the older car segment and
launch of Shariah law compliant used vehicle finance
• Role out of sales executive package changes to the Group’s premium franchise outlets. Changes already
implemented in volume franchise dealerships have improved sales performance and colleague retention
• Enhancement of technician remuneration to improve retention and recruitment and increase capacity in the high
margin aftersales business
• Cost control will be a key priority, with the Group planning to provide further cost efficiencies through the adoption of
technologies, energy saving systems and increasing use of data and sales attribution to increase the return on
investment from marketing spend
•
The ZEV mandate continues to negatively impact the sector through its impact on new vehicle pricing, channel mix and
vehicle supply. This pressure is likely to continue into 2030 even after revised ZEV mandate following consultation
•
Caution on consumer demand, uncertain due to rising inflation and interest rates
•
Opportunities for the further expansion of Chinese brands and wider acquisition opportunities are being assessed against
strict investment hurdle metrics
•
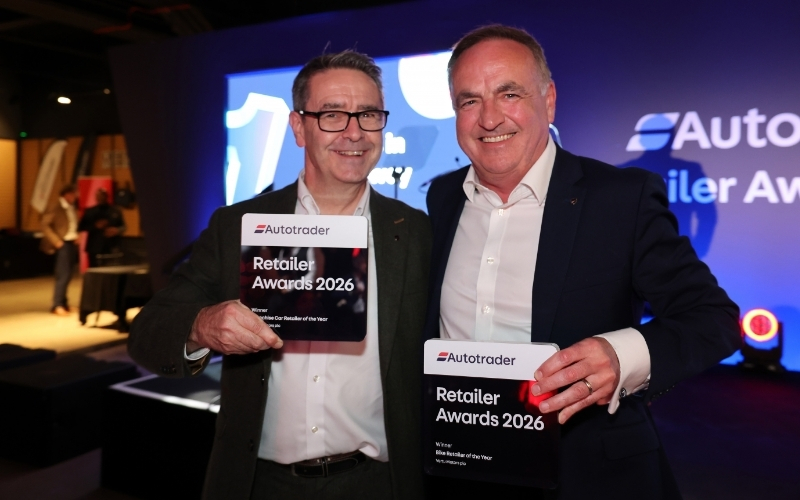
In October 2026 Group received key industry awards of Autotrader “Retailer of the Year” for the second year running and
“Bikes Retailer of the Year”
1
According to compiled data at 13 October 2026, the current consensus of three sell side analysts’ expectations for FY27. Adj usted profit before tax is £26.5m with a range of £25.5m to £27.1m.
5
Strategic Update
Robert Forrester CEO
Mission &
Values
Consistent Group Strategy
To aim for every dealership to be
the best retailer in their respective
town or city
To deliver an outstanding customer
motoring experience through
honesty and trust
Vertu Motors to be the most
admired and respected dealer
group in the automotive industry
PASSION RESPECT PROFESSIONALISM INTEGRITY RECOGNITION OPPORTUNITY COMMITMENT
Strategic Goals
Growth
To grow as a major scaled franchised
dealership group and to develop our portfolio
of Manufacturer partners, whilst being
mindful of industry development trends, to
maximise returns
Digitalisation
• Optimise omnichannel retail offering and
promote our brand to drive enquiry
levels
• Digitalise aftersales process
• Reduce cost base, deliver efficiency
through use of technology
Colleague & Customer Focus
Ancillary businesses
To develop and motivate the Group’s
colleagues to ensure consistency of
operational excellence and delivery to
customers across the business
To develop ancillary businesses to
add revenue and returns which
complement the core business
Sustainability
Goals
• Utilise data driven decision making to
enhance returns
Work with our Manufacturer partners
to provide increasingly sustainable
choices for customers
Reduce the environmental impact
of our business
Care for our colleagues and
support our communities
7
Evolving Competitive Landscape in New Vehicles
Chinese New Entrants
BEV & ZEV Mandate
BEV as % of Total UK Registrations (Source: SMMT)
January to August 2026
35.0%
25.6%
19.8%
11.6%
Private
•
•
Motability
Fleet
Total Car
Market
Battery electric vehicle (“BEV”) registrations grew strongly, reaching almost
356,000 units in the first eight months of 2026, a 25.6% calendar year-to-date
market share to the end of August.
Headline ZEV mandate targets for 2026 currently remain 33% for cars and
24% for vans
•
Vertu like-for-like BEV retail sales up 125.6% ahead of the Private market
growth of 75.9% (March to August)
•
In August 2026, the Government opened a formal review of the mandate,
seeking views on the annual target trajectory. Consultation remains open
until 23 October 2026
•
The ZEV mandate continues to negatively impact the sector through its
impact on Manufacturer pricing, channel mix and vehicle supply. This
pressure is likely to continue into 2030 even after revisions to the EV
Mandate following consultation
•
Rapid expansion of Chinese automotive Manufacturers remained an
important structural feature of the UK car market during the Period
•
Chinese production overcapacity and current tariff-free trade with UK
driving change; Chinese brands excluding Volvo represented 24.5% of the
September new retail market
•
New brands continued to broaden model choice across BEV, plug-in hybrid
and hybrid powertrains, supported by competitive pricing, strong technology
propositions and increasing retailer outlets
•
Growth is intensifying competition and contributing to pressure on both
pricing and established brand loyalty
•
Chinese brands engaging in significant short-cycle fleet and pre-registration
activity helping to drive overall UK new car market growth
•
Used car market impacted due as heavy discounting and highly competitive
finance are pricing new vehicles at or below the cost of used vehicles
•
UK Government appears to be considering applying EV tariffs to Chinese
made EV cars to gain access to “Made in EU” initiative
8
Portfolio Development
Growing Representation of Chinese Manufacturers*
15.1%
% = Chinese brands as % of outlets
9.3%
4.7%
31
9
18
182
176
31-Aug-25
31-Aug-26
Other Outlets
174
Anticipated by mid-2027
Chinese Outlets by Manufacturer
BYD
7
MG
5
Geely
5
iCaur
3
Leapmotor
2
Omoda
2
Jaecoo
2
Smart
2
LEVC
1
Denza
1
Chery
1
31-Aug-25
31-Aug-26
Anticipated by mid-2027
Chinese Owned Outlets
- Excludes Geely owned Volvo
9
Digitalisation
Other Strategic Actions
Selling Older Used Cars
Colleague & Customer Experience
“Controlling the controllables”
Cost Reduction and Control
Returns to Shareholders
Digitalisation
Opportune
vMax
FitBits
•
In the Period ‘Opportune’ piloted across 18
dealerships; extended to 52 dealerships in October
•
Group's new real-time sales performance sales
executive commission dashboard
•
‘Fit Bits’ parts performance dashboard, launched
across the Group on 1 August 2026
•
AI-enabled sales tool which analyses customer
telephone enquiries into the Group’s Centralised Sales
Experience Centre
•
Provides enhanced transparency, colleague
engagement and management oversight
•
•
Developed alongside the third party telephony provider
for the Group
•
vMAX shows the sales executives their earning
opportunity on next deal, what they have missed
out on previous deals and key performance
ratios
Centrally developed dashboard provides a
consistent view of key operational and financialcontrol measures across all of the Group’s parts
departments
•
Gamification elements within vMAX are driving
both greater sales effectiveness and higher sales
per sales executive. This has led to higher sales
team earnings
Tool introduces an element of gamification that
has increased engagement and local
accountability, while enabling central
management to identify operational deficiencies
•
Early improvements have been achieved in stock
management, strengthening control and reducing
operational and balance-sheet risk
•
Provides dealership sales colleagues with a tailored
summary, recommended actions and guidance on
potential objections and risks
•
Shows skills required to make a sale
•
Pilot Group have shown improved sales conversion
rate of 24.8%, an increase of 12.7% compared with
22.0% across a representative control group of
comparable, non-participating dealerships
•
11
Used Cars over 7 years old; performance since launch 1 April 2026
•
•
•
•
•
•
1,400+
£1,437
Additional 7 year+ Cars sold
Average GPPU
13% of Used Vehicles Sold up from 10%
+11% vs prior year
Route to market: selling over 7 year plus old cars
Revised preparation standard
Use of non-OEM parts in preparation
Finance available extended to 12 year-old cars
New warranty product developed
Crucially cars sourced by dealerships as ‘Value’ cars are not
transferrable to other sites
13.5%
Gross Margin
Compared to 6.9% in sales of <7 year old
cars
32 Days
Stock Turn
14 Days faster than <7 year old
Coming soon…
Shariah Law Compliant
Used Car Finance
12
Colleague & Customer Experience
Technicians
Sales Executives
Great Place to Work
Customer Experience
•
Stability of the Group’s overall
colleague base has improved over
the Period and engagement remains
high
Autotrader Retailer of the Year
2025 and 2026
•
85% of colleagues believe Vertu is a
“Great Place to Work”
+38%
Group Sales Executive
Turnover
53%
49%
46%
39%
Feb-25
Aug-25
Feb-26
Aug-26
▸ On 1 April, the Group introduced a new
Sales Executive remuneration
framework across its volume franchise
operations, increasing base salaries
and enhancing performance-related
earning opportunities
▸ New structure more closely aligns
•
•
colleague incentives with key
operational objectives including vehicle
volumes, finance penetration, product
sales and customer satisfaction
▸ Changes were launched alongside
“vMAX”
▸ Initiatives have helped reduce Sales
Executive turnover significantly
▸ Similar changes to Premium Sales
Executive packages will apply from 1
November
•
Group experienced an increase in
technician vacancies during the latter
part of the Period, in part due to
moves to increase the aftersales
capacity of the Group
Review of technician remuneration is
under way, with pay packages being
augmented to support retention,
recruitment and further growth in
aftersales capacity
These changes to Technician
remuneration will be implemented on
1 November 2026
•
•
Recognised as one of the UK’s Top
100 Apprenticeship Employers for
2026, emerging as the highestranked automotive retail group on
the list
Investment in degree apprentices,
technician apprentices and
graduates continue to feed talent
pipeline
New Car CSI v national average
+6%
Aftersales CSI v national average
85%
Used Car NPS (JudgeService)
13
Cost Reduction and Control
6-month period ended 31 August
£’m
Salary cost
2026
2025
Variance
Variance %
142.9
137.5
5.4
3.9%
Vehicle and valeting costs
27.8
27.7
0.1
0.4%
Property costs and depreciation
31.2
30.6
0.6
2.0%
Other (including IT)
27.5
26.1
1.4
5.4%
Marketing costs
21.4
20.7
0.7
3.4%
Share based payments and amortisation
1.9
1.9
252.7
244.5
8.2
3.4%
Core Group operating expenses
Core Group operating expenses as a
percentage of Core Group revenues
9.9%
10.0%
Acquisitions
3.4
0.0
3.4
Disposals
0.5
6.7
(6.2)
256.6
251.2
5.4
Group net underlying operating
expenses1
Operating expenses as a percentage of
revenues
1 Excludes non-underlying items
9.9%
10.0%
0.1%
2.1%
0.1%
•
Salary costs have increased due to the
following:
Higher Sales Performance driving
earnings
5.4
National Minimum Wage Change
1.3
Investment into Management Teams
0.9
National Insurance Costs
1.2
Headcount Savings
(3.4)
Salary Cost Movement
5.4
•
Marketing cost increase reflects additional
fleet introductory commission spend arising
from significant growth in Fleet volumes.
During the Period the Group delivered two
brand new Group wide new vehicle sale
events with significant marketing investment
•
Other costs have increased by £1.4m in the
Core Group, reflecting investment in IT
systems and AI along with inflationary
increases in other areas. These rises in part
allowed the Group to increase productivity and
deliver headcount savings
•
Disposals of poor performing dealerships has
reduced the cost base
•
Share based payments costs are level yearon-year despite a reduction in awards, due to
a decline in leaver rate: stability of
Management
14
Returns to Shareholders
Portfolio Management
•
•
•
Active portfolio management resulted
in a continued trend in the disposal of
surplus property assets at a premium
to book value
•
Group is progressively increasing its
opportunity with Chinese brands
reflecting the fundamental
transformation of UK car market
structure
Total net capital expenditure of £5.3m
in the Period, net of £1.6m sale
proceeds from surplus property
2.5m shares (0.8% of share capital in
issue at 1 March 2026) repurchased
for £1.8m in FY27 as at 30 th
September
•
Interim dividend increased 11% to
1.00p per share (H1 FY26: 0.90p)
•
Interim dividend will be paid on 15
January 2027
•
£10.2m remains of the £12m Share
Buyback programme announced in
March 2026
•
Policy of targeting full year cover on
adjusted diluted EPS of 2.5 – 3.5
times
•
Since the commencement of the
buyback programme in October
2018, and up to 30th September
2026, the Group has reduced its
issued share capital by 21.9%
•
1.05
1.5
2.35
2.05 2.05
1.7
1.6
0.6
FY26
FY25
FY24
FY23
FY22
FY20
FY19
FY18
0.8
1.4
FY17
0.7
1.3
FY16
Board committed to share buyback
programme at levels up to 5% more
than tangible net assets per share
(85p per share)
2.15
FY15
•
£4m (6.4m shares) purchased into
the Employee Benefit Trust in the
Period
Dividend Per Share History
FY14
Net capital expenditure of £21.6m
currently anticipated for FY27 which
includes planned expansion with
Chinese brands
Dividends
FY13
•
Share Buyback
15
Financial Performance
Karen Anderson CFO
Financial Highlights
Adjusted1 profit before tax for the Period of £23.8m (H1 FY26: £20.0m) up 19%
Record H1 revenues, with strong organic growth
Group like-for-like gross profit up £10.9m; with growth delivered in all channels
Group continued its strong focus on cost control with like-for-like operating expenses slightly down as a
percentage of revenue in the Period
Non-underlying items represent a net income of £0.4m due to a surplus property disposal at above net book value
Excellent cash conversion of 94.2%; cash flow from operating activities £32.5m from an operating profit of £34.5m
Group generated Free Cash Flow of £17.5m in the Period (31 August 2025: £0.4m)
Tangible net assets per share of 80.8p (28 February 2026: 75.9p)
New three-year banking facilities, with option to extend to five-years, reducing future financing costs
1 Excludes non-underlying items (non-underlying items in the Period were a net income)
17
Income Statement
6-Month Period Ended 31 August
£’m (unless otherwise stated)
2026
2025
% Change
Revenue
2,596.5
2,510.0
3.4%
Gross profit
290.6
282.2
3.0%
Gross margin %
11.2%
11.2%
Operating expenses
(256.6)
(251.2)
(2.1%)
Operating expenses as % of revenue
9.9%
10.0%
(0.1%)
Adjusted operating profit1
34.0
31.0
9.7%
Operating profit margin %
1.3%
1.2%
0.1%
Net finance charges
(10.2)
(11.0)
7.3%
Adjusted profit before tax
23.8
20.0
19.0%
Net non-underlying items
0.4
(0.5)
180.0%
Profit before tax
24.2
19.5
24.1%
Adjusted Basic EPS1 (pence)
5.71p
4.57p
24.9%
Dividend per share (pence)
1.00p
0.90p
11.1%
1
Revenue: £86.5m rise in revenues driven by
growth in the Core Group (+£106.0m) and the
impact of acquired businesses and start-ups
(+£29.5m). Closures and disposals during the
period resulted in a revenue reduction of
£49.0m
Gross Margin: Flat at 11.2%
Operating Expenses: Operating expenses as
a % of revenue decreased by 0.1% in the Core
and total. This reflects the strong focus of the
Group on cost control and the decisions taken
to prune underperforming businesses.
Operating Margin: Improved to 1.3% from
1.2% in prior year
Net Finance Charges: Overall reduction of
£0.8m is driven by a decrease in new vehicle
stocking charges and bank interest savings
Non-underlying items: Profit on disposal of
assets held for resale of £0.5m in the Period
has been shown as non-underlying income in
the Period, partially offset by dealership closure
costs
EPS: Growth of 24.9%
1 Excludes non-underlying items
18
Profit Bridge – Adjusted PBT
All values in £’million
Core Group Gross Profit Movement: +£10.9m
3.9
3.4
1.0
(3.9)(8.2)
2.6
0.8
0.3
23.8
20.0
Core Group
H1 FY26
Adjusted PBT
New vehicles
Fleet and
commercial
vehicles
Used vehicles
Aftersales
Core Group
operating
expenses
Finance Costs
Acquisitions,
start-ups and
disposals
H1 FY27
Adjusted PBT
1 Excludes non-underlying items
19
Balance Sheet
31 Aug 2026
£’m
28 Feb 2026
£’m
31 Aug 2025
£’m
136.3
136.6
137.3
Retirement benefit asset
3.6
3.6
3.7
Right-of-use assets
86.4
88.7
93.7
Tangible assets
350.9
354.0
357.8
Non-current assets
577.2
582.9
592.5
Current assets
879.4
898.6
883.6
Property assets held for sale
3.6
4.5
Cash and cash equivalents
78.0
Total assets
•
Tangible net assets per share of 80.8p, up from 76.1p
(6.2%).
•
Freehold and long leasehold property portfolio at
depreciated historic cost of £327m within tangible assets
•
Desktop valuation recently performed by Knight Frank
indicates support of property values at current net book
value: 54% of portfolio unencumbered by mortgages
5.1
•
Net Debt1 of £54.2m (FY26: £61.3m)
73.1
58.5
•
1,538.2
1,559.1
1,539.7
Current liabilities
(903.9)
(934.1)
(900.5)
One of the two properties assets held for sale at 28 Feb
2026 sold in March 2026 for £1.5m, generating a profit on
disposal of £0.5m
Non-current liabilities
(37.6)
(35.1)
(34.5)
•
Lease liabilities
(96.6)
(98.0)
(103.9)
New vehicle stock declined due to reduced pipeline of
stock funded by Manufacturer facilities with no cash impact
Borrowings
(132.2)
(134.4)
(136.8)
Net assets
367.9
357.5
364.0
Tangible net assets
247.3
235.1
241.3
Tangible net assets per share
(pence)
80.8
75.9p
76.1
Intangible assets
1 Excludes lease liabilities
Vehicle Inventory
Variance (Aug
26 v Feb 26)
£’m
31 Aug 2026
£’m
28 Feb 2026
£’m
New vehicles
509.5
579.4
(69.9)
Demonstrators
41.9
42.1
(0.2)
Used vehicles
185.9
174.3
11.6
737.3
795.8
(58.5)
20
Net Debt & Refinancing
Current
Facilities
£’m
Net Debt at 31
August 2026
£’m
20 year mortgage facility (from December 2020)
9.2
9.2
20 year mortgage facility (from December 2022)
60.8
60.8
10 year mortgage facility (from December 2024)
6.3
6.3
76.3
76.3
5 year revolving facility (from October 2026)
70.0
55.9
1 year working capital facility (from May 2026)
48.0
Used vehicle stocking loans
70.0
Total committed facilities
264.3
132.2
Uncommitted accordion facility (from October 2026)
50.0
Cash
Overdraft
Total facilities
(78.0)
5.0
319.3
Net Debt (excluding lease liabilities)
54.2
Lease liabilities
96.6
Total Net Debt including lease liabilities
150.8
• In October 2026, the Group agreed the renewal of its
revolving credit facility, replacing the existing £93m
acquisition-only facility which was due to expire in
December 2027
• New facility comprises a £70m revolving credit facility for
general commercial purposes, together with a £50m
accordion to retain capacity for future acquisitions
• These two facilities have an initial three-year term, with
options to extend for up to a further two years
• Broader purpose of the facility will allow the Group to
repay and redraw funds as cash and working capital
requirements change on a seasonal basis, improving
treasury efficiency while maintaining committed liquidity
and strategic flexibility
• The new facility reduces the margin payable by 0.25% on
previous levels
• Refinancing expected to save c.£0.5m in annualised
finance costs: c.£0.1m in FY27, with the full benefit
thereafter
• c.60% of Group debt is long-term property backed
mortgages with no covenants
21
Free Cash Flow, Net Debt and Gearing
Cash Flow 6 Months Ended
31 August
2026
£’m
2025
£’m
Operating profit
34.4
30.6
Depreciation, amortisation and impairment
21.9
20.6
Profit on sale of assets
(0.5)
(0.9)
Working capital
(11.0)
(21.2)
Share based payments
1.4
1.4
Interest and taxation
(13.7)
(14.5)
Net cash flow from operating activities
32.5
16.0
Net Debt1: £54.2m (FY26: £61.3m)
Gearing1: 15% (FY26: 17%)
Free Cash Flow: £17.5m (H1 FY26: £0.4m)
Very strong cash conversion at 94%
1 Net Debt (excluding lease liabilities)/Shareholders funds
32.5
(4.1)
(10.9)
17.5
(1.2)
(3.5)
(5.3)
(0.4)
Net cash flow from Net sustaining capital
operating activities
expenditure
All values in £’m
Lease principal
repayments
Free Cash Flow
Enhancement capital
expenditure
Dividends paid
7.1
Repurchase of own Non cash movement Decrease in Net Debt
shares/sale of
in borrowings
(excluding lease
treasury shares (inc.
obligations)
EBT)
22
Trading and
Operational Update
New Vehicle Sales Performance
H1 FY27
Volume 2
Group LikeUK % Change
for-like %
1
(SMMT)
Change
Group Likefor-like v
SMMT %
New retail car and bikes 3
21,686
8.8%
13.1%
(4.3%)
Motability
9,564
11.6%
10.7%
0.9%
Fleet car3
20,704
30.5%
8.4%
22.1%
New commercial vans
8,286
(3.7%)
5.7%
(9.4%)
Total new vehicles
60,240
13.7%
Like-for-like unit % growth
Like-for-Like New Vehicle Volume 6 months to 31 August 2026
Like-for-like new retail unit growth/(decline)
versus UK market
1.5%
New retail car and bikes4
Core Group
2.5%
(11.2%)
H1 FY25
H2 FY25
H1 FY26
H2 FY26
H1 FY27
UK Private Registrations
Group2 Share of UK Market H1 FY27
New fleet & vans
H1 FY27
+/- v H1
FY26
H1 FY27
+/- v H1
FY26
26,025
(322)
26,969
(2,310)
Gross profit £’m
58.8
+3.4
28.5
+1.0
Gross profit per unit £
1,913
(55)
984
(142)
Gross margin %
8.0%
+0.4%
4.6%
(0.4%)
Selling price per unit (£)
8.8%
(1.5%)
(3.2%)
(5.5%)
Like-for-like Retail
Like-for-Like New Vehicle KPI’s 6 months to 31 August 2026
4.0%
6.6%
13.1%
New retail car
Motability
Fleet car
New vans
4.5%
5.8%
4.1%
4.9%
(FY26: 4.8%)
( FY26: 5.8%)
( FY26: 3.4%)
(FY26: 5.4%)
1 Source: SMMT
2 Total Group
3 includes agency volume
4 includes agency & Motability volume
24
Used Vehicle Sales Performance
Core Group
H1 FY27
H1 FY26
+/-
+/- %
Revenue (£’m)
987.6
971.3
16.3
1.7%
Gross profit (£’m)
72.3
69.7
2.6
3.7%
Gross margin %
7.3%
7.2%
+0.1%
Volume (units)
47,470
45,787
1,683
3.7%
Gross profit per unit (£)
1,522
1,517
+5
0.3%
•
Vertu Value Cars launched 1 April 2026 to
grow used car performance and retail older
used vehicles previously traded outside the
Group
•
Core Group used vehicle performance ahead
of prior year aided by the positive impact of
Value Cars
•
Average sales prices declined 2.5% (£535)
compared to H2 FY26
•
Core Group gross profit up £2.6m year-onyear on a like-for-like basis with growth in
volume and margin
•
Group saw higher Core Group gross margin %
of 7.3% reflecting reduced used van mix and
Value Cars impact. This offset weaker margin
in Premium large SUV segment which was
impacted by higher fuel prices
2.0%
Selling price per unit
3.9%
(3.0%)
(0.5%)
1.0%
3.7%
21,580
20,425
20,634
21,057
20,977
21,318
20,783
H1 FY24
H2 FY24
H1 FY25
H2 FY25
H1 FY26
H2 FY26
H1 FY27
(5.7%)
Units
Units +/- %
Selling price per unit £
Like-for-like movement in used units and Group selling price per unit
25
Group Aftersales Performance
Core Group
H1 FY27 v H1 FY26
1
Revenue (£’m)
1
Service
Parts
116.5
149.6
Accident &
Smart Repair
Fuel Forecourt
15.6
6.9
Total
288.6
Revenue change %
2.9%
3.9%
(0.4%)
33.2%
Gross profit (£’m)
85.7
31.7
10.0
0.6
128.0
Gross profit increase (£’m)
2.5
1.1
0.2
0.1
3.9
2
73.6%
21.2%
64.2%
8.6%
44.4%
2
0.1%
(0.1%)
1.4%
(0.1%)
(0.3%)
Gross margin %
Gross margin % change
3.8%
•
Strong growth in Service aided by higher number of customers taking Vertu Pay Later options, helping drive up conversion of a ddon
work and increased average invoice value
•
Part departments have benefited from the additional Service revenue as well as market share gains in trade parts operations
•
Group has 160,000 live service plans and more than 50,700 Motability vehicles under contract, the Group has a highly resilient
aftersales revenue base
•
Decline in number of accidents has negatively impacted Accident & Repair revenues. This is offset by enhanced growth in Smar t
repair operation at improved margins
1 Includes internal and external revenue
2 Margin in aftersales expressed on internal and external revenue
26
Group Well Positioned
Group stable, well-capitalised and asset backed
Firepower and ambition to further expand operations and scale
Digitalisation gathering pace in impact, benefiting customers and productivity
People-focus provides talented, motivated colleagues to serve customers
Group excited to benefit from pace of change and high level of opportunities
27
Appendices
Definitions of Key Terminology
Core:
Comparison against FY26
Dealerships that have traded for the full period of March 2025 to August 2025 and March 2026 to August 2026
Like-for-like:
Dealerships that have comparable trading periods in two consecutive financial years, only the comparable period is measured as “like-for-like”
FY27:
The twelve month period ended 28 February 2027
FY26:
The twelve month period ended 28 February 2026
FY25:
The twelve month period ended 28 February 2025
H1 FY27:
The six month period ended 31 August 2026
H1 FY26:
The six month period ended 31 August 2025
H1 FY25:
The six month period ended 31 August 2024
29
New Vehicle Trends (Retail and Motability)
H2
FY24
H1
FY25
H2
FY25
H1
FY26
H2
FY26
H1
FY27
Selling price per unit [1] (£)
25,906
25,338
26,180
26,064
26,155
25,497
26,045
Gross profit per unit [1] (£)
2,170
2,019
1,965
1,984
1,948
1,857
1,908
Margin (Group) [1]
8.5%
8.0%
7.6%
7.7%
7.6%
7.6%
7.9%
Margin (Core Group) [1]
8.2%
7.8%
7.6%
7.9%
7.7%
7.7%
8.0%
Like-for-like unit (Retail) growth/(decline)
1.1%
(4.1%)
(5.5%)
(1.5%)
1.5%
2.5%
8.8%
UK private registrations [2] growth/(decline)
1.4%
(3.7%)
(11.2%)
(3.2%)
4.0%
6.6%
13.1%
Like-for-like unit % growth
H1
FY24
Like-for-like new retail unit growth/(decline) versus UK market
20.0%
10.0%
1.1%
1.5%
1.4%
4.0%
2.5%
6.6%
8.8%
13.1%
0.0%
(4.1%)
(10.0%)
(3.7%)
(20.0%)
H1 FY24
H2 FY24
(5.5%)
(1.5%)
(3.2%)
(11.2%)
H1 FY25
Like-for-like Retail
H2 FY25
H1 FY26
H2 FY26
H1 FY27
UK Private Registrations
[1] Includes Motability sales
[2] Source SMMT
30
Fleet and Commercial Vehicle Trends
H1
FY24
H2
FY24
H1
FY25
H2
FY25
H1
FY26
H2
FY26
H1
FY27
Selling price per unit (£)
27,085
28,196
29,288
29,806
29,274
27,798
26,968
Gross profit per unit (£)
1,160
1,296
1,272
1,194
1,124
981
984
Margin (Group)
5.1%
5.6%
5.2%
5.4%
5.0%
4.5%
4.6%
Like-for-like unit growth (Fleet)
9.9%
14.0%
6.6%
3.1%
16.6%
24.6%
30.5%
UK car fleet registrations[1] growth
36.3%
18.2%
9.7%
3.8%
13.5%
11.9%
8.4%
Like-for-like unit growth/(decline) (Vans)
6.2%
(11.0%)
(15.0%)
(2.0%)
(9.4%)
(14.2%)
(3.7%)
UK van commercial registrations[1]
growth/(decline)
19.8%
18.8%
2.0%
(2.1%)
(9.4%)
(7.6%)
5.7%
[1 ] Source SMMT
31
Used Vehicle Trends
H1
FY24
H2
FY24
H1
FY25
H2
FY25
H1
FY26
H2
FY26
H1
FY27
Selling price per unit (£)
21,580
20,425
20,634
21,057
20,977
21,318
20,783
Gross profit per unit (£)
1,535
1,296
1,490
1,455
1,487
1,414
1,512
Margin (Group)
7.1%
6.3%
7.2%
6.9%
7.1%
6.6%
7.3%
Margin (Core Group)
7.4%
6.9%
7.3%
7.0%
7.2%
6.8%
7.3%
Like-for-like unit growth/(decline)
(5.7%)
2.0%
3.9%
(3.0%)
(0.5%)
1.0%
3.7%
2.0%
3.9%
21,580
20,425
20,634
H1 FY24
H2 FY24
H1 FY25
(5.7%)
(3.0%)
(0.5%)
1.0%
3.7%
21,057
20,977
21,318
20,783
H1 FY26
Units
H2 FY26
H1 FY27
H2 FY25
Selling price per unit
Units +/- %
Selling price per unit £
Like-for-like movement in used units and Group selling price per unit
32
Vehicle Volumes Sold
H1 FY27 vs H1 FY26
+/- %
Total units sold
16,457
16,085
Used Trade
47,799
48,164
Used Retail
Total Fleet Car
1
15,800
20,704
Used Trade
+0.8%
Used Retail
New Commercial
8,626
8,286
(3.9%)
New Motability
8,638
9,564
+10.7%
Total New Retail
1
117,570
124,489
Total Volumes
H1 FY26
1 Includes agency volume
+7.1%
20,250
21,686
H1 FY27
Like-for-like units sold
(2.3%)
+31.0%
+5.9%
H1 FY27 vs H1 FY26
+/- %
Total Fleet Car
15,807
15,833
+0.2%
45,787
47,470
1
+3.7%
+30.5%
SMMT +8.4%
15,773
20,586
New Commercial
8,597
8,276
(3.7%)
SMMT +5.7%
New Motability
8,408
9,380
+11.6%
SMMT 10.7%
Total New Retail
1
+8.8%
SMMT +13.1%
19,596
21,318
113,968
122,863
Total Volumes
H1 FY26
+7.8%
H1 FY27
33
Dealership Portfolio
196 sales outlets
Group
Stellantis
BMW
Ford
Nissan
Renault
Honda
Volkswagen
Group
Hyundai
Brand
Vauxhall
Peugeot
Citroen
Leapmotors
BMW
MINI
BMW Motorcycles
Ford
Nissan
Renault/Dacia
Alpine
Honda
Honda Motorcycles
Volkswagen
Skoda
SEAT/Cupra
Ducati Motorcycles
Volkswagen Commercial Vehicles
Audi
Hyundai
Kia
Kia PBV
Sales
Outlets
15
9
4
2
7
7
4
16
13
11
1
14
2
8
5
3
1
1
1
11
4
1
Group
JLR
Toyota
Mercedes
Geely
BYD
Mazda
Chery
Ferrari
Brand
Land Rover
Jaguar
Toyota
Mercedes-Benz
Mercedes-Benz Commercial Vehicles
Volvo
Geely
SMART
LEVC
BYD
Mazda
MG
Omoda
Jaecoo
Ferrari
Sales
Outlets
10
1
11
5
1
5
4
1
1
5
3
4
2
2
1
34
Disclaimer
This presentation contains forward looking statements. Although the Group believes that the estimates and
assumptions on which such statements are based are reasonable, they are inherently uncertain and involve a
number of risks and uncertainties that are beyond the Group’s control.
The Group does not make any representation or warranty that the results anticipated by such forward looking
statements will be achieved and this presentation should not be relied upon as a guide to future performance.