FSG
Fiscal year ends March Quarters are offset from the calendar — Q1 is Apr–Jun

Foresight Group Holdings Limited is an investment manager operating a diversified platform of strategies and funds spanning private and public markets. The company is structured into two main divisions: Real Assets and Private Equity. The Real Assets division focuses on energy transition, natural capital, and social, transport, and digital infrastructure, managing a portfolio of real assets across Europe and Australia. The Private Equity division invests in growing companies in the UK and Ireland, supporting businesses from start-up to exit. The firm offers public market strategies and investment trusts providing access to private infrastructure and renewable energy assets. Additionally, Foresight provides tax-efficient investment solutions for retail investors, including Enterprise Investment Schemes (EIS) and Venture Capital Trusts (VCTs). The company manages assets in green energy infrastructure and backs emerging opportunities in technology, land, and water.

Summarised from the company's own disclosures, fiscal year ended Mar 2026

Industry Asset Management Homepage foresight.group
Sector Financial Services IR page foresight.group/strategies-funds/tax-efficient-investing
Tags
real assets, private equity, venture capital, renewable energy, infrastructure, investment trusts, tax-efficient investing, eis, vcts, energy transition, Foresight Group LLP, ATL Turbine Services, Barnes Aerospace, Mulberry Bush Nursery Group, Kondinin Wind Farm, Golf's Greatest Holes
Press page foresight.group/news-insights/news

Metrics

Valuation  
Market cap £ 571.38M
Market cap (USD) $ 755.74M
P/E 12.48
PEG 0.51
P/BV 6.00
P/S 3.46
P/OCF 12.35
P/FCF 13.65
Dividend yield 5.4%
Turnover / mcap —
Returns  
ROE 47.4%
ROI 44.9%
ROIC 47.9%
Profit margin 26.0%
Growth  
Revenue growing Yes
Profits growing Yes
Revenue up 3y Yes
Revenue up 5y Yes
Earnings growth 3y (net profit CAGR) 24.5%
Quality  
Profitable Yes
Margin expanding Yes
Buying back stock Yes
Diluting (TTM) No
Debt/Equity 0.13%
Podcast bulls (TTM) Sign up
Podcast bears (TTM) Sign up
Podcast sentiment (TTM) Sign up
Podcast sentiment % (TTM) Sign up
News sentiment (TTM) 9
Quality score 61.1%
Insiders  
Buys, 1w Sign up
Buys, 1m Sign up
Buys, 1y Sign up
Sells, 1w Sign up
Sells, 1m Sign up
Sells, 1y Sign up

Sign up to see this company's insider trades

Figure FY 2026 FY 2025 FY 2024 FY 2023 FY 2022 FY 2021
Revenue 164.919M 153.989M 141.326M 119.155M 86.071M 69.098M
Net profit 42.831M 33.245M 26.434M 23.625M 25.076M 15.174M
Free cash flow 41.854M 43.089M 43.884M 50.742M 24.668M 16.325M

Figure FY 2026 FY 2025 FY 2024 FY 2023 FY 2022 FY 2021
Share price 4.05 3.59 4.61 4.41 — 4.2
Price performance 12m 0.13 -0.22 0.05 — — —

Filed figures

Figure Mar 2020 Mar 2021 Mar 2022 Mar 2023 Mar 2024 Mar 2025 Mar 2026
Balance sheet detail
Trade receivables (GBP) — 16.5M 17.9M 19.1M 27.5M 37.5M 42.6M
↳ YoY growth +9.0% +6.7% +43.6% +36.6% +13.5%
↳ 5y CAGR +20.9%
Borrowings, current (GBP) — 688,000 660,000 2.65M 121,000 138,000 130,000
Borrowings, non-current (GBP) — 3.64M 3.03M 485,000 388,000 242,000 122,000
Lease liabilities (GBP) — 12M 10.4M 9.25M 7.26M 19.1M 30.9M
Cash and deposits (GBP) 13M 39.4M 54.3M 39.8M 45M 43.3M 41.8M
Intangible assets (GBP) — 3.01M 4.43M 62.9M 61.4M 53.4M 51.6M
Right-of-use assets (GBP) — 9.12M 8.26M 7.28M 5.77M 16.5M 26.1M
Net debt (borrowings + leases - cash) (GBP) — -23.1M -40.2M -27.4M -37.2M -23.8M -10.6M
Cash flow detail
Operating cash flow (GBP) — 16.5M 25.1M 51.4M 44.7M 44.1M 46.3M
Purchases of property, plant and equipment (GBP) — -141,000 -398,000 -619,000 -790,000 -1.03M -4.41M
Purchases of intangible assets (GBP) — -48,000 -171,000 -13,000 -5,000 -1.4M -1.39M
Change in receivables (cash effect) (GBP) — -4.53M -222,000 2.77M -6.92M -10.2M -1.38M
Change in payables (cash effect) (GBP) — 3.59M 2.55M 7.75M -238,000 9.44M -2.34M
Dividends paid (cash effect) (GBP) — -18.2M -6.18M -16M -25.8M -26.5M -28.4M
Share buybacks (cash effect) (GBP) — -10,000 0.00 -275,000 -1.43M -16.6M -19.1M
Income taxes paid (cash effect) (GBP) — -174,000 -3.4M -3.62M -5.08M -12.7M -9.61M
Share-based compensation (GBP) — 35,000 459,000 10.7M 13.7M 5.73M 3.85M
Operating cash flow before change in receivables (GBP) — 21M 25.3M 48.6M 51.6M 54.3M 47.6M
Free cash flow (OCF - PPE - intangibles) (GBP) — 16.3M 24.5M 50.7M 43.9M 41.7M 40.5M
Income detail
Total comprehensive income (GBP) — 14.9M 24.9M 20.9M 24.8M 32M 44.8M
Reported Jul 28, 2022 Jul 28, 2022 Jul 28, 2022 Jul 5, 2023 Jun 28, 2024 Jun 26, 2025 Jun 30, 2026

Operating KPIs — quarters

KPI Sep 21 Sep 22 Mar 23 Sep 23 Mar 24 Sep 24 Mar 25 Sep 25
Assets under management (GBP) 8.13B 12.5B 12.2B 12.2B 12.1B 12.4B 13.2B 13.7B
↳ YoY growth +20.2% +53.5% -2.3% -0.8% +1.6% +9.1% +10.5%
Reported — — — — — — — —

Operating KPIs — years

KPI Mar 2023 Mar 2024 Mar 2025
Assets under management (GBP) 12.2B 12.1B 13.2B
↳ YoY growth -0.8% +9.1%
Reported — — —

Sign up to see institutional holdings

Sign Up

Podcast Mentions

Sign up to see podcast mentions and sentiment

Sign Up

Home News & Insights News Foresight Energy Infrastructure Partners II partners with Gilkes Energy via strategic investment into Earba Pumped Storage Hydro

Foresight today announces that Foresight Energy Infrastructure Partners II SCSp (“FEIP II”), has made a significant investment in Gilkes Energy’s Earba Pumped Storage Hydro (PSH) project. Earba is a 1.8 GW / 40 GWh long-duration energy storage project in the Scottish Highlands and one of the largest PSH projects currently under development in the UK.

This investment will provide capital and long-term support to advance the next phase of the project as it progresses towards construction and delivery. The investment will also support detailed engineering, procurement, site investigations and preparations for construction.

With an installed capacity of 1.8 GW and energy storage capacity of 40 GWh, Earba will provide the equivalent of 22 hours of full-power export. The project will play an important role in balancing the electricity system, storing renewable power when generation exceeds demand and releasing power back to the grid when additional electricity is required. The project on average generates electricity to power more than 1.4 million UK homes.

The investment comes at a pivotal time for the UK’s energy transition. As the electricity system incorporates increasing volumes of intermittent renewable generation, large-scale, long-duration storage will be critical to maintaining system flexibility, strengthening security of supply and reducing reliance on fossil-fuel generation.

Earlier this year, Earba reached a significant milestone with its inclusion in Ofgem’s Minded-to Decision under the first application window of the UK Government’s Long Duration Electricity Storage (“LDES”) cap and floor scheme. Earba is the largest PSH project included in Ofgem’s Minded-to Decision in terms of both installed capacity and stored energy, underlining its strategic importance to the future UK electricity system. Ofgem is expected to publish its final decisions for the first LDES cap and floor window in autumn 2026.

The project is also expected to generate significant economic activity during its construction and operation, including employment opportunities and investment in the local and regional supply chain.

Carl Crompton, Managing Director of Gilkes Energy, said: “We are delighted to welcome Foresight as a strategic investor in the Earba PSH project. Their long-term approach to infrastructure investment and experience across the energy transition sector make them an excellent partner for this nationally significant project.

“Earba is widely recognised as one of the most economically viable and deliverable LDES projects, and has the potential to make a major contribution to the UK’s energy security and net-zero ambitions. Foresight’s investment provides further momentum as we progress the project towards construction and continue to work with our delivery partners to bring this transformational infrastructure project forward.”

Ben Field, Investment Director at Foresight, said: “We are delighted to be partnering with Gilkes Energy to advance Earba, one of the UK's most strategically important long duration energy storage projects. As renewable generation continues to scale, assets such as Earba will play a critical role in providing the flexibility, resilience and system stability needed to support a decarbonised power system. Building on Foresight's extensive experience of developing and managing essential infrastructure, we look forward to working alongside Gilkes Energy to bring the project through development and into operation, helping to strengthen the UK's energy security and accelerate the energy transition.”

The investment strengthens Earba’s position as one of the UK’s leading long-duration electricity storage projects and supports the delivery of critical energy infrastructure in Scotland.

Learn more about FEIP II here

Show Filters

[Foresight Energy Infrastructure Partners II completes acquisition of Nivala BESS from Fotowatio Renewable Ventures

Energy Transition Infrastructure Real Assets Private Markets

News
\

Foresight Energy Infrastructure Partners II completes acquisition of Nivala BESS from Fotowatio Renewable Ventures\


15 Oct 2026](https://foresight.group/news-insights/news/2026/foresight-energy-infrastructure-partners-ii-completes-acquisition-of-nivala-bess-from-fotowatio-renewable-ventures/)

[Flood Resilience Starts Upstream: Natural Capital as Essential Infrastructure

Insights
\

Flood Resilience Starts Upstream: Natural Capital as Essential Infrastructure\


12 Oct 2026](https://foresight.group/news-insights/insights/2026/flood-resilience-starts-upstream-natural-capital-as-essential-infrastructure/)

[Energy Security, Resilience and the Next Phase of Europe's Energy Transition

Featured Energy Transition Real Assets Private Markets Homepage feature

Video
\

Energy Security, Resilience and the Next Phase of Europe's Energy Transition\


06 Oct 2026](https://foresight.group/news-insights/insights/2026/energy-security-resilience-and-the-next-phase-of-europes-energy-transition/)

You have viewed 3 of 40

Load More

Richard Roberts, Head of Sales Development, discusses how advisers can respond to the cut in upfront Venture Capital Trust (VCT) income tax relief from 30% to 20% - from rebalancing the multi-year portfolios of existing shareholders to setting realistic expectations for clients investing for the first time.

Home News & Insights Insights How to strengthen VCT portfolios in a changing market
VCT investors broadly fall into two camps: existing shareholders, many of whom have subscribed across multiple tax years, and those with no VCT holdings at all. With upfront income tax relief now 20% rather than 30%1, advisers need to think carefully about how allocations should differ for each.

Rising concentration risk

Diversification has always mattered in VCT portfolios. Generalist managers often share similar investment criteria, so the most exciting companies attract more than one deal team. It’s not uncommon to find meaningful overlap in sectors, business types and even individual companies across two or more generalist VCTs.

Lower relief may increase that risk. It is widely expected to affect fundraising, and when capital is less plentiful, managers tend to prioritise liquidity commitments to shareholders and follow-on funding for existing investee companies. The focus shifts towards existing portfolios and away from new holdings.

The new investment limits cut both ways

Since April 2026, the limits on the companies VCTs can invest in have doubled1. Managers can now back larger, better-funded businesses and support them for longer. Follow-on investment in strong performers becomes more attractive, but advisers should watch for too much value building up in one or two holdings. A write-down in a large position would have a marked effect on net asset value (NAV).

Combined with a less forgiving risk and reward balance, this is likely to draw advisers towards established managers with stronger return profiles, larger cash reserves and a proven record in difficult markets. The irony is that a flight to quality can itself add concentration for existing clients. Strong due diligence and a clear view of what each VCT actually holds are the best defence. Advisers who can show how each holding complements the others will be better placed to explain their recommendations.

Reviewing an established portfolio

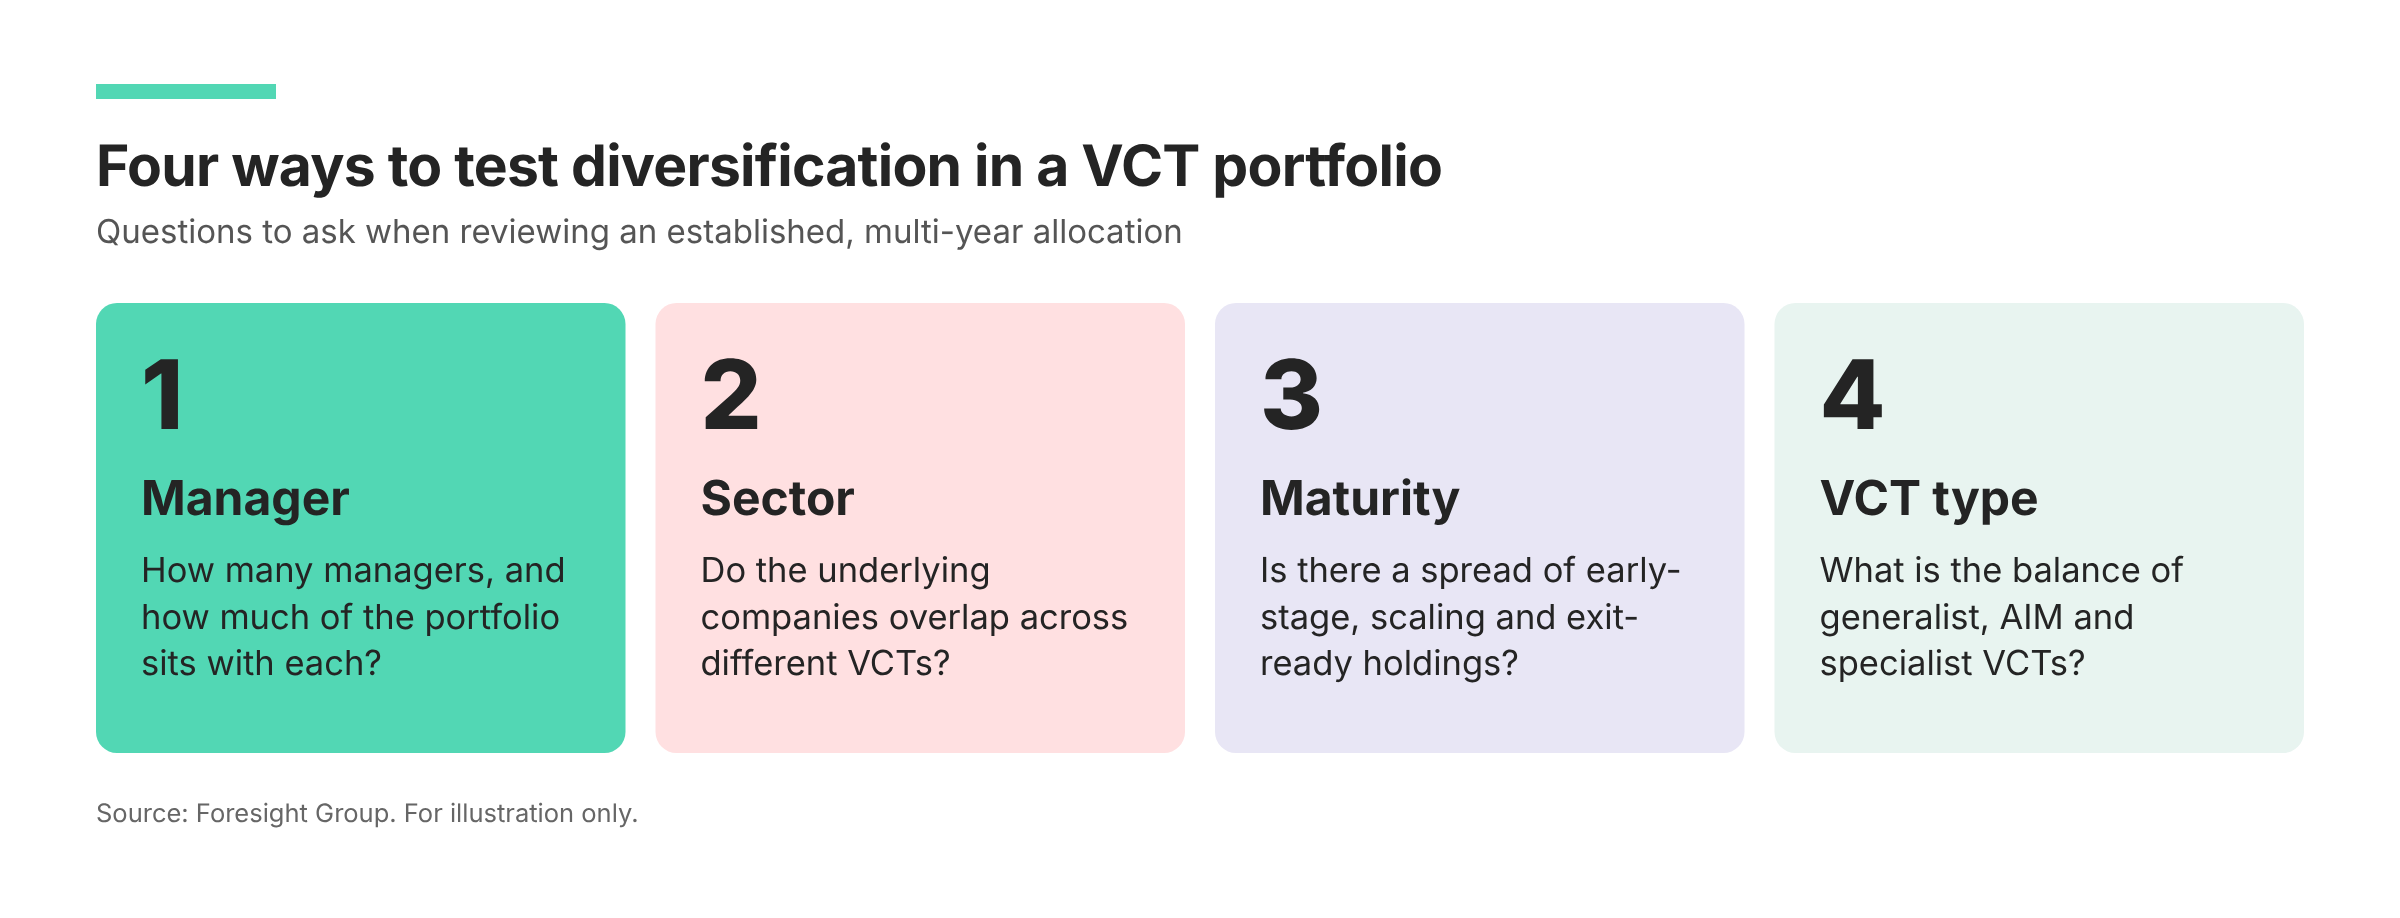
All of this points to a growing need to review multi-year portfolios, with a particular focus on manager concentration, sector exposure and dividend history. A useful starting point is to look through to the underlying companies across every VCT a client holds, then ask how much of the total sits with a single manager, in a single sector or in a handful of large positions. Cash levels and recent buyback activity are also worth checking, as both indicate how well a VCT can meet its commitments if fundraising slows.
Two practical constraints apply. Selling within five years means repaying the upfront income tax relief, and exits typically depend on the manager’s share buyback policy, with buybacks usually priced at a discount to NAV.

Where changes are recommended, advisers should keep the Consumer Duty in mind. Clients need to understand the revised strategy, how it goes beyond upfront relief, and what each new holding is intended to achieve.

Where specialist VCTs still have a role

Specialist VCTs have long been a way to add different sectors, growth stages or return drivers to a generalist allocation. That equation has changed. Their smaller size may make fundraising harder in current conditions, which increases the risk for investors.

They may still suit some clients, most likely those with VCT experience and a higher tolerance for risk. A broad generalist mandate can make it harder for a manager to build the depth of expertise needed to source and assess deep-tech opportunities, so the best results in those areas often come from a specialist. Two factors are worth weighing:

  • Sector concentration. Specialist VCTs offer higher potential returns but concentrated exposure, so they should be assessed in the context of the client’s whole portfolio
  • Manager scale and experience. A well-capitalised manager with access to specialist expertise and stable teams is better placed to support smaller, riskier companies through a difficult fundraising market

Why maturity matters

Holding companies at different stages of development helps to stagger exits, which can keep growth and income more regular. For a specialist VCT, portfolio maturity can be decisive. A portfolio with assets approaching an exit is less reliant on fresh fundraising to keep its companies funded, and new shareholders gain exposure to existing assets from day one. Dividends from specialist VCTs tend to follow realisations, so they are likely to be irregular and are not guaranteed.

First-time investors start from a different place

Existing investors approaching or in retirement are generally looking for tax-free dividends to supplement their income. New investors should probably treat VCTs as a hybrid of income and growth.
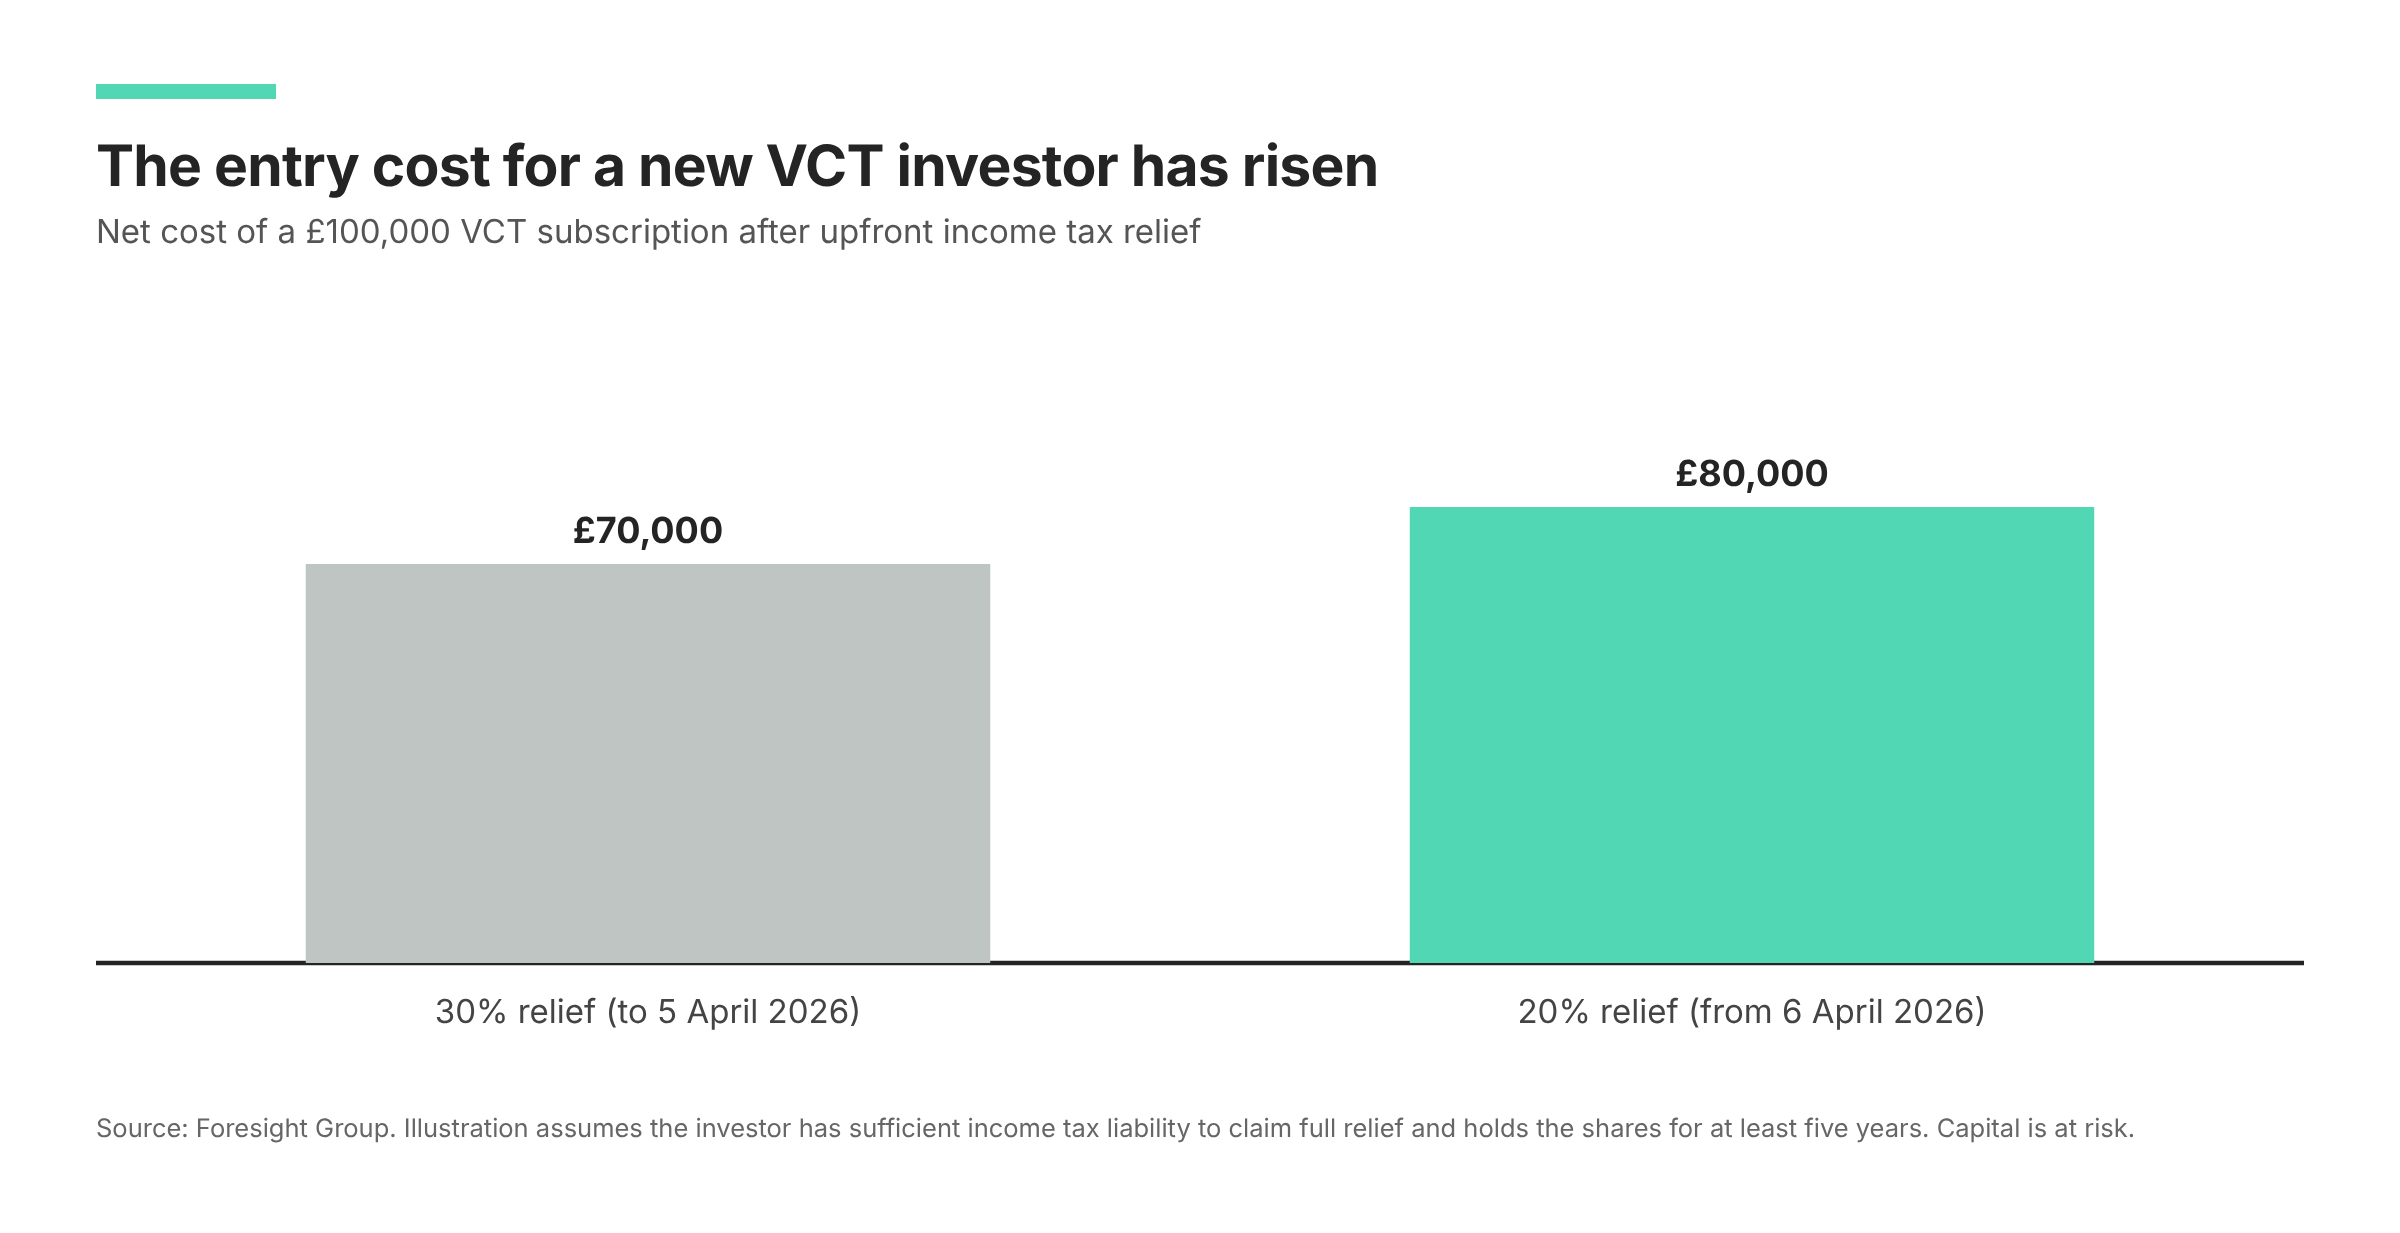
With new deal activity likely to slow, new investors may be buying into fewer early-stage companies and more mature holdings, which implies lower volatility but also less scope for exceptional gains. They will need to accept a slower pace of portfolio construction and rely more heavily on manager discipline and exit markets. Their entry cost is also higher: a £100,000 subscription now costs £80,000 after relief, rather than £70,000.

There is another way to look at it. New investors miss out on 30% relief, but they are not carrying the legacy issues, such as underperforming holdings, that long-standing investors have had to absorb over time. Building a position gradually over several tax years, and across more than one manager, remains a sensible way to manage both timing and concentration risk.

For more support on preparing clients for the changes, or to discuss how our solutions can support your planning approach, our team is ready to help. Book a meeting with your local BDM.

Book a meeting with your local Business Development Manager

Sources

1 HM Treasury, Budget 2025, 26 November 2025; Finance Act 2026, gov.uk

Show Filters

[What changes when VCT tax relief falls to 20%?
Insights
\

What changes when VCT tax relief falls to 20%?\


16 Oct 2026](https://foresight.group/news-insights/insights/2026/what-changes-when-vct-tax-relief-falls-to-20/)

[A New Era of IHT: When a pension changes the whole estate plan
Insights
\

A New Era of IHT: When a pension changes the whole estate plan\


15 Oct 2026](https://foresight.group/news-insights/insights/2026/a-new-era-of-iht-when-a-pension-changes-the-whole-estate-plan/)

[A New Era of IHT: Five checks to find the clients most exposed to the pension changes
Insights
\

A New Era of IHT: Five checks to find the clients most exposed to the pension changes\


08 Oct 2026](https://foresight.group/news-insights/insights/2026/a-new-era-of-iht-five-checks-to-find-the-clients-most-exposed-to-the-pension-changes/)

You have viewed 0 of 0

Load More

Important information

This article is issued by Foresight Group LLP (“Foresight”) which is authorised and regulated by the Financial Conduct Authority (“FCA”) under firm reference number 198020 on 8 October 2026. Foresight’s registered office is at The Shard, 32 London Bridge Street, London, SE1 9SG. This article has not been approved as a financial promotion for the purpose of Section 21 of the Financial Services and Markets Act 2000 (“FSMA”).

This article is intended for financial advisers and for information purposes only, and does not create any legally binding obligations on the part of Foresight. Without limitation, this article does not constitute an offer, an invitation to offer or a recommendation to engage in any investment activity. The information contained in this article is based on material we believe to be reliable. However, we do not represent that it is accurate, current, complete or error free. Assumptions, estimates and opinions contained in this document constitute our judgement as of the date of the document and are subject to change without notice. Opinions expressed by third parties are their own and do not necessarily reflect the views of Foresight.

Capital is at risk. The value of an investment, and any income from it, can fall as well as rise and investors may not get back the full amount they invest. Venture Capital Trusts (“VCTs”) should be considered longer-term investments and may be higher risk and more difficult to realise than an investment in listed securities. Investments will be made in small unquoted companies, which carry a higher risk than many other forms of investment. These investments will be illiquid and may expose you to a significant risk of losing all of the money you invest. VCTs usually trade at a discount to their net asset value.

Tax reliefs are dependent on the VCT maintaining its qualifying status and on investors’ individual circumstances. Current tax rules are subject to change. If a VCT loses its qualifying status, tax advantages will be withdrawn from that point. Foresight does not provide financial, legal, investment or tax advice. Past performance is not a guide to future performance and may not be repeated. Please see the relevant offering documents for full details where attention should be paid to the risk factors set out.
Home News & Insights News Foresight Energy Infrastructure Partners II completes acquisition of Nivala BESS from Fotowatio Renewable Ventures

Foresight has today announced that Foresight Energy Infrastructure Partners II SCSp (“FEIP II”) has completed its acquisition of a 100% interest in Nivala, a battery energy storage system (“BESS”) from Fotowatio Renewable Ventures. Nivala is Finland’s largest BESS project. 

Nivala is a fully permitted, ready-to-build battery energy storage system project, with a 100MW/400MWh capacity located in the city of Nivala, in the North Ostrobothnia region of Finland.  

This investment, which is Foresight’s second in Finland, following the acquisition of Puskakorpi, an 88MW in 2021 via FEIP I , strengthens FEIP II 's exposure to energy storage and grid flexibility infrastructure. With a four-hour duration, the battery is designed to participate in Finland's wholesale, intraday and ancillary services markets, a significant revenue driver for Finnish BESS, and help support the integration of renewable generation and the decarbonisation of the Finnish power system. With the acquisition, Foresight will continue to develop the project which is expected to commence commercial operations in the second half of 2028.

Finland has emerged as one of the most attractive BESS markets in the Nordics, due to rapid renewable energy growth, particularly in onshore wind. Finland also carries a positive demand side story, acting as a key hub for Europe’s data centre buildout following a recent announcement from Google to invest €13bn in data centres across Finland. Together, these tailwinds increase the need for grid flexibility and BESS.

Richard Thompson, Partner and Co-Manager of FEIP & FEIP II at Foresight Group, said: “The energy transition is no longer only about decarbonisation, it is increasingly about maintaining system security, reliability and resilience as electricity demand grows and economies become more electrified. As Finland sees accelerated investment in data centres and new industrial demand, we expect grid-scale battery storage to play an increasingly important role in providing flexibility, supporting grid stability and helping integrate more renewable power onto the system. Project Nivala provides immediate access to this critical infrastructure opportunity.”

Javier Huergo, Chief Investment Officer of FRV_,_ noted_:_ “This transaction reflects FRV’s ability to create value throughout the entire development cycle of its projects and successfully execute its asset rotation strategy. The sale of Nivala allows us to crystallise the value generated during the development phases and reinvest those resources in new opportunities that will continue to drive the energy transition and strengthen our international BESS project portfolio”.

Foresight’s BESS portfolio across Europe consists of around 550 MW of operational capacity.

Learn more about FEIP II here

Show Filters

[Foresight Energy Infrastructure Partners II partners with Gilkes Energy via strategic investment into Earba Pumped Storage Hydro

Energy Transition Infrastructure Real Assets Private Markets

News
\

Foresight Energy Infrastructure Partners II partners with Gilkes Energy via strategic investment into Earba Pumped Storage Hydro\


19 Oct 2026](https://foresight.group/news-insights/news/2026/foresight-energy-infrastructure-partners-ii-partners-with-gilkes-energy-via-strategic-investment-into-earba-pumped-storage-hydro/)

[Flood Resilience Starts Upstream: Natural Capital as Essential Infrastructure

Insights
\

Flood Resilience Starts Upstream: Natural Capital as Essential Infrastructure\


12 Oct 2026](https://foresight.group/news-insights/insights/2026/flood-resilience-starts-upstream-natural-capital-as-essential-infrastructure/)

[Energy Security, Resilience and the Next Phase of Europe's Energy Transition

Featured Energy Transition Real Assets Private Markets Homepage feature

Video
\

Energy Security, Resilience and the Next Phase of Europe's Energy Transition\


06 Oct 2026](https://foresight.group/news-insights/insights/2026/energy-security-resilience-and-the-next-phase-of-europes-energy-transition/)

You have viewed 3 of 40

Load More

Prompts

Foresight Group Holdings Limited (ticker FSG), listed in United Kingdom.

ETFs Holding Foresight Group Holdings Limited

ETF Weight in ETF Shares Market value As of
AVDV 0.02% 640,887 $ 3.857M Nov 16, 2026
DFIS 0.02% 170,876 $ 1.062M Nov 12, 2026
AVSD 0.01% 6,621 $ 39.846K Nov 16, 2026
AVDS 0.01% 9,074 $ 54.609K Nov 16, 2026
AVDE 0.00% 130,613 $ 786.047K Nov 16, 2026