THIRD QUARTER REPORT FOR PERIOD ENDED 30 SEPTEMBER 2026 ASX: WDS | NYSE: WDS Wednesday, 21 October 2026 Strong performance from improved production and pricing Performance highlights • • • • • Achieved $84/boe realised LNG price during Q3 2026, an…
THIRD QUARTER REPORT FOR PERIOD ENDED 30 SEPTEMBER 2026
ASX: WDS | NYSE: WDS
Wednesday, 21 October 2026
Strong performance from improved production and pricing
Performance highlights
•
•
•
•
•
Achieved $84/boe realised LNG price during Q3 2026, an increase of 27% compared to Q2 2026 reflecting
price lags from Q2 2026, realised values from LNG portfolio optimisation undertaken in Q2 2026 and
stronger gas hub market pricing.
Delivered quarterly operating revenue of $4,281 million, up 2% on Q2 2026 from strong LNG performance
offset by lower average realised pricing from the liquids portfolio.
Delivered quarterly production volumes of 46.2 MMboe (503 Mboe/d), up 12% from Q2 2026 reflecting
higher production from Pluto LNG following turnaround and maintenance activities completed in Q2 2026.
Achieved operational reliability of greater than 99% at Sangomar, NWS Project LNG and Pluto LNG.
Completed NWS single train planned major turnaround campaign on schedule and budget.
Project highlights
•
•
•
The Scarborough Energy Project was 99% complete and remains on budget and on track for first LNG
cargo this year.
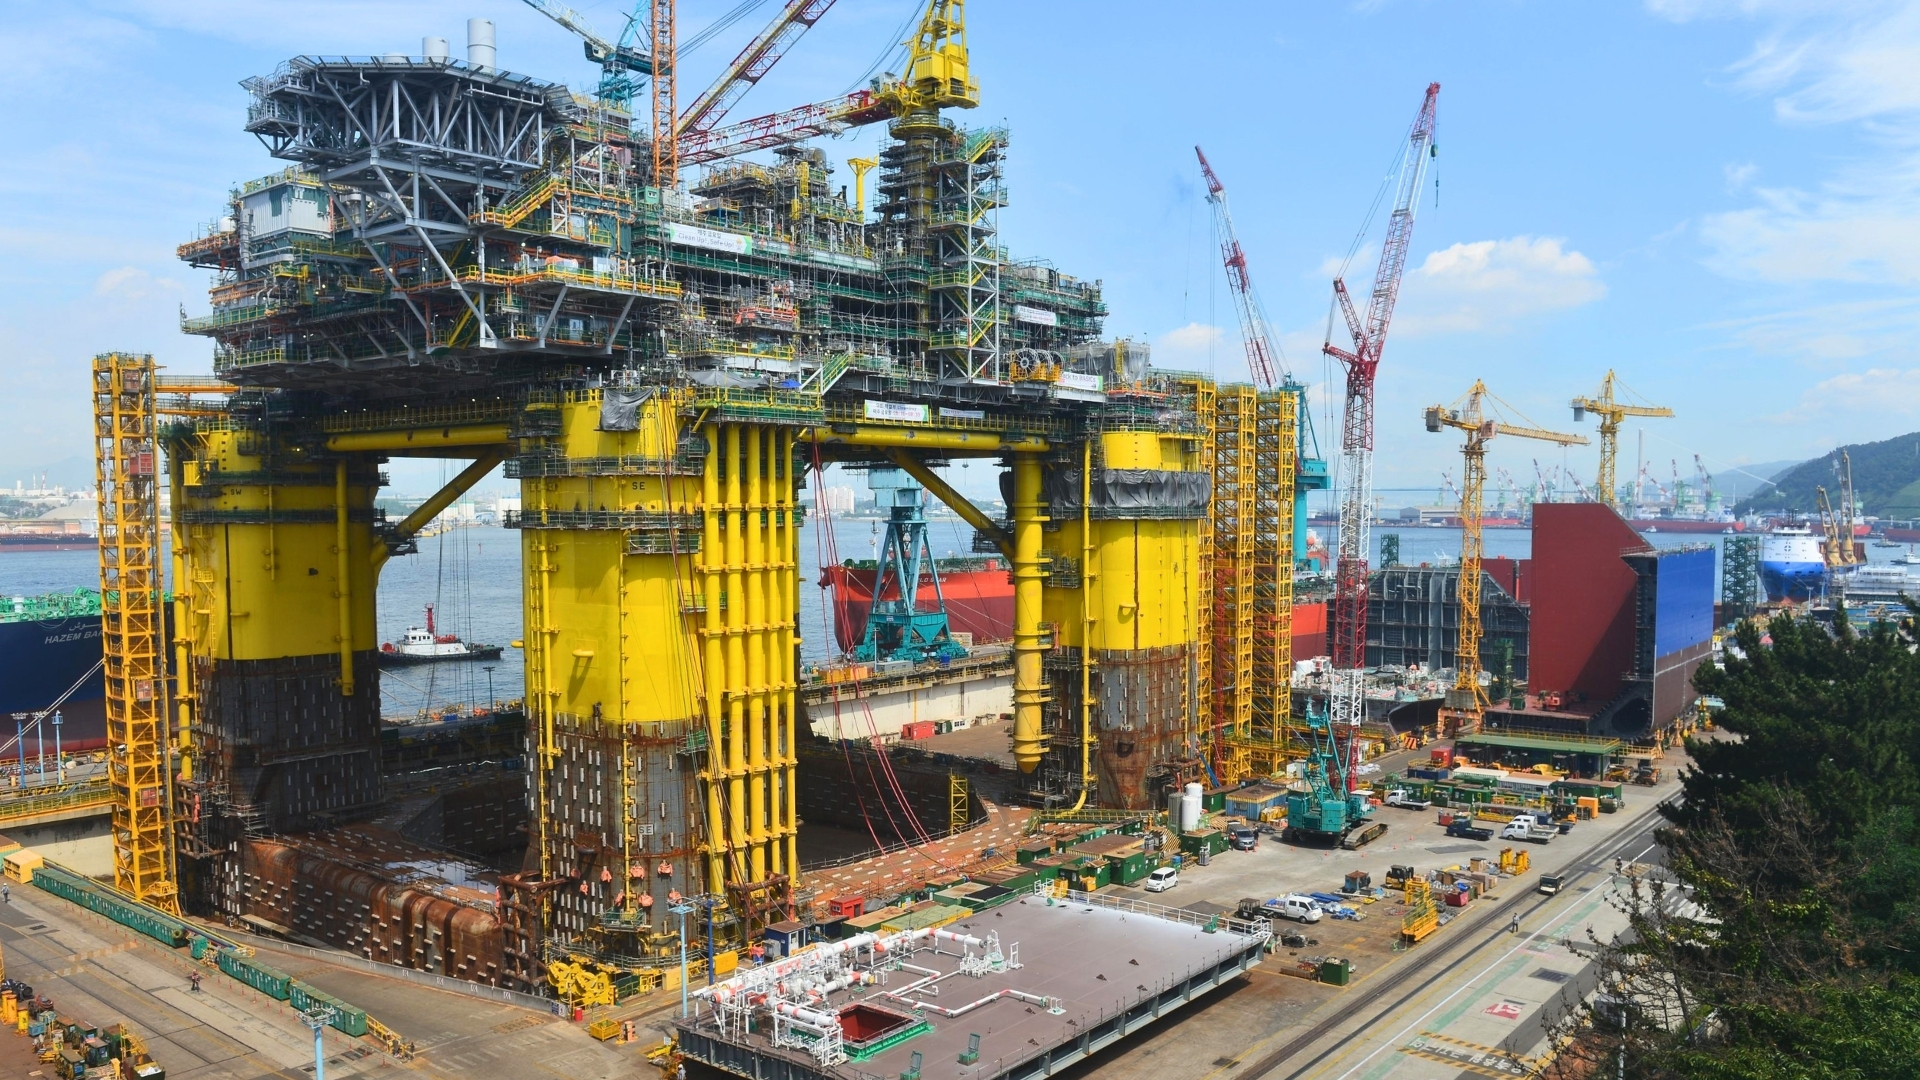
The Trion Project was 71% complete at quarter end and remains on budget, with floating production unit
(FPU) fabrication advancing to 96% completion, targeting first oil in 2028.
The Louisiana LNG Project remains on budget, targeting first LNG in 2029. It is 32% complete with Train 1
41% complete.
Business and portfolio highlights
•
•
Entered into an agreement to sell Woodside’s 70% operated interest in the Calypso Project to bp.
Completed the strategic review of Beaumont New Ammonia (BNA) and will initiate a formal process to
reduce Woodside’s investment and achieve value for shareholders.
2026 full-year guidance
Total production volumes1
Prior
MMboe
174—185
Current
174—181
Comment
•
•
•
•
Beaumont New Ammonia volumes revised to 1.5-2.5 MMboe
Narrowing of window for Scarborough first LNG cargo
Reduced production at Okha FPSO
Completion of start-up and performance testing of Julimar
Development Phase 3 in September
Gas hub exposure2
Capital expenditure3
Abandonment expenditure
Exploration expenditure
Production costs
%
$ million
$ million
$ million
$ million
~30
4,000—4,500
500—800
~200
1,500—1,800
No change
No change
No change
No change
No change
Feed gas, services and
processing costs
$ million
500—600
No change
Property, plant and equipment
depreciation and amortisation
$ million
4,200—4,700
No change
1
Total production volumes includes 1.5—2.5 MMboe from Beaumont New Ammonia (prior guidance included 2—3 MMboe).
Gas hub indices include Japan Korea Marker (JKM), Title Transfer Facility (TTF) and National Balancing Point. It excludes Henry Hub. Presented on a 3-year
average for 2026—2028. Includes binding sales and purchases agreements only, Woodside’s equity share of Scarborough and Pluto LNG, Corpus Christi offtake
volumes and assumes the Chevron asset swap is completed.
3
Capital expenditure is reported on the basis of Woodside’s net ownership interests for each project as at 30 September 2026. Louisiana LNG (90% Louisiana
LNG LLC, 60% Louisiana LNG Infrastructure LLC and 20% Driftwood Pipeline LLC) capital expenditure adjusted for the cash contributions from Stonepeak
Wallaby I Acquiror LP (Stonepeak) and Williams Louisiana LNG LLC (Williams). Scarborough (74.9% participating interest) and Pluto Train 2 (51% participating
interest). Trion (60% participating interest). Excludes the final acquisition completion payment for Beaumont New Ammonia of $470 million. Completion of the
asset swap with Chevron assumed to occur in Q4 2026.
2
1 | Third quarter report for period ended 30 September 2026
Woodside CEO Liz Westcott said the strong third quarter performance reflected the company’s highly reliable
operations and disciplined execution of major growth projects.
“Amid ongoing volatility in global energy markets, we have remained a reliable supplier to our customers.
Increased quarterly operating revenue reflected increased production and strong realised prices.
“We delivered quarterly production of 46.2 million barrels of oil equivalent, up 12% from the previous quarter
following the successful completion of the Pluto LNG turnaround in the second quarter and the NWS
turnaround in the third quarter.
“We maintained outstanding reliability across our global portfolio, with reliability of 99.8% at Pluto LNG and
99.3% at the NWS Project in Australia, and 99.2% at Sangomar in Senegal.
“We recorded three process safety events during the quarter. Safety remains our highest priority and we are
focused on applying the lessons learned from these incidents and strengthening our controls in this vitally
important area.
“We continued executing our major growth projects to budget and schedule. The Scarborough Energy Project is
now 99% complete, with gas from the Scarborough reservoir introduced into the FPU and exported into the
trunkline during the quarter. We remain on track for first LNG cargo this year.
“The Trion Project is now 71% complete and targeting first oil in 2028. Fabrication of the FPU is well advanced,
with integration and pre-commissioning activities underway.
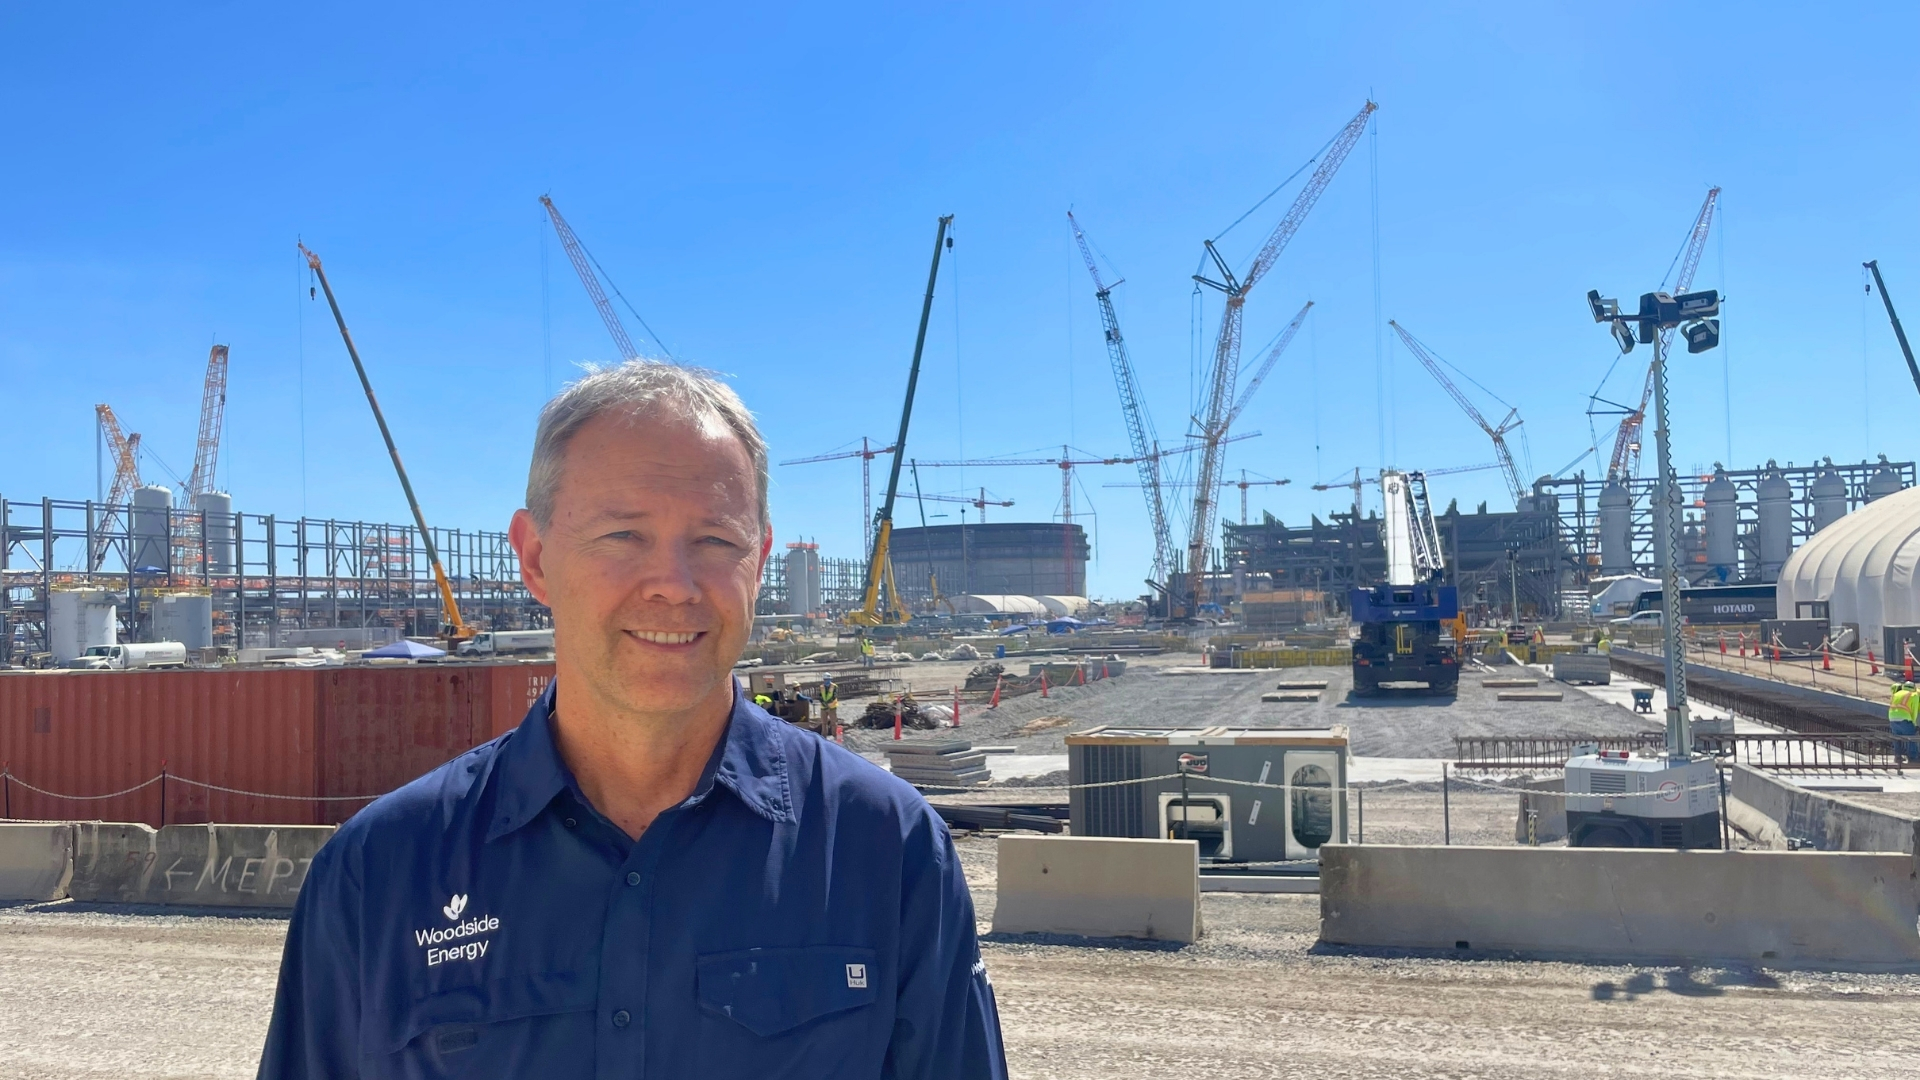
“Louisiana LNG is targeting first LNG in 2029, with construction progressing across all three trains and the
project 32% complete.
“We continued to optimise our portfolio through the ongoing integration of the Gippsland Basin assets and
divestment of our operated interest in the Calypso Project. Following completion of the Beaumont New
Ammonia strategic review, we will now initiate a formal process to reduce our investment and achieve value
for our shareholders. These actions demonstrate our disciplined approach to portfolio management and capital
allocation, with a clear focus on investments that deliver long-term shareholder value.
“We remain committed to supplying Australia’s domestic gas market and are assessing our plans for four
proposed development wells in the Bass Strait. Development will depend on technical assessments and the
implications of the Federal Government’s domestic gas reservation scheme.”
2 | Third quarter report for period ended 30 September 2026
Comparative performance at a glance
Q3
2026
Q2
2026
$ million
4,281
Production volumes4 MMboe
46.2
Operating revenue
Change
%
Q3
2025
Change
%
YTD
2026
4,185
2%
41.3
12%
YTD
2025
Change
%
3,359
27%
11,727
9,949
18%
50.8
(9%)
132.7
149.9
(11%)
Gas
MMscf/d
1,697
1,326
28%
1,827
(7%)
1,534
1,831
(16%)
Liquids
Mbbl/d
202
214
(6%)
231
(13%)
212
228
(7%)
Ammonia
kT/d
0.8
1.8
(56%)
—
—%
1.3
—
—%
Total
Mboe/d
503
454
11%
552
(9%)
486
549
(11%)
Sales volumes5
MMboe
51.1
48.0
6%
55.1
(7%)
150.9
159.9
(6%)
Gas
MMscf/d
2,043
1,672
22%
2,122
(4%)
1,910
2,049
(7%)
Liquids
Mbbl/d
193
227
(15%)
226
(15%)
213
226
(6%)
Ammonia
kT/d
1.0
2.1
(52%)
—
—%
1.3
—
—%
Total
Mboe/d
555
528
5%
599
(7%)
553
586
(6%)
$/boe
84
85
(1%)
60
40%
77
61
26%
$ million
722
784
(8%)
1,323
(45%)
2,829
3,881
(27%)
Capital
expenditure6
$ million
722
784
(8%)
1,323
(45%)
2,359
3,881
(39%)
Acquisitions
$ million
—
—
—%
—
—%
470
—
—%
Average realised
price
Capital expenditure
and acquisitions
Operations
Pluto LNG
•
•
Achieved quarterly LNG reliability of 99.8%.
Preparation for the subsea tie-in and commissioning of the XNA-03 infill well continued ahead of targeted
start-up in Q4 2026.
North West Shelf Project
•
•
•
•
Achieved quarterly LNG reliability of 99.3%.
Completed single LNG train planned turnaround campaign in September 2026 on budget and schedule.
Hearings on three legal proceedings in the Federal Court of Australia associated with the NWS Project
Extension Commonwealth environmental approvals were held in July 2026, with the decisions reserved. A
separate proceeding concerning the State environmental approval remains before the Supreme Court of
Western Australia, with a hearing scheduled for Q4 2026.
The NWS Project is continuing with infrastructure retirement planning at Karratha Gas Plant (KGP) while
maintaining the capacity to provide processing services for third-party gas. Planning is underway to retire
a second LNG train in 2027 subject to relevant approvals.
Wheatstone and Julimar-Brunello
•
•
Progressed towards asset swap transaction completion, including the satisfaction of certain conditions
precedent relating to the following:
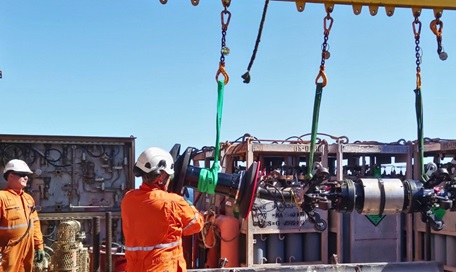
◦ Completion of the Julimar Development Phase 3 project, with start-up and performance testing of the
final development wells completed in September 2026.
◦ Completion of decommissioning of three Julimar-Brunello exploration wells, and wellhead severance
of a further two previously-abandoned exploration wells.
Subject to the receipt of all regulatory approvals, the asset swap transaction continues to target
completion in Q4 2026.7
Percent change in total production may differ from percent change in daily production due to the number of days in each quarter.
Restated additional volumes of 0.09 MMboe in Q3 2025 and 0.28 MMboe in YTD 2025 to reflect a revised MMBtu to boe conversion factor.
Louisiana LNG YTD 2026 project spend includes $185 million of prepayments recognised in investing cash flow that are recoverable through partner cash calls
but are not yet recognised as capital expenditure.
7
Completion of the transaction is subject to the remaining conditions precedent. See “Woodside simplifies portfolio and unlocks long-term value” announced on
19 December 2024.
4
5
6
3 | Third quarter report for period ended 30 September 2026
Bass Strait
•
•
•
Achieved quarterly reliability of 91%.
Achieved completion of the five Turrum Phase 3 Project development wells with first production targeting
H1 2027.
Progressed integration of the Gippsland Basin assets into Woodside’s operated portfolio following transfer
of operatorship from ExxonMobil on 1 July 2026.
Other Australia
•
•
Following remediation of a subsea mooring system defect and successful FPSO reconnection, production
resumed at Okha, with ongoing well assessment supporting further production restoration.
Subsequent to the period, the Pyrenees floating production storage and offloading (FPSO) disconnected
ahead of scheduled shipyard activity in Q4 2026.
Sangomar
•
•
Achieved an average daily production rate of 94 Mbbl/d (100% basis, 73 Mbbl/d Woodside share) with
reliability of 99.2%.
Production rate reflects natural field decline and reduced production sharing contract (PSC) net
entitlement following recovery of 100% Woodside-funded pre-FID costs.
Gulf of America
•
•
•
Achieved quarterly reliability of 94.3% at Shenzi.
Executed a planned shutdown at Shenzi in July 2026 and a three-well intervention campaign in August
2026.
Atlantis achieved start-up of the Major Facility Expansion (MFX) project, bringing the first of two water
injectors online. The project added subsea infrastructure, wells and upgraded water injection equipment.
Beaumont New Ammonia
•
•
•
•
BNA suspended operations for approximately 30 days following a Tier 1 process safety event. There were
no injuries to personnel or damage to equipment and no lasting impact to the environment. The facility
was safely restarted following completion of an internal investigation and implementation of appropriate
actions.
Production during the quarter was constrained to 69% of nameplate capacity due to third-party feedstock
availability and the 30 day shut down. Third-party cargoes were sourced to satisfy customer commitments
on similar financial terms.
Commencement of lower-carbon ammonia production remains targeted for 2027, subject to
commissioning of Linde’s low-carbon hydrogen facilities and start-up of ExxonMobil’s carbon capture and
storage (CCS) infrastructure. During the quarter, the Texas Railroad Commission voted to approve the
permit for ExxonMobil’s Rose carbon storage project, moving it into the final stages of a multi-year
regulatory process.
Completed the strategic review of BNA. In light of the evolving pace of lower-carbon ammonia market
development, Woodside will initiate a formal process to reduce its investment in BNA investment and
achieve value for shareholders.
Marketing
Revenue and trading
•
•
•
•
Strong marketing performance reflected the realisation of value from LNG portfolio optimisation
undertaken in Q2 2026, with revenue recognised as cargoes were delivered in Q3 2026.
Average realised LNG prices improved quarter-on-quarter, reflecting the realisation of price lags from Q2
2026 and stronger gas hub market pricing in the lead up to northern hemisphere winter months.
Approximately 33% of LNG sold was linked to gas hub indices during the quarter.
The impact of crude supply disruptions softened during the quarter as export flows recovered and market
balances improved, resulting in lower market prices for crude oil and weaker realised premiums for the
liquids portfolio (oil, condensate and liquids traded).
Pipeline gas
•
Executed incremental pipeline gas sales of:
4 | Third quarter report for period ended 30 September 2026
•
◦ 12.9 PJ to be delivered to the Western Australian market from 2027 to 2029
◦ 18.4 PJ to be delivered to the East Coast market from 2026 to 2028.
Progressed expression of interest for 20 PJ of Bass Strait supply and finalised a number of 2027 and 2028
offers during the period.
Projects
Scarborough Energy Project
•
•
•
•
•
The Scarborough and Pluto Train 2 projects remain on budget and were 99% complete at the end of the
quarter (excluding Pluto Train 1 modifications).
The FPU and subsea production system commissioning and start-up activities continued, including well
clean-up and export of gas to pressurise the trunkline. Well clean-up results are in line with reservoir and
well performance expectations.
Completed all mechanical runs of Pluto Train 2 compressors and, subsequent to the period, Scarborough
gas was introduced to the warm end (gas pre-treatment) of the LNG train. Activities in the cold end
continue to progress, which will enable the commencement of gas liquefaction.
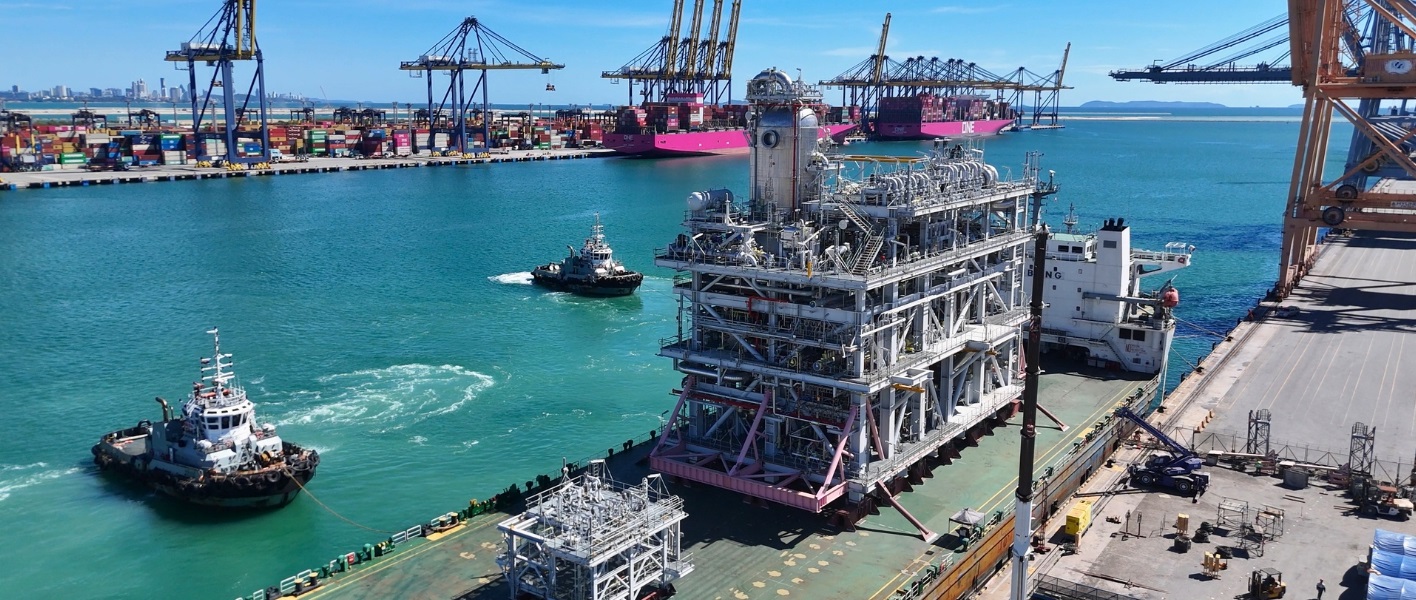
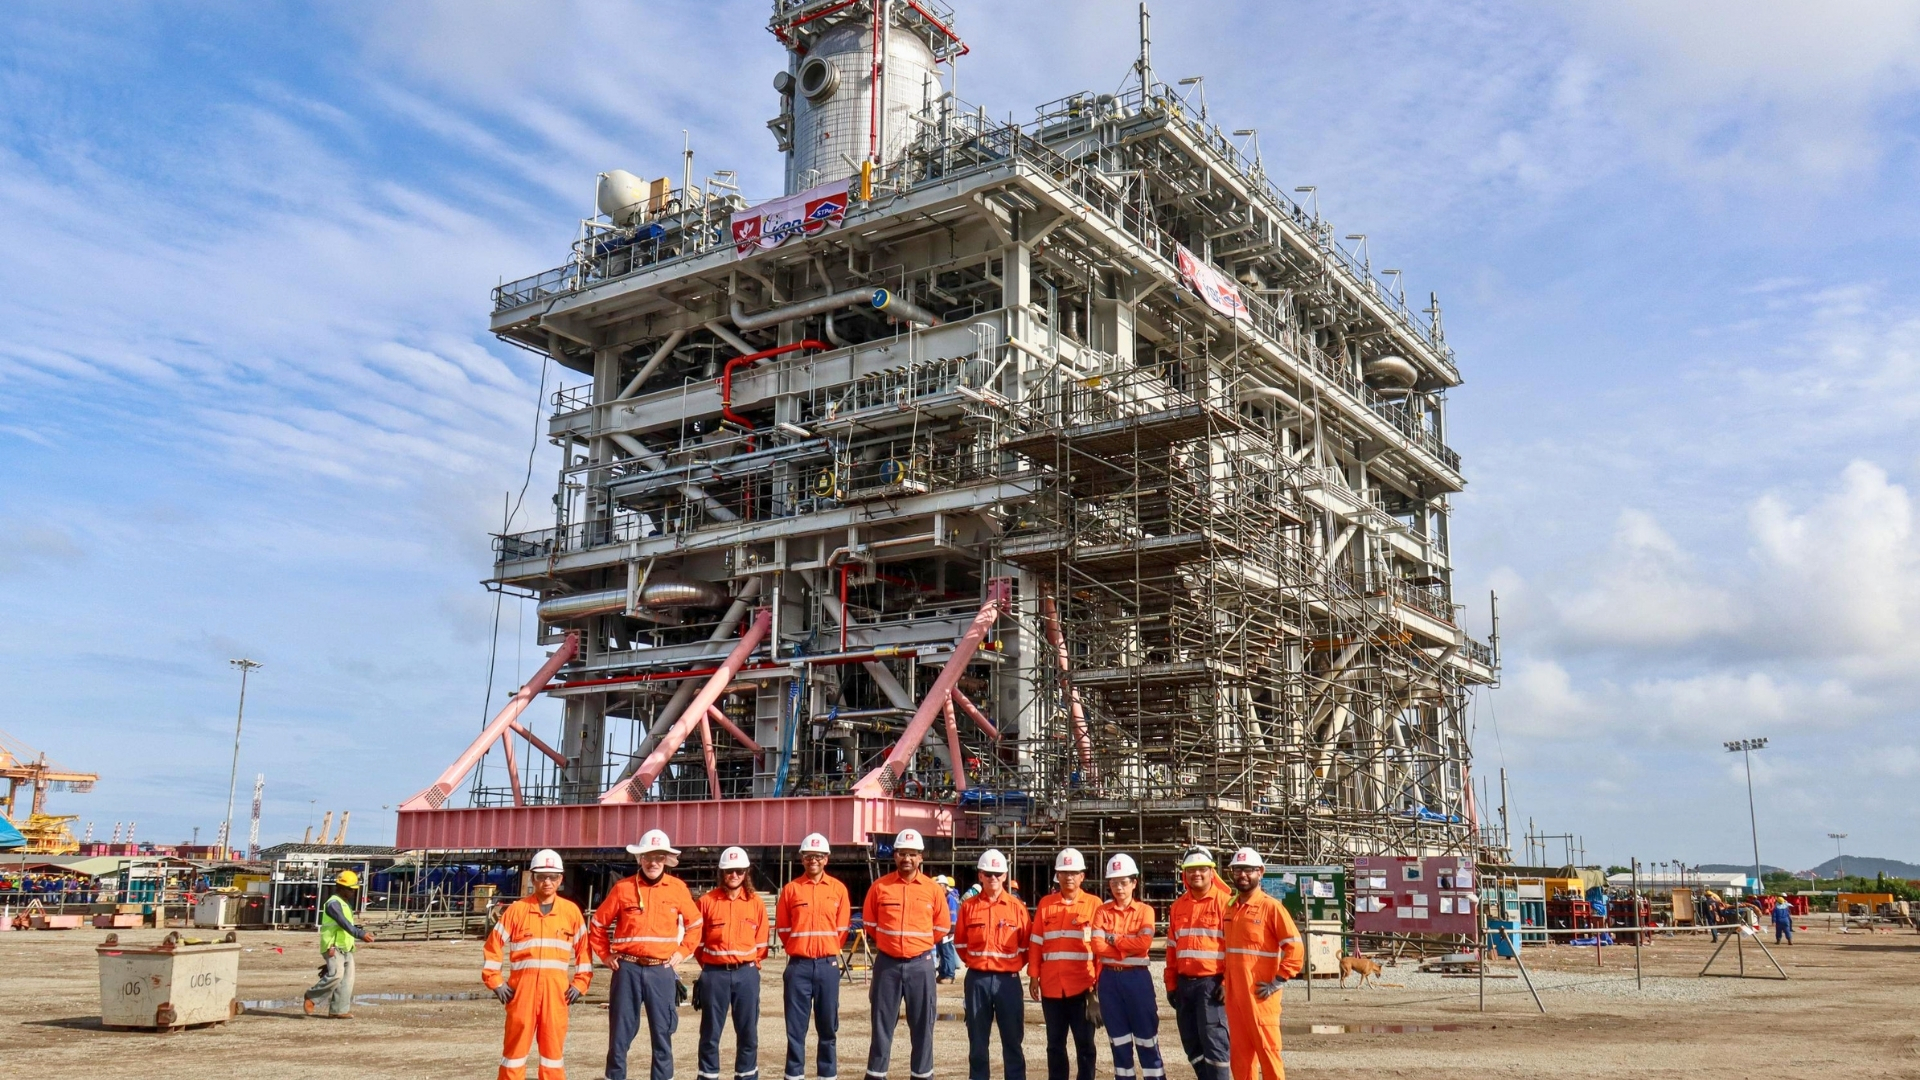
Following the Pluto Train 1 planned major maintenance campaign in Q2, modifications to Pluto Train 1
which will allow processing of Scarborough gas continued. The final module arrived onsite with activities
focused on module hook-up and integration.
First LNG cargo is on track for Q4 2026.
Trion
•
•
•
•
•
•
The Trion Project remains on budget and was 71% complete at the end of the quarter.
Advanced the drilling campaign, with 10 of 24 wells drilled and the first subsea tree installed.
Delivered subsea equipment and disconnectable turret mooring (DTM) buoy to Mexico and commenced
offshore installation.
The FPU fabrication reached 96% completion, with integration and pre-commissioning activities underway.
Progressed floating storage and offloading vessel construction, including completion of DTM turret
integration into the hull.
The project is targeting first oil in 2028.
Louisiana LNG
•
•
•
•
•
•
•
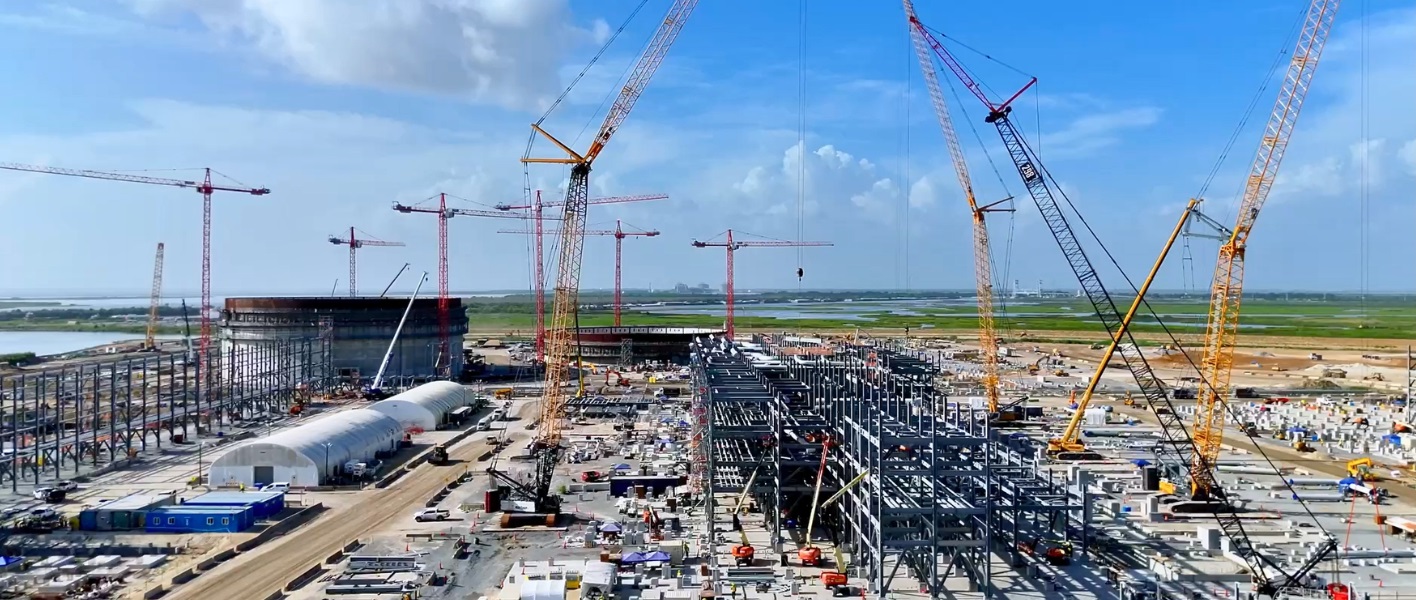
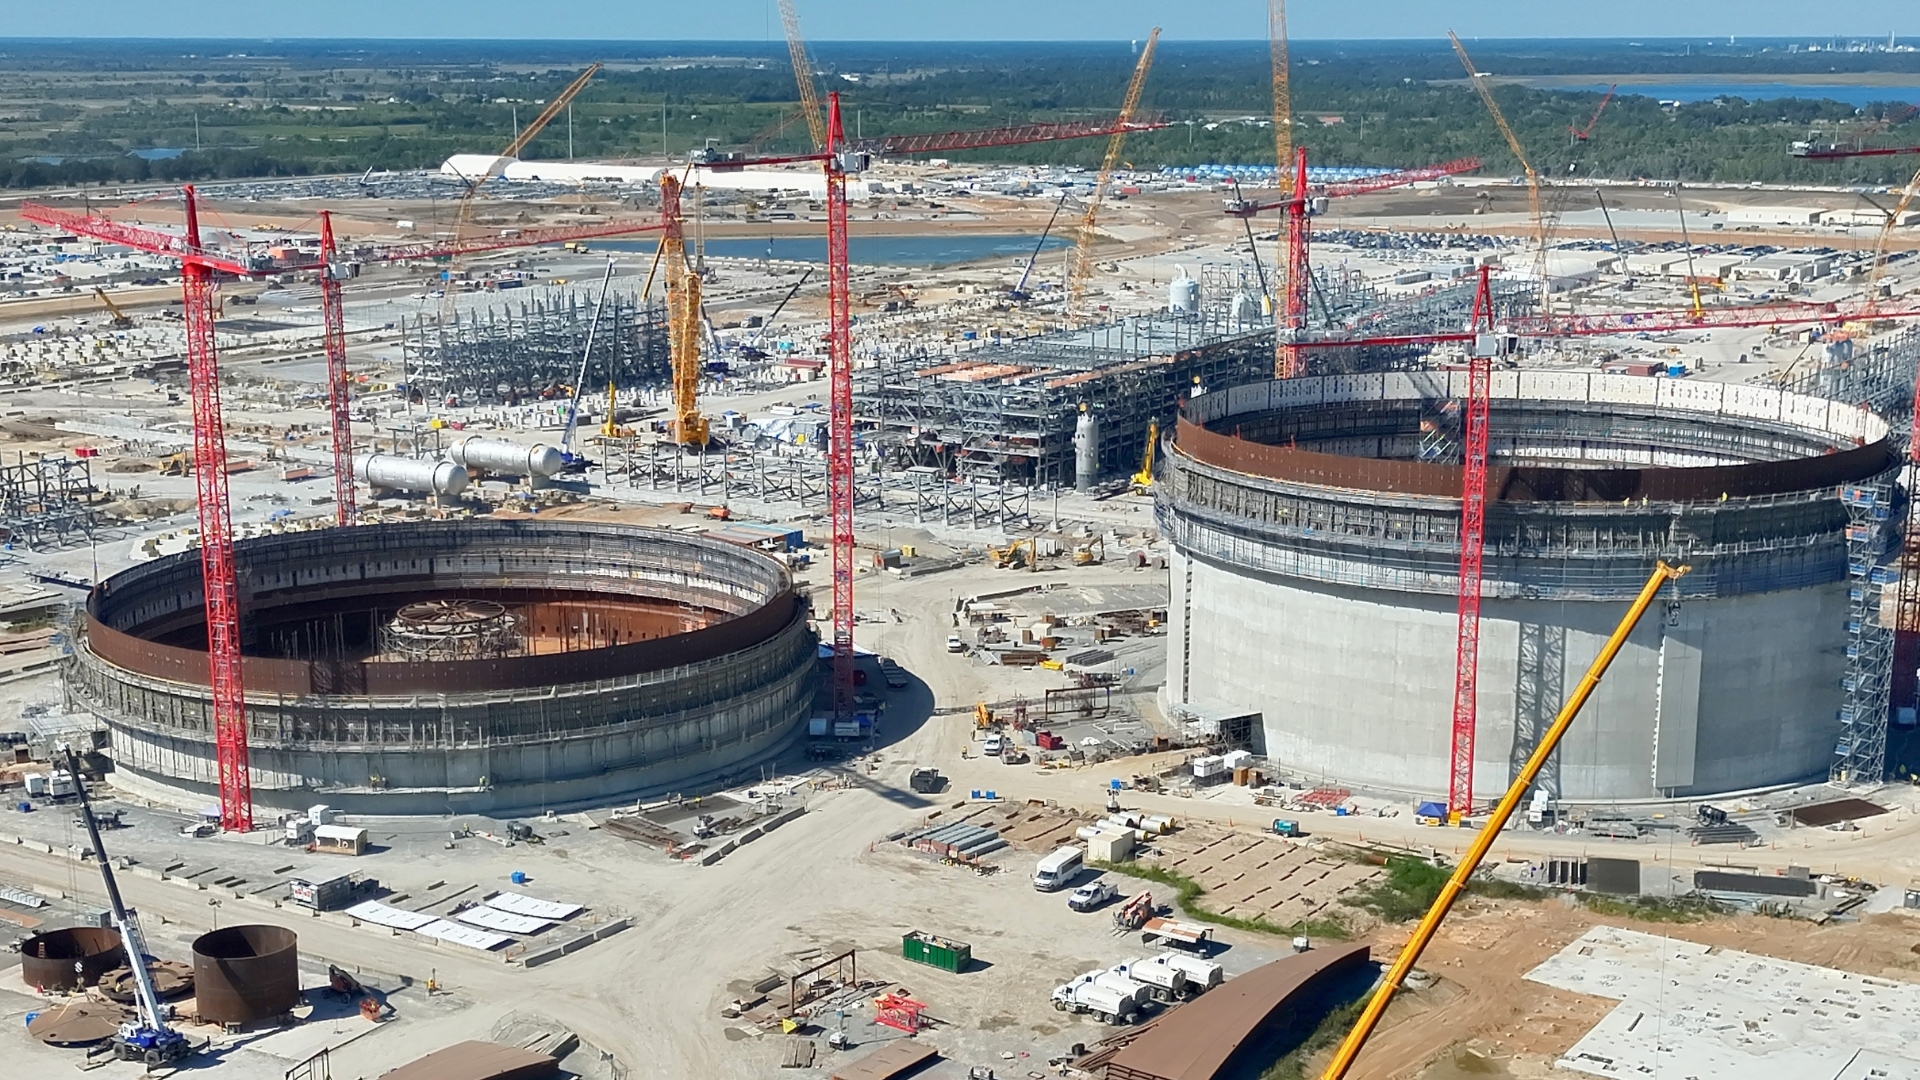
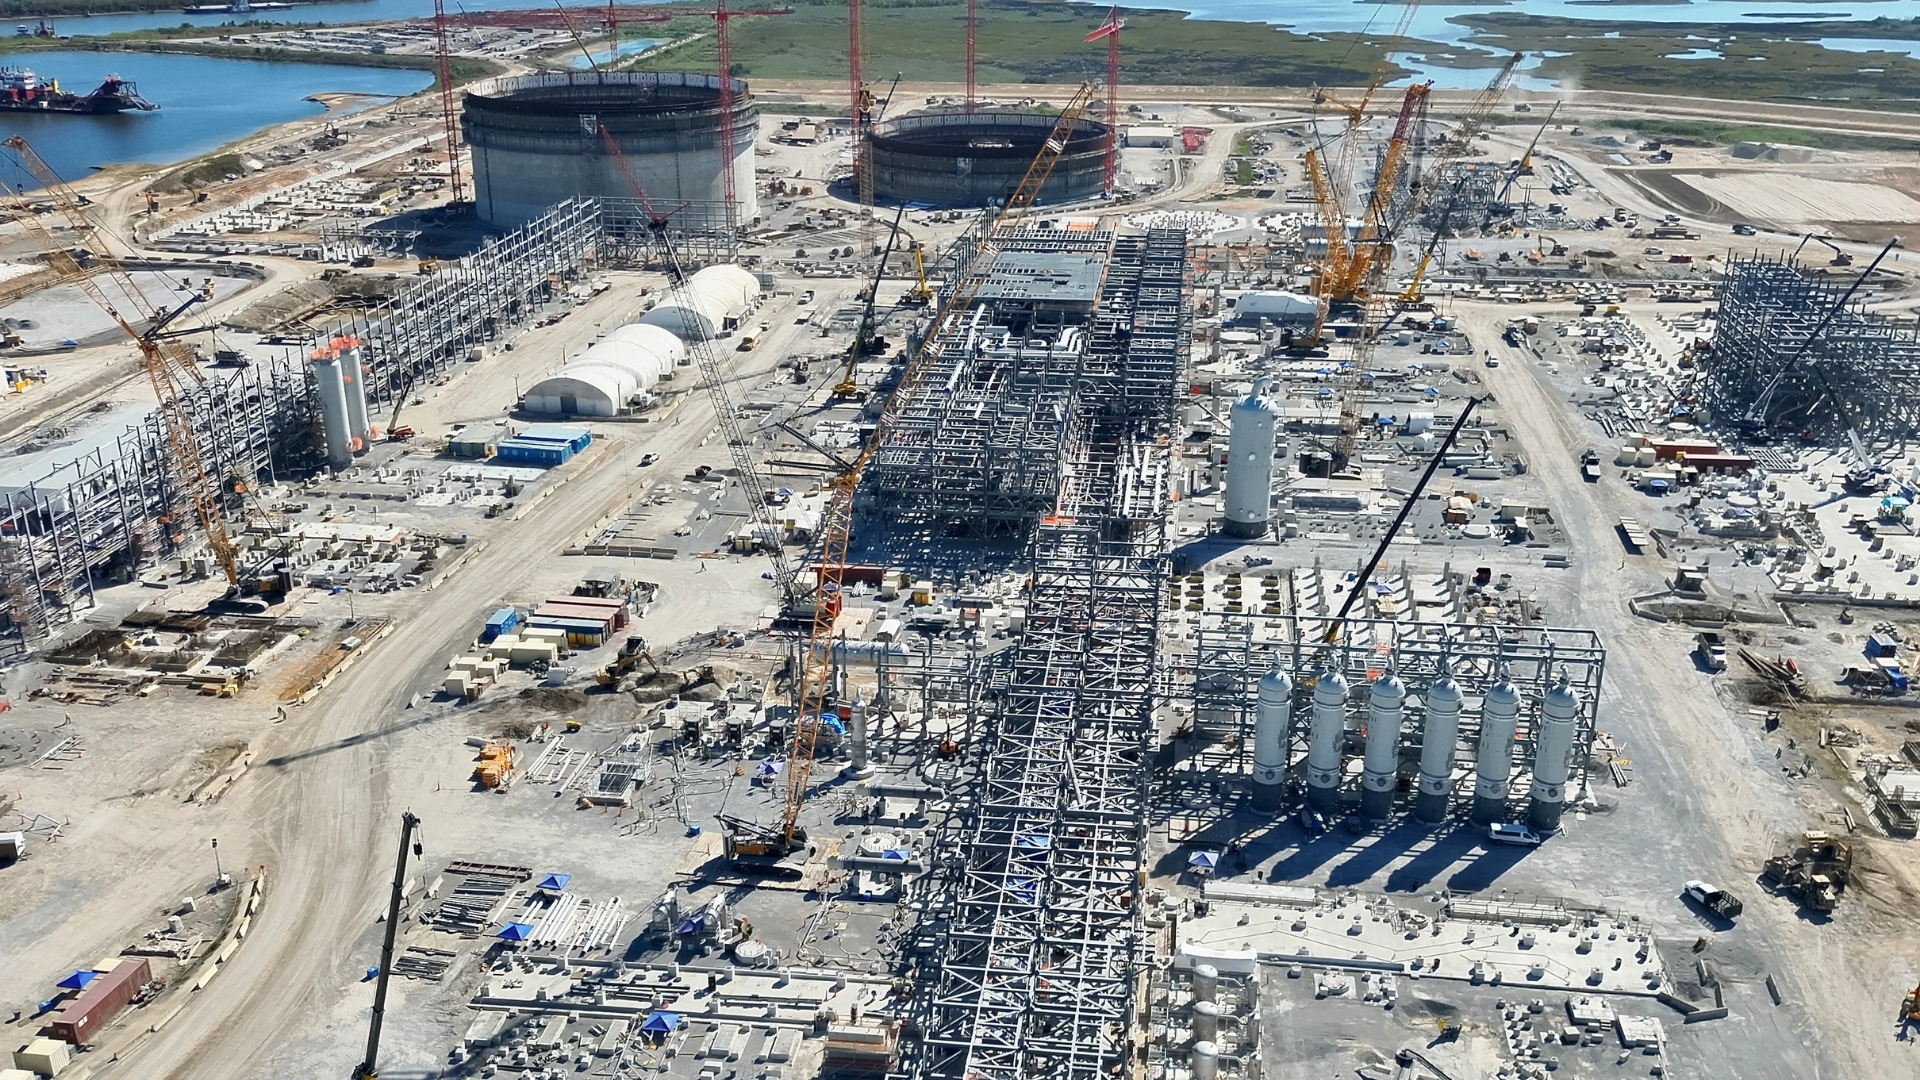
The Louisiana LNG Project remains on budget and was 32% complete at the end of the quarter.
LNG terminal construction advanced across marine, site works and LNG tanks, with LNG Tank 1 wall
concrete reaching 50% completion.
Train 1 was 41% complete at the end of the quarter, with structural steel and above-ground piping
installation progressed.
Trains 2 and 3 were 27% and 22% complete respectively at the end of the quarter, with above-ground
piping installation commenced for Train 2 and first concrete foundation poured for Train 3.
Structural steel supply challenges associated with ongoing disruptions in the Middle East continue to be
mitigated through alternative logistics routes and fabrication sources.
Ongoing engagement with high-quality counterparties for equity participation and LNG offtake continues.
The project is targeting first LNG in 2029.
Hydrogen Refueller @H2Perth
•
Ready for start-up was achieved and commissioning activities continued onsite with first hydrogen
production targeting Q4 2026.8
Decommissioning
•
•
Completed the plug and abandonment (P&A) of five wells in the Julimar-Brunello and NWS gas fields.
Commenced offshore wellhead severance across the NWS gas, NWS oil and Julimar-Brunello fields, with
nine wellheads removed.
The project has received funding from the Hydrogen Fuelled Transport Project Funding Process as part of the Western Australian Government’s Renewable
Hydrogen Strategy.
8
5 | Third quarter report for period ended 30 September 2026
•
•
•
Continued progress across the Gippsland Basin Joint Venture wells P&A campaign, including conductor
recovery activities at the Cobia field, completion of preparatory work for the Snapper campaign and
commencement of the Barracouta A P&A campaign.
Progressed execution readiness for the offshore Echo Yodel pipeline removal campaign.
Submitted and secured NOPSEMA acceptance of Enfield decommissioning project close-out
documentation.
Development and exploration
Browse
•
•
•
The Browse to North West Shelf Project continues to advance technical definition, regulatory approvals
and commercial agreements as part of pre-front end engineering design activities.
Continued engagement with regulators to progress environmental approvals. Following submission of the
revised Environmental Protection and Biodiversity Conservation Act 1999 referral, the Commonwealth
regulator has determined that the Browse Carbon Capture and Storage (CCS) Project will be assessed by
Environmental Impact Statement.
Progressed market engagement for the design and construction of the FPSO facilities and engineering
studies of downstream modifications required for processing Browse gas at Karratha Gas Plant.
Sunrise
•
•
The Sunrise Joint Venture reached alignment with the Governments of Timor-Leste and Australia on the
key principles underpinning a new Greater Sunrise PSC and associated fiscal framework.
The terms of the existing PSCs (JPDA PSC 03-19 and JPDA PSC 03-20) were extended to 31 March 2027 to
facilitate implementation of the new PSC arrangements.
Calypso
•
•
On 6 August 2026, Woodside entered an agreement to sell its 70% operated interest in the Calypso Project
to bp.9
All key conditions precedent have now been met, with completion of the transaction targeting Q4 2026.
Exploration
•
•
•
The Nasim-1X well, operated by ENI, was spud on the Tiba license in Egypt in August 2026 and drilling
activities are ongoing. Woodside holds a 40% non-operated interest.
Woodside was awarded one lease in the US Gulf of America where Woodside was the successful bidder
from the Big Beautiful Gulf 3 Lease Sale held in August 2026.
Entered a non-binding memorandum of understanding with Petrόleos Mexicanos (PEMEX) to evaluate
deepwater opportunities in the Gulf of Mexico.
Corporate activities
Cost reduction
•
•
•
Woodside continued to progress the cost reduction program during the quarter, focused on improving
efficiency and productivity.
Initiatives underway include simplifying organisational structures, improving maintenance and contracting
processes, and expanding the use of automation and AI.
The program is targeting to deliver a US$350 million structurally lower recurring cost base against the
2025 baseline from 2028.
Climate and sustainability
•
9
Three process safety events were recorded during the quarter.
◦ A Tier 1 event at BNA (refer to the BNA section for details).
◦ Two Tier 2 events involving:
◦ a marine diesel oil release during flushing operations at Okha, which had no environmental
impact as the release was contained.
◦ a methane release from pipework during turnaround activities at KGP.
Completion of the transaction is subject to the remaining conditions precedent. See “Woodside rationalises global portfolio with Calypso divestment”.
6 | Third quarter report for period ended 30 September 2026
•
The Sam Houston Jones State Park Project, a voluntary environmental and biodiversity restoration
initiative located 15 miles from LALNG, has progressed, with approximately 50% of site preparation
completed ahead of seedling planting.
Hedging
•
•
•
As at 30 September 2026, approximately 87% of the 30 MMboe of 2026 oil-linked production previously
hedged (at an average price of $74.23 per barrel) had been cash settled. No additional oil-linked corporate
hedges were entered during the quarter and the 2027 hedge position of 10 MMboe remains unchanged.
Continued to utilise Henry Hub and TTF commodity swaps in connection with overall management of
Corpus Christi LNG volumes.
For 2026 year to date, hedge settlements resulted in a net cash outflow of approximately $565 million, and
a reduction to pre-tax profit of $519 million. Cash settlements on oil-linked hedges occur in advance of the
related profit and loss impact, resulting in temporary differences.
Embedded commodity derivative
•
•
•
In 2023, Woodside entered a revised long-term gas sale and purchase contract with Perdaman. A
component of the selling price is linked to the price of urea, creating an embedded commodity derivative
in the contract. The fair value of the embedded derivative is estimated using a Monte Carlo simulation
model.
As there is no long-term urea forward curve, TTF continues to be used as a proxy to simulate the value of
the derivative over the life of the contract.
For 2026 year to date, an unrealised pre-tax loss of approximately $179 million is expected to be
recognised through other expense.
Funding and liquidity
•
•
During the quarter Woodside paid a fully franked dividend of $1,084 million and an $800 million bond
maturity in September.
As at 30 September 2026, Woodside had liquidity of approximately $7,800 million and net debt (including
lease liabilities) of approximately $8,900 million.
Capital Markets Day
•
•
•
Woodside’s 2026 Capital Markets Day will be held on Thursday, 5 November 2026, commencing at 10:00
am AEDT/7:00 am AWST/5:00 pm CST (Wednesday, 4 November 2026).
A live webcast of the Australian event will be available on Woodside’s website at https://
meetings.lumiconnect.com/300-191-159-742.
This will be followed by a US Capital Markets Day on 12 November 2026 in New York.
Upcoming events 2026-2027
November
5
2026 Capital Markets Day (Australia)
12
2026 Capital Markets Day (United States)
January
28
Fourth Quarter Report
February
23
2026 Annual Report
April
21
First Quarter Report


 |
 |